


Western Digital (WDC) just put fresh numbers on the board, reporting first quarter fiscal 2027 revenue of US$4.4b and guiding for higher sales, stronger margins, and increased earnings in the next period.
Western Digital’s share price closed at US$356.13 after a 3.63% one day gain. However, the stock has pulled back with a 30 day share price return of down 22.04% and a 90 day move of down 23.17%. At the same time, the year to date share price return of 89.73% and a three year total shareholder return of very roughly 10x show that momentum has largely been built over a longer stretch and is now being tested as investors weigh strong earnings and dividend growth against how much future demand is already reflected in the valuation.
Spot opportunities that follow the same AI and data storage theme as Western Digital by scanning our hand picked list of 55 AI infrastructure stocks.Bulls point to Western Digital’s earnings surge and tight memory supply, while bears see a stock that already priced in years of AI demand. Which side does the current valuation actually support?
Most Popular Narrative: 8% Overvalued
Western Digital closed at $356.13 against a widely followed fair value narrative of $329.76, so the story now hinges on how long current margins can hold rather than whether AI demand is real.
Which brings the whole debate down to a single assumption. This narrative assumes net margins settle near 23% over the next 10 years. That is well below today's flattered 54%, and below the true underlying peak too, but it is still far above the roughly 7% the wider tech hardware industry earns. In plain terms, it assumes WDC keeps most, but not all, of its newfound pricing power. The market is already paying up for the optimistic end of that range, so the margin you believe in is, more or less, the valuation you believe in. Trust the oligopoly to hold, and 23% may prove conservative. Trust Bezos, and it may prove generous.
See why 39 investors see Western Digital as 8% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s story could shift quickly if AI data center orders slow or if a deep‑pocketed rival decides to add aggressive new HDD capacity.
Find out about the key risks to this Western Digital narrative.
Another View: Western Digital Through The P/E Lens
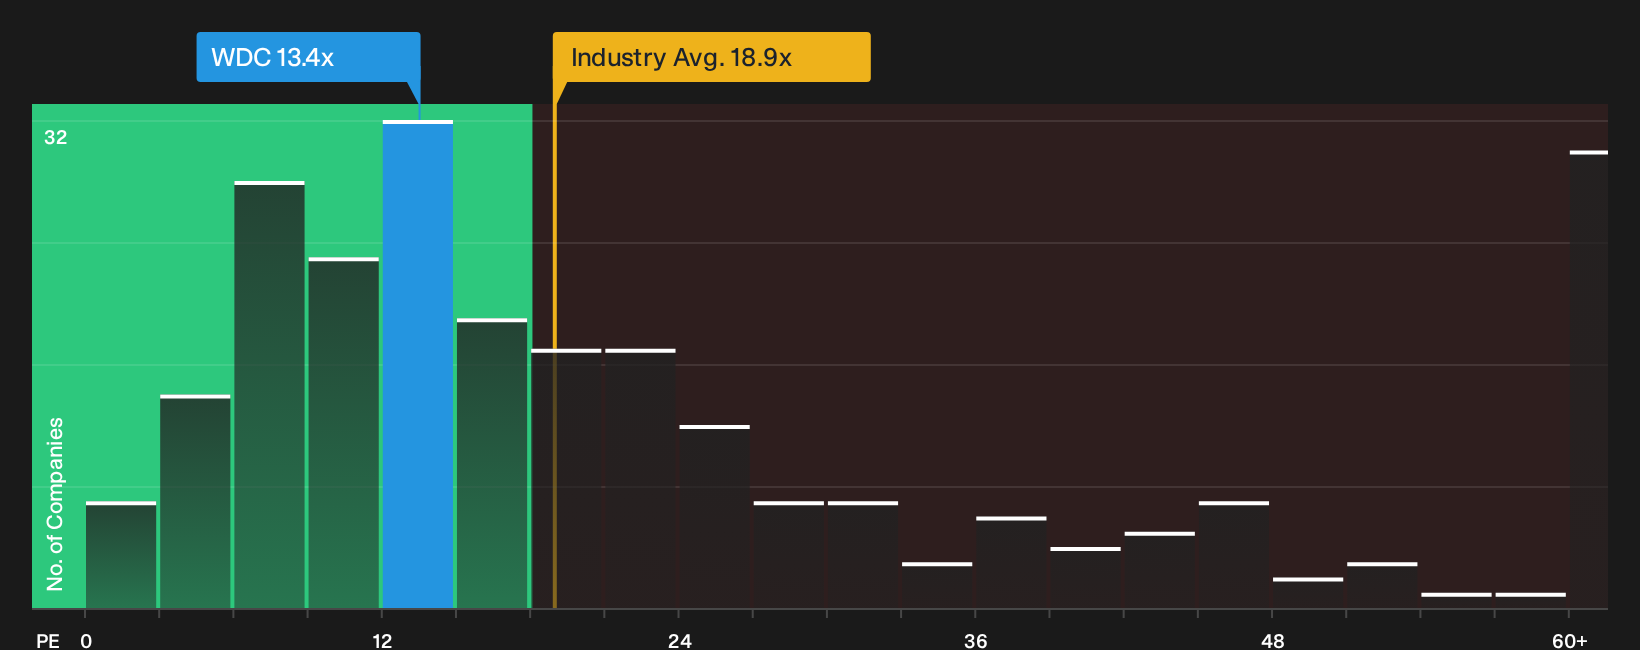
There is a very different story hiding in Western Digital’s earnings multiple. At a P/E of 13.4x versus 18.9x for the global tech sector and 29.3x for direct peers, the stock trades at a steep discount even though the fair ratio is listed at 48.2x. If the market moves even part of the way toward that fair ratio, current pricing could reflect more caution than exuberance.
That gap cuts both ways, however. A low P/E can signal opportunity, or it can signal investors questioning how long current margins and forecasts might hold up. Which explanation seems more convincing to you on a three to five year view?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these are exactly when independent work matters most. Move quickly, pull up the underlying data, and weigh both the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Western Digital?
If Western Digital has sharpened your focus on where capital goes next, do not stop here. Broaden your watchlist now so you are not chasing the crowd later.
- Target potential mispricing by scanning a focused set of quality opportunities through our 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies built around reliable payouts using the 5 dividend fortresses.
- Dial down portfolio stress by concentrating on resilient businesses with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com