


- Almonty Industries reported revenue of C$43 million in Q2 2026, driven by the Sangdong tungsten mine moving into commercial processing and backed by extended offtake commitments and fresh cash from a convertible bond.
- The business now carries a Pentagon linked tungsten supply role just as upcoming U.S. restrictions on Chinese tungsten imports approach. At the same time, legal settlements and an auditor change create a more complex backdrop for assessing earnings quality.
- We will now look at how Almonty Industries’ investment narrative could be reshaped by Sangdong’s commercial ramp and related earnings questions.
What Is Almonty Industries' Investment Narrative?
The big picture with Almonty Industries is simple. You need to believe this is becoming a serious tungsten producer anchored by Sangdong, with offtake backing and access to capital to keep that mine running hard. The recent analyst and investor day fits squarely into that story, because it is management’s chance to reset expectations around the commercial ramp, explain capital needs after the convertible bond, and address how legal settlements and the auditor switch affect reported earnings quality.
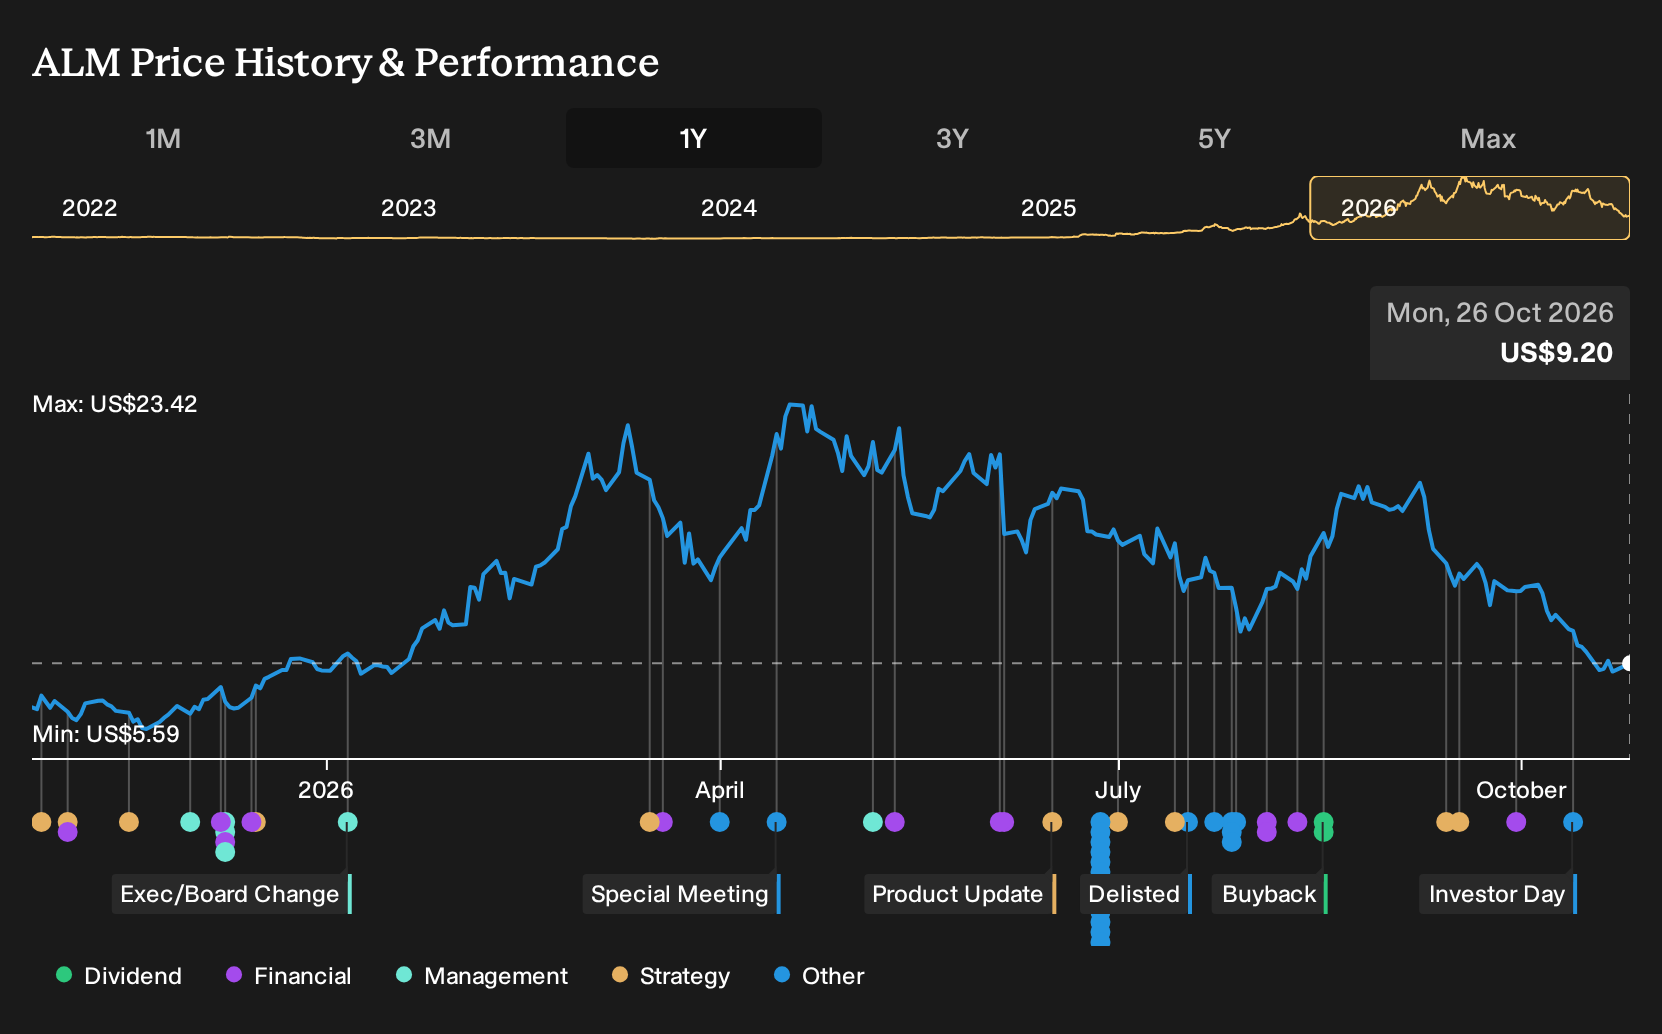
In the short term, the key swing factors are still operational and financial execution at Sangdong, tungsten pricing, and how much of current profit reflects non cash items. Analysts cutting near term EPS expectations suggests more caution around that earnings mix rather than a change in the underlying tungsten theme. The share price drop from the 52 week high signals that funding structure, insider selling, and past dilution remain front of mind for the market.
That said, the picture around Almonty Industries starts to look very different once you focus on one uncomfortable detail around ...
There's only one way to know the right time to buy, sell or hold Almonty Industries. Head to Simply Wall St's company report for the latest analysis of Almonty Industries's Fair Value.
Exploring Other Perspectives
For Almonty Industries, the most bearish twist in the story is the risk that Sangdong’s expansion and the US$800m convertible notes fail to convert into the earnings profile some expect. The lowest analysts were pencilling in revenue of about CA$996.7m and earnings near CA$594.7m by 2029, yet still saw that as rich for today’s P/E. Those forecasts and the recent analyst day were set before the latest news, so consider them moving parts rather than fixed figures and use them as reference points while you weigh your own view.
Explore 3 other Almonty Industries fair value estimates, including one that suggests it could be worth just $15.26!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Almonty Industries research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Almonty Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Almonty Industries' overall financial position at a glance.
Looking For More Investment Ideas Beyond Almonty Industries?
If the tungsten story around Almonty Industries has sharpened your interest in niche themes and resilient business models, it can help to widen the lens and compare it with other opportunities that share some of the same qualities you value.
- If capital preservation and steadier price swings matter most to you, start with a group of companies screened for resilience by checking out 30 resilient stocks with low risk scores.
- If quality at a reasonable entry point is the priority, weigh Almonty Industries against a broader field of potential bargains by scanning 29 high quality undervalued stocks.
- If you care about financial strength and cleaner balance sheets, round out your watchlist with our list of solid balance sheet and fundamentals (24 results) to see which businesses carry less leverage and stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com