


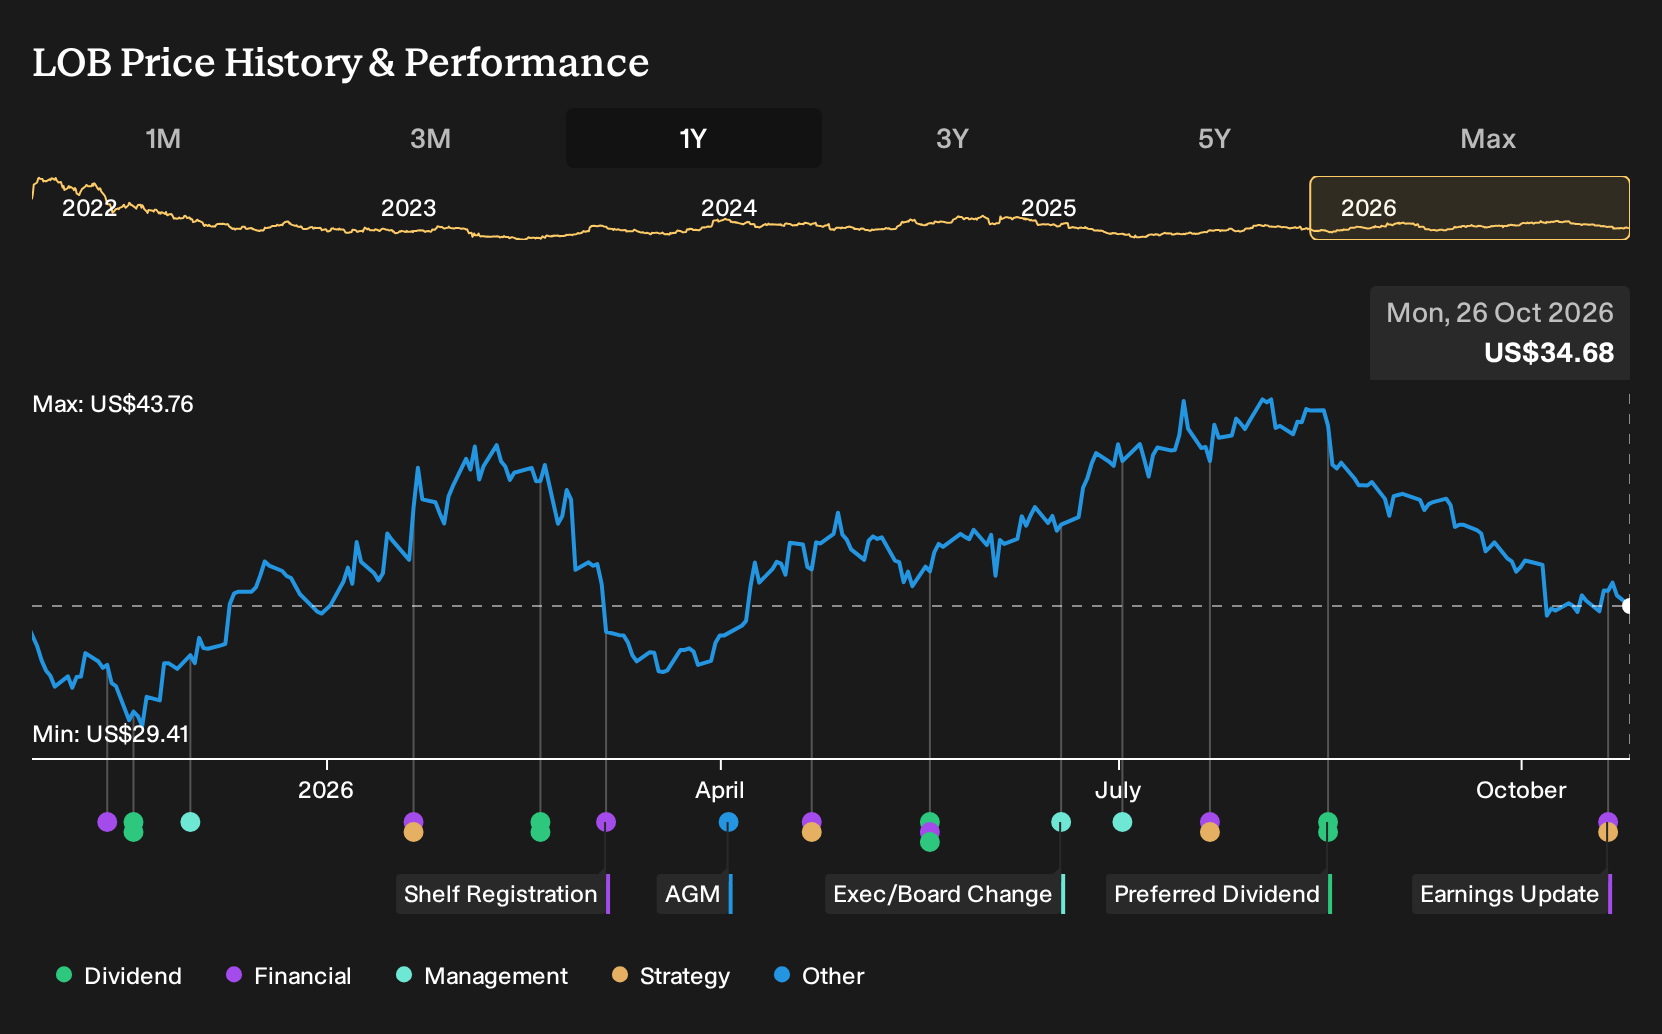
- Live Oak Bancshares reported third quarter 2026 results, with net interest income of US$133.01 million and net income of US$26.35 million, alongside basic earnings per share from continuing operations of US$0.52.
- The business posted net charge-offs of US$32.09 million for the quarter, an increase from US$16.82 million a year earlier, which puts credit quality and risk management in sharper focus for anyone tracking its small business lending model.
- The next step is to examine how Live Oak Bancshares' investment narrative intersects with higher quarterly net charge-offs and shifting credit dynamics.
Live Oak Bancshares Investment Narrative Recap
To own Live Oak Bancshares, you need to be comfortable with a small business focused lender that leans on SBA and USDA programs while trying to scale digital origination such as Live Oak Express. The near term bullish angle is straightforward. Management is still generating higher net interest income and has shown it can grow nine month earnings year on year.
The tension is that this earnings profile now sits alongside higher net charge offs and a low allowance coverage, so credit management is the biggest swing factor. The key short term catalyst remains execution on the growing loan pipeline and digital channels without further pressure on credit costs. The latest quarter keeps that debate open rather than resolving it.
The most relevant update for this discussion is the third quarter and nine month 2026 earnings release. Net interest income reached US$133.01 million for the quarter and US$377.75 million for nine months, while net income came in at US$26.35 million and US$93.19 million respectively. Earnings per share from continuing operations over nine months also moved higher year on year.
Those figures provide a clearer lens on how Live Oak Bancshares is balancing growth investments in AI driven platforms and deposit gathering efforts against rising charge offs and a relatively high level of bad loans. Progress on earnings helps support the catalyst around scaling Live Oak Express and deepening primary banking relationships, but the credit profile keeps the risk side of the ledger highly visible.
What The Current Analyst Framework Implies For Live Oak Bancshares
Analysts frame Live Oak Bancshares as a business that needs strong revenue expansion and higher profit margins to support its current narrative. Their base case uses projected annual top line growth of 25.5% over the next three years, while assuming margins increase from 25.1% today to 26.9% by around 2029. In this scenario, earnings are projected to move from US$132.3 million today to US$280.0 million by 2029, which is an increase of roughly US$148 million in profit over the period. To align with these assumptions, the stock would need to be valued on a P/E of 8.8x those 2029 earnings compared with 12.0x today, with total revenue reaching about US$1.0b by the same year.
Live Oak Bancshares' narrative centers on reaching about US$1.0b of revenue and US$280.0 million of earnings by 2029, based on revenue growing around 25.5% a year and earnings rising by roughly US$148 million from US$132.3 million today.
Uncover why Live Oak Bancshares' fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Live Oak Bancshares' use of generative AI as a potential earnings engine, rather than on credit costs. Before this earnings release, they were modeling revenue of about US$1.1b and earnings of roughly US$316.2 million by 2029. You can treat those forecasts as just one lens, then weigh how rising net charge offs might reshape them.
Explore 2 other Live Oak Bancshares fair value estimates, including one that suggests as much as 122% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Live Oak Bancshares research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Live Oak Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Oak Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Live Oak Bancshares?
If the credit and earnings story at Live Oak Bancshares has sharpened your appetite for broader opportunities, it can help to scan for other companies that fit clear risk and return profiles. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or mispriced quality so you can build a watchlist that matches how you like to take risk.
- For investors who want income potential backed by substantial cash distributions, review companies in the 5 dividend fortresses that aim to pair higher yields with resilient payouts.
- If capital preservation and steadier profiles matter most to you, focus on the 30 resilient stocks with low risk scores to see which businesses score well on resilience and lower risk characteristics.
- When the goal is to search for quality that the market may be overlooking, scan through the 21 high quality undiscovered gems that combine solid fundamentals with relatively low attention from investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com