


Why Nordnet’s latest earnings matter for shareholders
Nordnet (OM:SAVE) just posted third quarter and nine month results that showed higher net income and earnings per share year over year, putting the spotlight on how the business is converting client activity into profit.
Recent trading tells a mixed story. Nordnet’s share price is up 20.03% year to date but has fallen 11.49% over the past 90 days, while long term investors have seen a 130.54% three year total shareholder return. This suggests that momentum has cooled even as the longer track record remains strong.
Scan how Nordnet compares with a hand-picked 195 high quality undervalued stocks that have recently turned stronger earnings into fresh share price momentum.
Nordnet is reporting higher earnings while the share price has cooled over the past quarter. That combination can be appealing. The real tension now is simple: do the current numbers already reflect that strength?
Most Popular Narrative: 14% Undervalued
Nordnet closed at SEK323.60 while the most followed narrative pegs fair value closer to SEK376.94, so the latest earnings drop straight into an already underpriced story built around recurring fees and efficiency.
The key factor is that Nordnet continues to convert strong inflows and product uptake, including private banking, pension wrappers and future ETF products, into profitable growth while keeping its efficiency ratio and cost growth near current levels.
The current valuation suggests Nordnet is priced below what this narrative views as reasonable for a business reporting record profit, an efficiency ratio of 27% and expanding higher-margin products, so the market is not fully crediting these earnings and reinvestment plans in the share price.
See why 10 investors see Nordnet as 14% undervalued.
Result: Fair Value of SEK376.94 (UNDERVALUED)
Still, higher spending on the German rollout and tougher competition in Nordic and German markets could squeeze Nordnet’s profitability and weaken this undervaluation story.
Find out about the key risks to this Nordnet narrative.
Another View: What Nordnet’s P/E Is Telling You
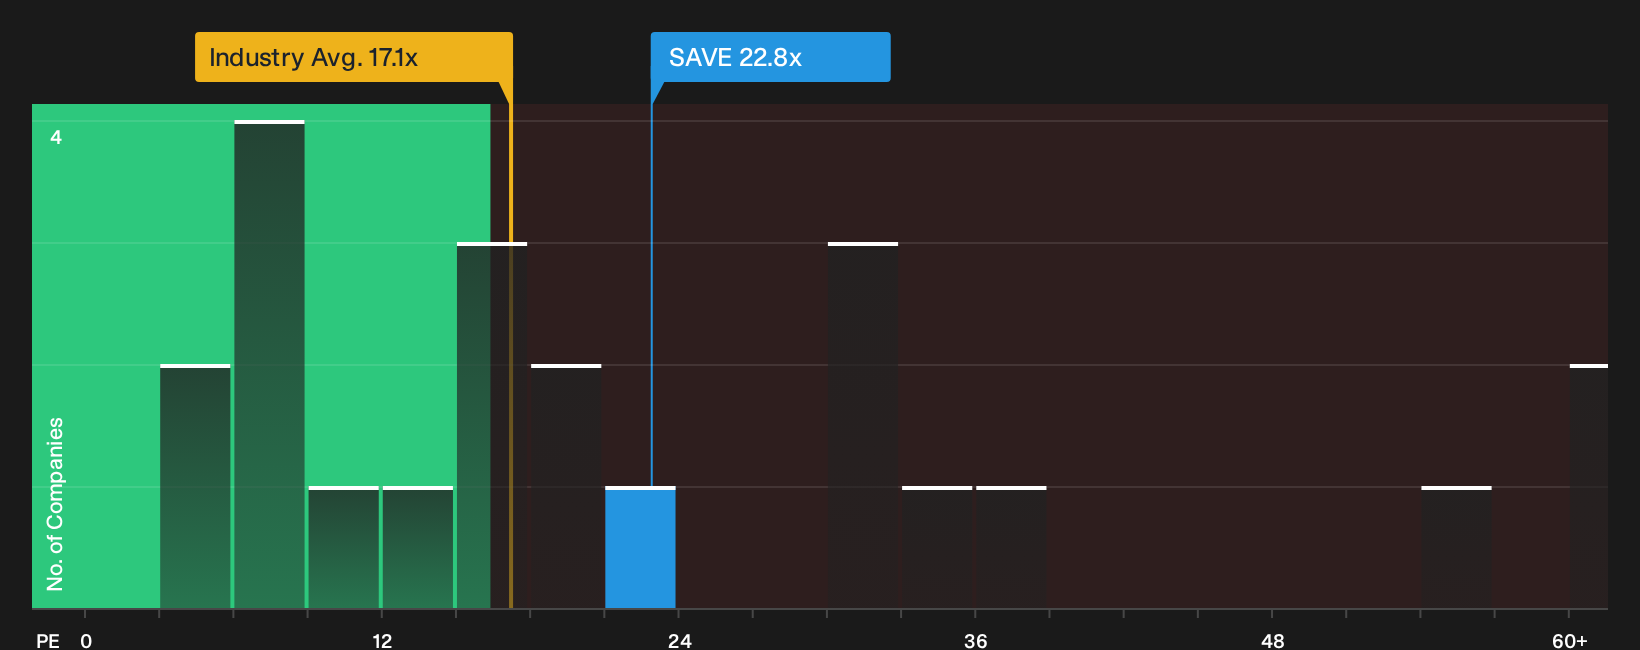
The fair value narrative around Nordnet points to an undervalued stock, yet the current pricing on earnings paints a tougher picture. The shares trade on a P/E of 22.8x, slightly above peers at 22.6x and well above the Swedish Capital Markets group at 17.1x, while the fair ratio sits at 16.8x. That gap means investors are already paying a premium multiple, so how comfortable are you with paying up when the story says there is still value on the table?
To see how that premium lines up with the underlying numbers and what the market may be willing to move back toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong opinions are already forming around Nordnet, but the most useful view will be your own, built quickly from the full risk and reward picture. To weigh both sides in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nordnet?
If Nordnet has sharpened your thinking, do not stop there. Broader context from other opportunities can help you judge whether today’s price and quality stack up.
Use Simply Wall Street’s screener to quickly spot other listed businesses that might fit your return and risk goals before the market catches on.
- Target resilient cash generators with a 224 dividend fortresses that can help anchor your portfolio when sentiment swings.
- Hunt for potential bargains through a 610 high quality undiscovered gems that flags quality companies the wider market may be overlooking.
- Protect your downside first by scanning a 223 resilient stocks with low risk scores that screens for balance sheet strength and cleaner risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com