


- Northwest Bancshares reported third quarter 2026 net interest income of US$148.95 million and net income of US$50.72 million, with basic earnings per share from continuing operations of US$0.35, all higher than the same period in 2025.
- The nine month 2026 figures, including US$438.37 million of net interest income and US$154.8 million of net income, show that Northwest Bancshares' recent business expansion and balance sheet actions are contributing to materially stronger profitability year to date.
- Next, we consider how Northwest Bancshares' sharp year on year earnings increase could influence the existing investment narrative.
Compare Northwest Bancshares' earnings shift with a curated group of resilient regionals by scanning our 30 resilient stocks with low risk scores, which pairs sturdier balance sheets with more measured risk profiles.
Northwest Bancshares Investment Narrative Recap
To own Northwest Bancshares, you need to believe the expansion into Columbus, the nationwide commercial and industrial book, and fee businesses can keep supporting earnings while credit costs and operating expenses stay contained. The latest quarter points to stronger profitability, but the near term swing factor is whether that improved run rate can hold as funding costs evolve.
The main risk still sits in the cost base and credit book. Branch buildout, higher quarterly expenses in the US$107 million to US$109 million range, and classified healthcare and Penns Woods loans could pressure margin if growth in interest income or fees cools. The fresh earnings report does not remove those issues.
The nine month 2026 results, with US$438.37 million of net interest income and US$154.8 million of net income, give you a cleaner read on how Northwest Bancshares is executing across the year, not just in a single quarter. That performance arrives as management continues to lean on balance sheet actions to support net interest margin and earnings.
For catalysts, you are really watching how these higher earnings intersect with the existing growth engines that analysts have highlighted, such as C&I expansion and new financial centers. If operating leverage from the Dublin headquarters and Columbus push holds up against the known risks in expenses, commercial real estate and credit migration, this latest profitability step becomes more meaningful to the thesis.
What The Consensus Implies For Northwest Bancshares
Analysts currently model a fairly specific path for Northwest Bancshares. Revenue is assumed to rise by 10.6% a year over the next three years, with profit margins moving from 23.4% today to 28.3% by around 2029. On that framework, earnings are expected to reach US$250.5 million by 2029, compared with US$152.9 million today, and the stock would trade on a P/E of 11.8x instead of 14.4x if those numbers play out.
That set of expectations gives you a clear checklist. Management would need to keep growing the nationwide C&I book, scaling the Columbus and Dublin operations, and integrating Penns Woods while still holding a tighter cost and credit profile. The expansion push that is lifting nine month 2026 profitability also has to support the higher margin structure implied by the consensus margin lift to 28.3%.
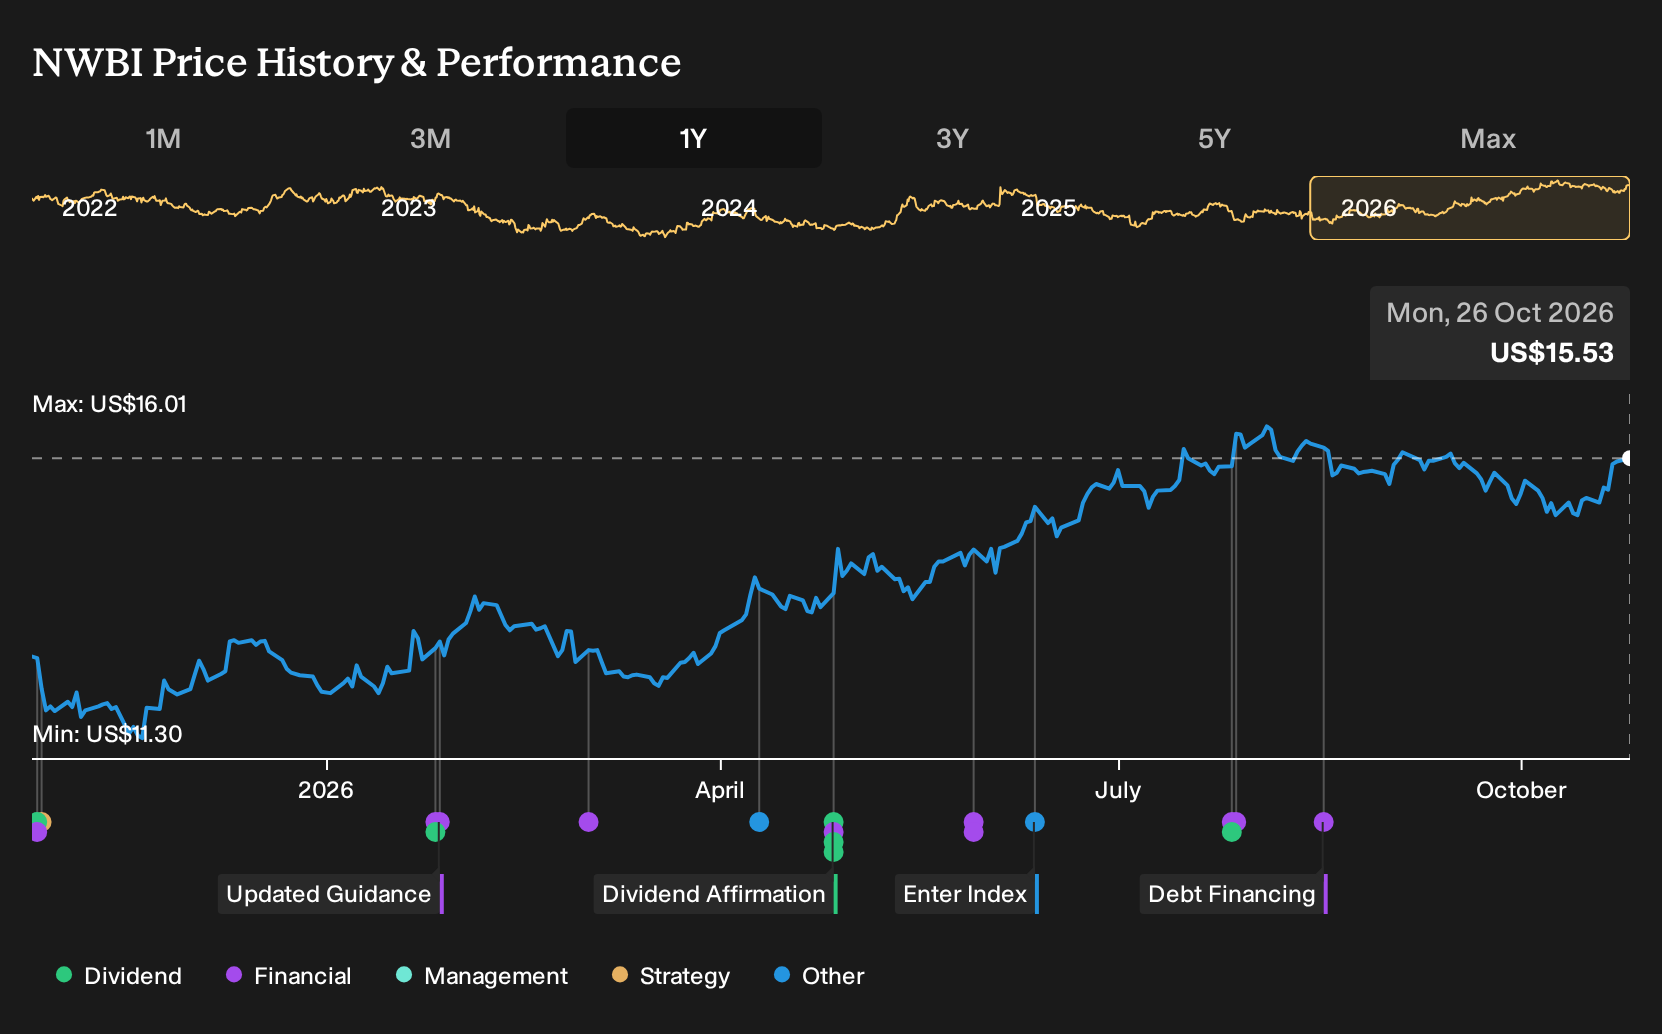
On valuation, the analyst group ties this earnings trajectory to a consensus price target of US$16.29, bracketed by a high case of US$18.00 and a low case of US$15.00, against a current share price of US$15.04 as of late October 2026. That relatively narrow spread signals that, on average, they see the stock as close to fairly priced if revenues reach US$886.0 million and earnings climb to US$250.5 million by 2029 while the P/E settles near 11.8x.
For you as an investor, the key question is how comfortable you are with those embedded assumptions. Northwest Bancshares would need to sustain double digit revenue expansion, absorb a modest increase in shares outstanding of about 0.25% per year, and still convert more of each dollar of income into profit. If that feels aggressive, you might want to stress test your own scenario with slower top line growth or flatter margins and see how that alters what you view as a reasonable valuation range.
Northwest Bancshares' current analyst blueprint points to US$886.0 million of revenue and US$250.5 million of earnings by 2029. That path assumes yearly revenue growth of 10.6% and an earnings increase of about US$97.6 million from US$152.9 million today.
Uncover why Northwest Bancshares' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value views on Northwest Bancshares so far, with one estimate near US$16.29 and another stretching above US$27, which is a wide gap for the same stock. Use that spread, along with the recent earnings jump and the expense and credit risks, to test how your own expectations might differ.
Explore another Northwest Bancshares fair value estimate, including one that suggests as much as 75% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Northwest Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Northwest Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Northwest Bancshares?
If Northwest Bancshares has sharpened your sense of what you want in a bank stock, use that clarity to widen your opportunity set. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or future growth so you can build a watchlist that actually matches your risk tolerance and return goals.
- If capital preservation is your first filter, start by reviewing a curated 30 resilient stocks with low risk scores that pair resilient financial profiles with more measured volatility.
- If you are hunting for value, scan a focused 29 high quality undervalued stocks set where stronger fundamentals and pricing gaps may line up in your favor.
- If reliable income matters most, zero in on a 5 dividend fortresses that screens for higher yields while still paying attention to balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com