


As European markets face heightened inflationary pressures and geopolitical tensions, the pan-European STOXX Europe 600 Index has experienced a decline, reflecting broader market sentiments. In this environment, identifying undervalued stocks becomes crucial for investors seeking opportunities amidst volatility; these stocks often present potential for growth when trading below their estimated value.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €27.10 | €54.02 | 49.8% |
| Peab (OM:PEAB B) | SEK95.60 | SEK180.78 | 47.1% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.91 | €23.45 | 49.2% |
| Konecranes (HLSE:KCR) | €26.96 | €50.30 | 46.4% |
| Grupa Pracuj (WSE:GPP) | PLN55.90 | PLN108.21 | 48.3% |
| Goodtech (OB:GOD) | NOK14.45 | NOK28.51 | 49.3% |
| DWS Group GmbH KGaA (XTRA:DWS) | €65.50 | €126.80 | 48.3% |
| Colt CZ Group (SEP:COLT) | CZK833.00 | CZK1562.97 | 46.7% |
| Boliden (OM:BOL) | SEK495.00 | SEK946.11 | 47.7% |
| Apator (WSE:APT) | PLN25.80 | PLN50.63 | 49% |
Let's uncover some gems from our specialized screener.
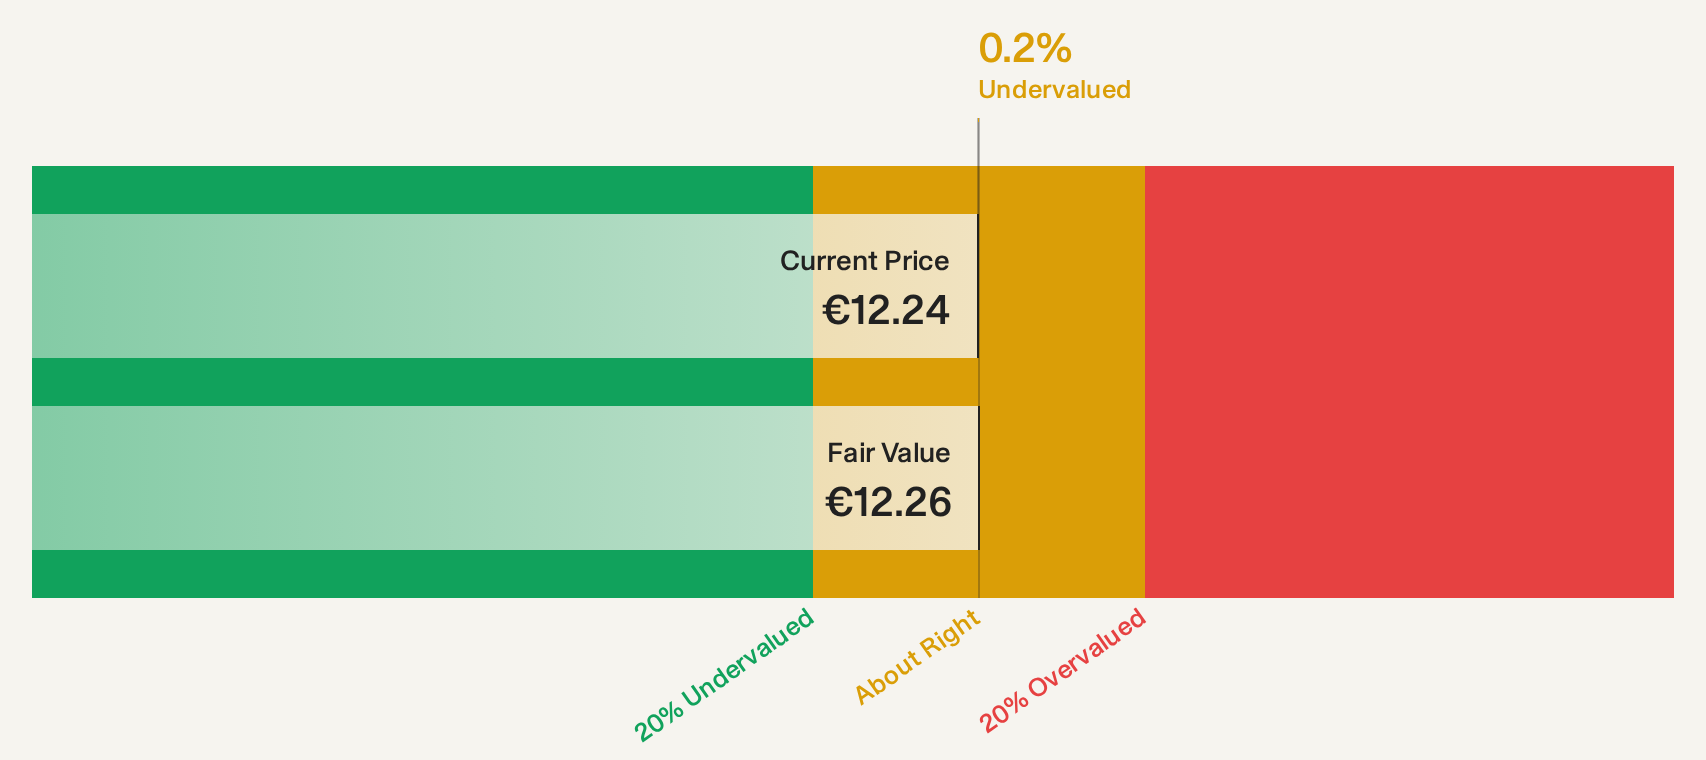
Scanfil Oyj (HLSE:SCANFL)
Overview: Scanfil Oyj operates as a contract manufacturer and system supplier for the electronics industry worldwide, with a market cap of €769.49 million.
Operations: The company's revenue is segmented as follows: €237.45 million from APAC, €73.50 million from the Americas, €375.58 million from Central Europe, and €270.23 million from Northern Europe.
Estimated Discount To Fair Value: 20.2%
Scanfil Oyj's recent earnings report highlights robust financial performance, with third-quarter sales reaching €252.2 million, up from €191.3 million a year ago, and net income rising to €11.6 million from €9.2 million. The stock is trading at approximately 20% below its estimated fair value of €14.67 per share based on discounted cash flow analysis, suggesting it may be undervalued relative to peers and industry standards despite forecasted slower earnings growth compared to the Finnish market average.
- Our growth report here indicates Scanfil Oyj may be poised for an improving outlook.
- Delve into the full analysis health report here for a deeper understanding of Scanfil Oyj.
Develia (WSE:DVL)
Overview: Develia S.A., with a market cap of PLN3.88 billion, operates in Poland through its subsidiaries, focusing on real estate development.
Operations: Revenue Segments (in millions of PLN): Residential Development: 1,200; Commercial Development: 750; Property Management: 300.
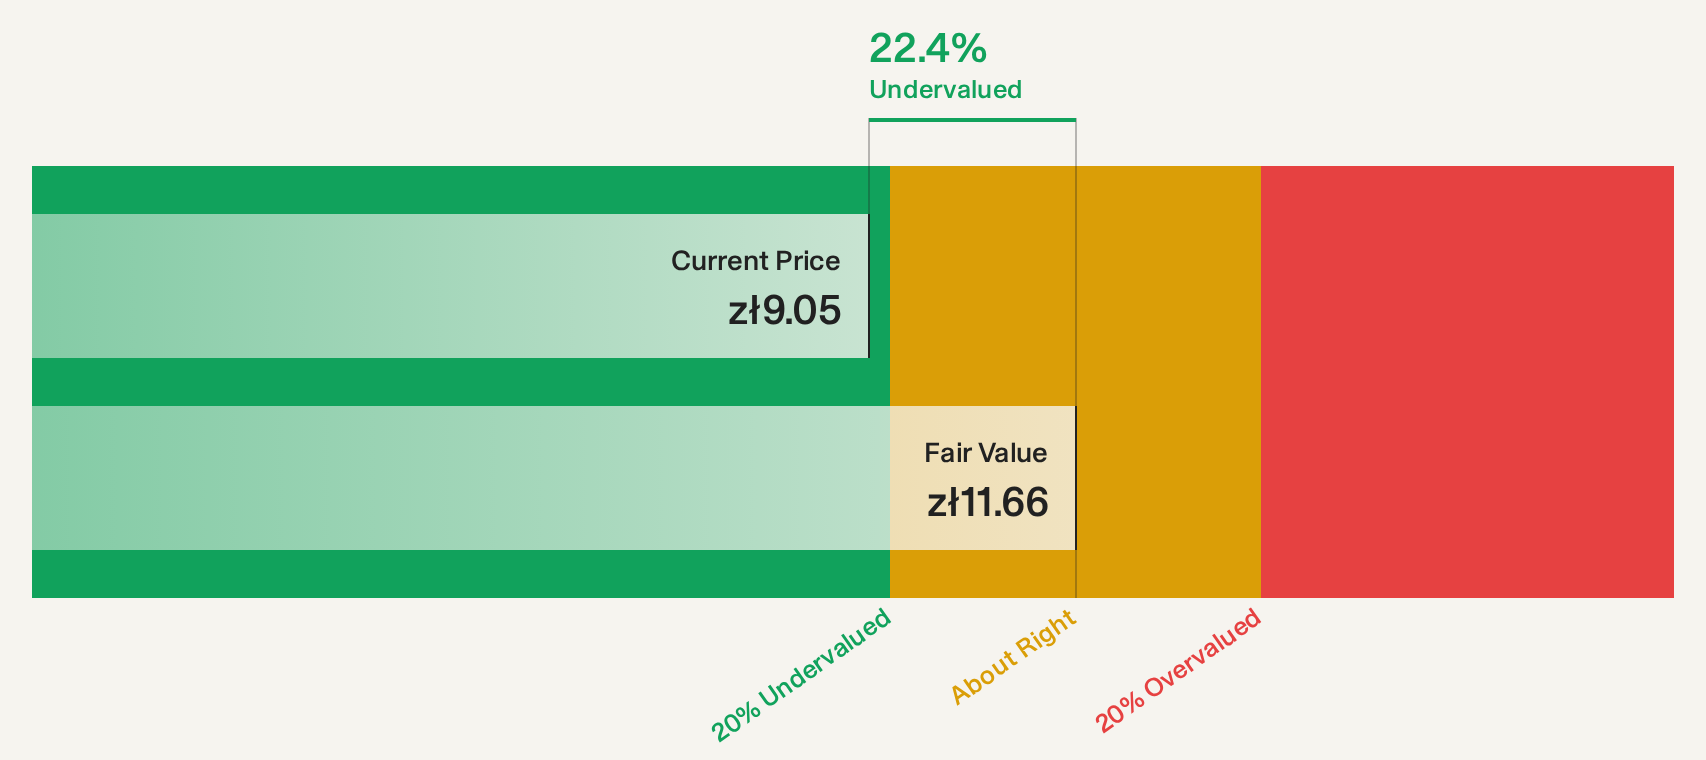
Estimated Discount To Fair Value: 17.4%
Develia's recent earnings report shows substantial revenue growth, with second-quarter revenue at PLN 996.57 million, up from PLN 494.79 million a year ago. Despite this, the stock trades at approximately 17.4% below its estimated fair value of PLN10.01 per share based on discounted cash flow analysis and is priced below analyst price targets by around 32.8%. However, future earnings are projected to decline by an average of 6% annually over the next three years.
- According our earnings growth report, there's an indication that Develia might be ready to expand.
- Navigate through the intricacies of Develia with our comprehensive financial health report here.
Friedrich Vorwerk Group (XTRA:VH2)
Overview: Friedrich Vorwerk Group SE offers solutions for energy transformation and transportation in Germany and Europe, with a market cap of €1.46 billion.
Operations: The company's revenue segments include €378.11 million from electricity, €207.61 million from natural gas, €27.67 million from clean hydrogen, and €125.16 million from adjacent opportunities.
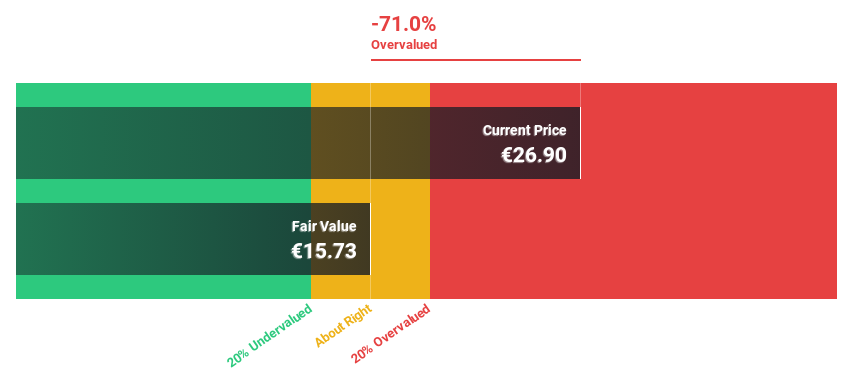
Estimated Discount To Fair Value: 24.5%
Friedrich Vorwerk Group, trading at €72.75, is valued 24.5% below its estimated fair value of €96.37 based on discounted cash flow analysis, reflecting a potential undervaluation. Recent corporate guidance raised expected 2026 revenue to €760-790 million from prior forecasts, and recent earnings showed significant growth with net income rising to €33.82 million in Q2 2026 from €19.69 million a year ago, despite slower projected earnings growth compared to the German market.
- Insights from our recent growth report point to a promising forecast for Friedrich Vorwerk Group's business outlook.
- Dive into the specifics of Friedrich Vorwerk Group here with our thorough financial health report.
Make It Happen
- Reveal the 67 hidden gems among our Undervalued European Stocks Based On Cash Flows screener with a single click here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com