


Why Idorsia’s latest daridorexant data matters for the stock
Idorsia (SWX:IDIA) has put fresh clinical data at the center of the story. At Sleep Europe 2026, the company reported Phase 2 results for daridorexant in children and adolescents with insomnia disorder, including those with neurodevelopmental conditions such as autism spectrum disorder.
The daridorexant updates land after a volatile stretch for Idorsia. The share price is CHF4.34, with a 1-day share price return of 3.63% and a 7-day share price return of 3.78%. However, the 90-day share price return is down 34.74%, so recent optimism is building on top of a sharp pullback. Over a longer horizon, momentum has shifted again, with a year-to-date share price return of 6.90% and a 3-year total shareholder return of about 1.7x, even though the 5-year total shareholder return is still down 77.04%.
Spot fresh momentum in Idorsia’s sector by scanning 123 healthcare AI stocks, which are quietly building pipelines around complex CNS and neurodevelopmental conditions.A rebound of 27% over the past year after a deep 5 year drawdown leaves Idorsia looking like either a recovery just getting started or one already largely priced in. Which side does the current valuation lean toward?
Most Popular Narrative: 19% Undervalued
Against Idorsia’s last close at CHF4.34, the most followed valuation storyline points to a fair value of CHF5.33. This leaves a clear gap that hinges on how daridorexant and the wider pipeline translate into earnings and margins.
Analysts are assuming Idorsia's revenue will grow by 24.8% annually over the next 3 years. Analysts assume that profit margins will increase from -158.3% today to 6.2% in 3 years time.
See why 8 investors see Idorsia as 19% undervalued.
Result: Fair Value of CHF5.33 (UNDERVALUED)
Still, the narrative could shift quickly if QUVIVIQ underperforms commercial expectations or if pricing pressure limits how Idorsia turns pipeline assets into profits.
Find out about the key risks to this Idorsia narrative.
Another View: Idorsia looks expensive on sales
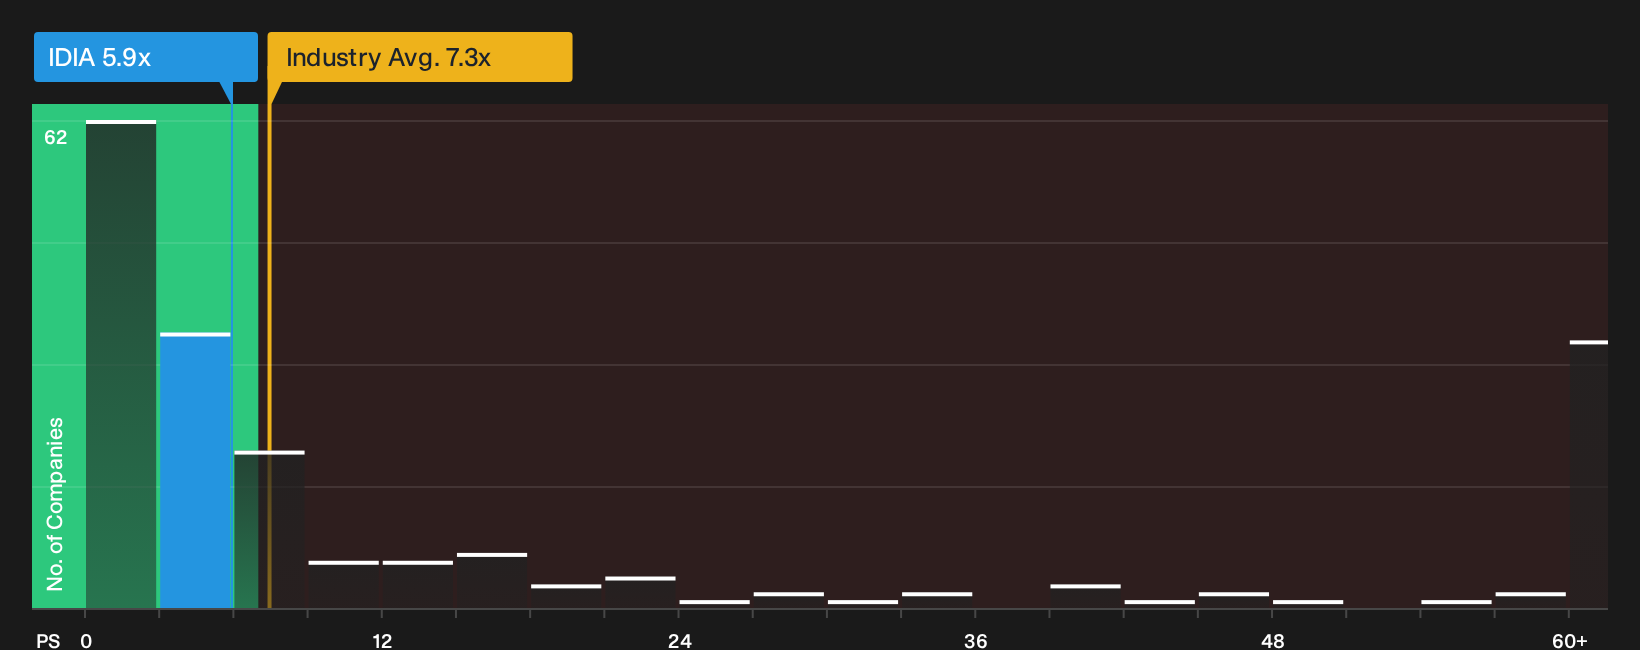
The first story presents Idorsia as 61.1% below an estimate of fair value using future cash flows. Through a simple P/S lens, the picture changes. The current 5.9x P/S is higher than a 4.5x fair ratio, so the share price already reflects richer sales expectations than that model suggests.
Even compared with peers, the signal is mixed. A 5.9x P/S sits below the 7.4x European Biotechs average and under the 8.5x peer group figure, which points to some relative discount, yet it remains above the fair ratio that the market could move toward. The question for investors is which anchor matters more for Idorsia: cash flows or sales multiples.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Idorsia story so far. If you want to move quickly and shape your own view, weigh both sides through 3 key rewards and 4 important warning signs.
Looking for more Idorsia sized investment ideas?
Idorsia gives you one angle, but your portfolio deserves a broader bench of potential opportunities filtered by quality, price, resilience and income strength.
- Target potential mispricing by scanning the 195 high quality undervalued stocks that combine solid fundamentals with a market price that has not fully reflected them yet.
- Strengthen your downside protection by checking the 223 resilient stocks with low risk scores that pair sturdier balance sheets with more measured risk scores.
- Get ahead of the crowd by reviewing the 610 high quality undiscovered gems that show strong underlying metrics before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com