


SoftwareOne Holding (SWX:SWON) just picked up its seventh consecutive Leader spot in Gartner's 2026 Magic Quadrant for SAM Managed Services, spotlighting its role in IT asset management, FinOps support, and cost control.
The recognition comes as SoftwareOne Holding’s share price has quietly built momentum, with a 1 month share price return of 9.85% and a year to date share price return of 6.37%. The 1 year total shareholder return of 22.04% contrasts with a 3 year total shareholder return that declined 40.08% and a 5 year total shareholder return that fell 48.17%.
Capitalize on SoftwareOne Holding's momentum by scanning a curated set of 195 high quality undervalued stocks with resilient cash flows and balance sheets that can shoulder long contracts and complex IT spending cycles.SoftwareOne Holding now trades at a sizeable discount to both analyst targets and one intrinsic value estimate, even after the recent bounce. Is that a cautious market calling past scars, or mispricing current execution?
Most Popular Narrative: 15% Undervalued
Against a last close of CHF9.60, the most followed narrative pegs SoftwareOne Holding’s fair value at CHF11.27, implying a sizeable valuation gap that hinges on execution of its cloud and services push.
The integration with Crayon is expected to unlock substantial cost and revenue synergies, including CHF 80 to 100 million in run-rate cost savings and enhanced cross
and upsell opportunities through a combined marketplace and expanded global reach; these synergies support margin expansion and higher earnings visibility over the medium to long term.
See why 6 investors see SoftwareOne Holding as 15% undervalued.
Result: Fair Value of CHF11.27 (UNDERVALUED)
Still, the SoftwareOne Holding story can break if reliance on a few major software vendors bites harder, or if the Crayon integration stumbles and erodes margins.
Find out about the key risks to this SoftwareOne Holding narrative.
Another View On SoftwareOne Holding’s Valuation
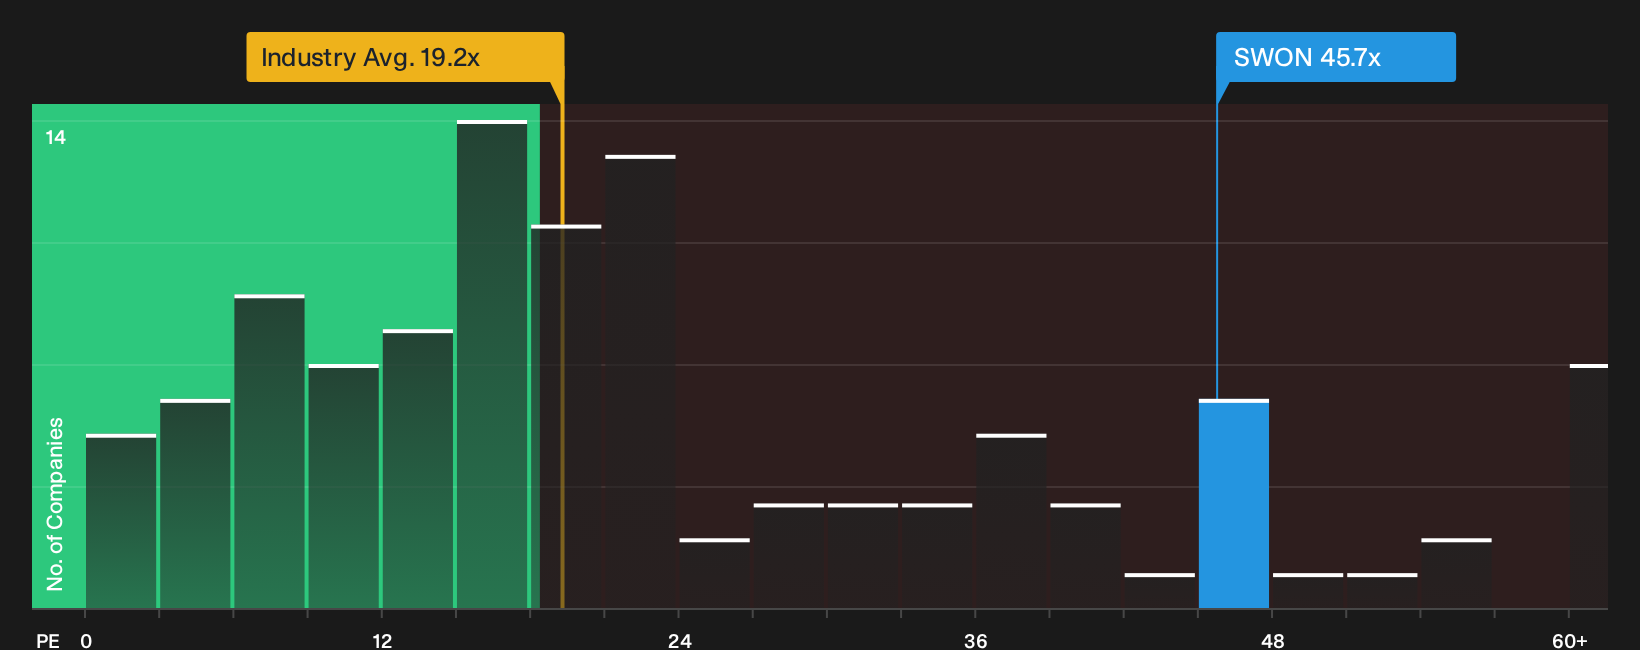
There is a different signal once you swap the fair value model for the headline P/E. SoftwareOne Holding trades on a P/E of 45.7x compared with 19.5x for the European Electronic group and a fair ratio of 49.5x, which points to richer pricing today and raises the question of how much execution risk you are willing to underwrite at this level.
For a closer look at how that earnings multiple stacks up against what the numbers imply over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the numbers or a clear opportunity in disguise? Move quickly, review the full picture for yourself, and weigh both sides in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SoftwareOne Holding?
If you stop at just one ticker, you risk missing other opportunities that match your approach, your risk tolerance, and the kind of outcomes you are aiming for.
- Target potential mispricings by scanning a curated pool of quality candidates through the 195 high quality undervalued stocks.
- Anchor your watchlist to financial resilience by filtering companies with a list of solid balance sheet and fundamentals (207 results).
- Hunt for underfollowed opportunities by surfacing 610 high quality undiscovered gems before they show up on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com