


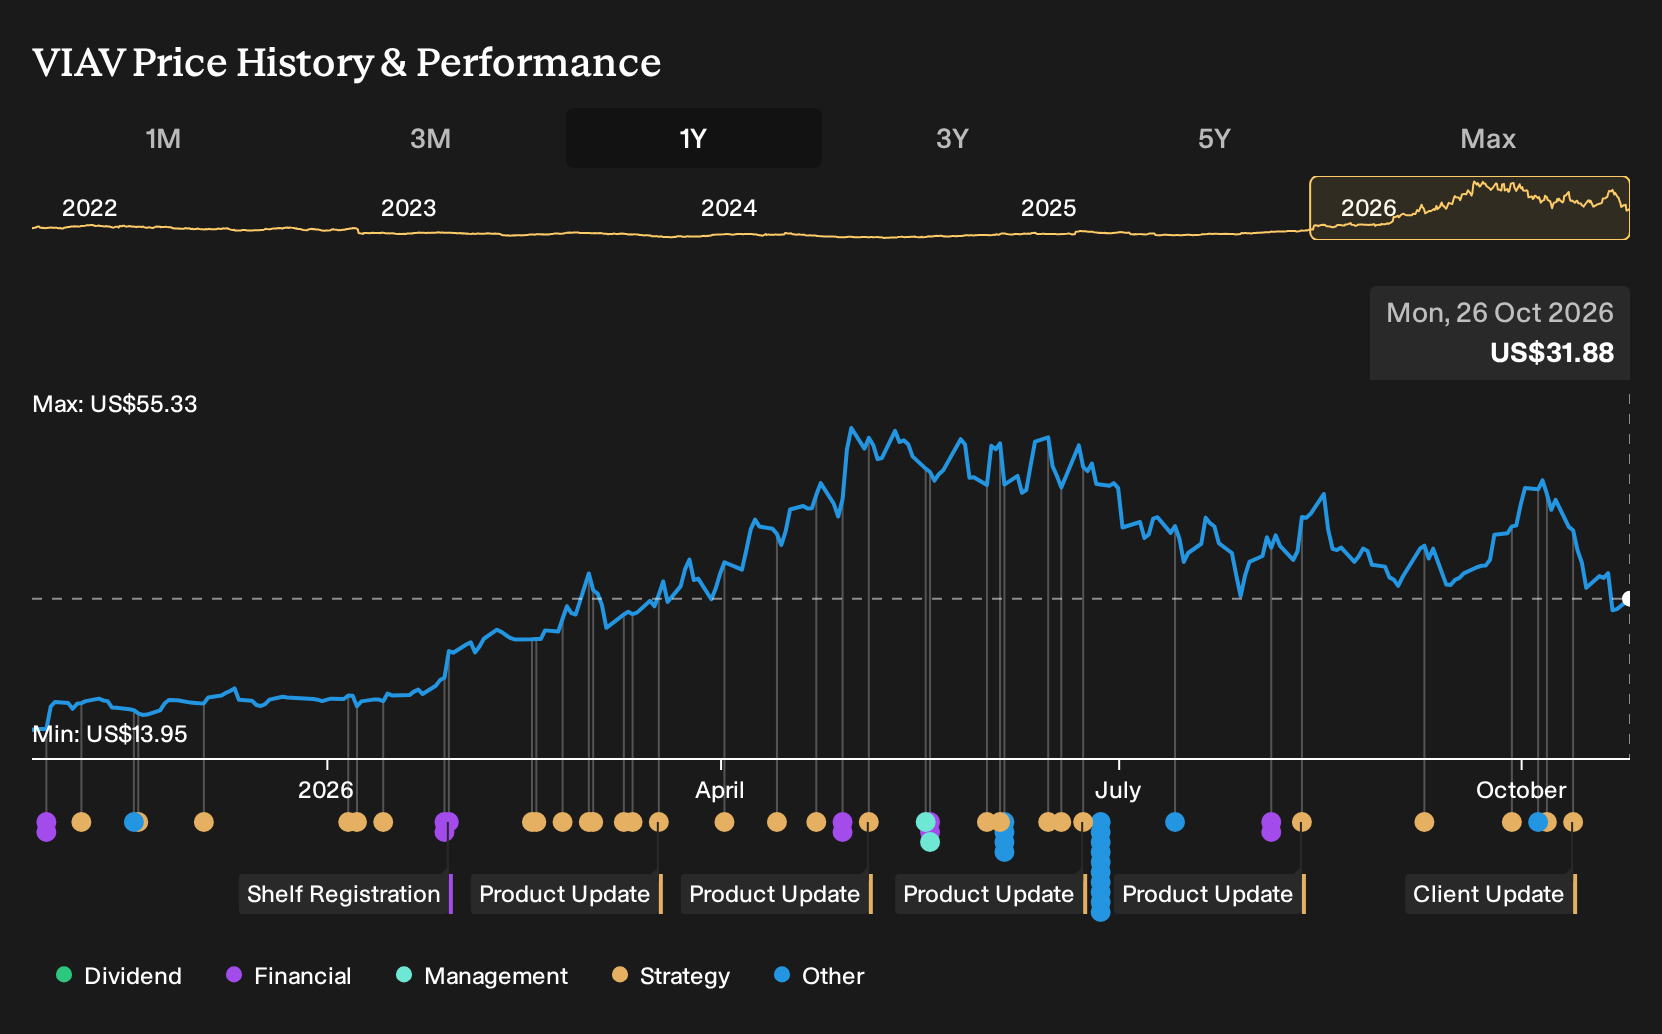
- In October 2026, the U.S. Army's Threat Systems Management Office selected Viavi Solutions' T/Rx software defined transceiver to help create realistic electromagnetic spectrum conditions at test ranges that are now open to private drone, counter drone, long range fires and interceptor developers.
- The T/Rx deployment at sites such as Camp Grayling highlights Viavi Solutions' foothold in electromagnetic spectrum testing for both defense and commercial technology developers that need contested electronic warfare conditions for product hardening.
- This article examines how Viavi Solutions' role in electromagnetic spectrum testing shapes the broader investment narrative around defense diversification.
Scan other defense and EMS testing opportunities by shortlisting companies exposed to similar demand trends through our curated 42 power grid technology and infrastructure stocks
Viavi Solutions Investment Narrative Recap
To stay invested in Viavi Solutions, you need to believe the test and measurement portfolio can absorb telecom cyclicality through steadier demand from data centers, fiber build outs, and now defense and aerospace. The T/Rx win with the U.S. Army fits that thesis as another proof point that Viavi’s technology is relevant in high value, mission critical applications beyond traditional carriers.
In the near term, the key swing factor is whether data center and fiber spending keep offsetting weak wireless infrastructure test activity and lumpy service provider budgets. The biggest risk still sits in integration and execution on acquisitions plus higher debt, rather than this single T/Rx award, which looks helpful but not business defining on its own.
The recent selection of Viavi’s T/Rx system for the Army’s Test Range Private Industry Initiative is the clearest link to the defense diversification catalyst already in the story. It shows Viavi equipment being embedded in test infrastructure that commercial drone and counter drone developers are expected to use, which can deepen relationships in aerospace and defense over time.
For you as an investor, that ties back to the goal of reducing reliance on cyclical service provider and cable spending while adding customers that view rigorous EMS testing as non discretionary. The operational question now is execution: whether Viavi can scale similar deployments across multiple ranges and programs while managing supply chain exposure, integration tasks, and the higher financing load on the balance sheet.
Viavi Solutions' current analyst narrative points to US$2.5b in revenue and US$503.0m in earnings by 2029, built on assumed 18.0% yearly revenue growth and a swing in profitability from an earnings loss of US$30.4m today to that US$503.0m figure. This implies an earnings increase of about US$533.4m from the current base.
Uncover why Viavi Solutions' fair value indicates a 93% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
You also need to weigh a different angle. The most bearish analysts worry that Viavi Solutions is leaning too hard on AI driven data centers, even while they still penciled in about US$2.5b of 2029 revenue and roughly US$524.5m in earnings before this Army T/Rx news. That gap in expectations shows how widely views can spread, so it is worth comparing several narratives yourself and deciding which one feels more realistic if contracts like this keep emerging.
Explore 3 other Viavi Solutions fair value estimates, including one that suggests as much as 11% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Viavi Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Viavi Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viavi Solutions' overall financial health at a glance.
Looking For More Ideas Beyond Viavi Solutions?
If the Viavi Solutions story has you thinking about how to balance risk, income, and quality across your portfolio, it can help to line it up against other stocks facing different demand drivers. The Simply Wall St Screener lets you filter for the kind of businesses that match your priorities, whether you care more about resilience, income today, or upside potential over time.
- For investors who want potential upside combined with balance sheet strength, shortlist a focused pool of candidates using our 21 high quality undiscovered gems.
- If capital preservation and steadier profiles sit higher on your list, narrow the field to companies with lower risk characteristics via the 30 resilient stocks with low risk scores.
- Income oriented investors who care about cash returns as much as price moves can zero in on reliable payers through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com