


- Carpenter Technology reported first quarter 2026 results, with sales of US$798.2 million, net income of US$162.5 million, and diluted EPS from continuing operations of US$3.25. The company also issued and maintained operating income guidance for the second quarter and full fiscal year 2027.
- The company paired these updates with a new US$1 billion share repurchase authorization and commentary on strong aerospace and defense order activity. Together, these factors highlight how capital allocation and end market demand are shaping Carpenter Technology’s earnings profile.
- We will now look at how Carpenter Technology's investment narrative is influenced by reaffirmed 2027 guidance alongside the new share repurchase.
Compare Carpenter Technology's latest guidance and buyback with a curated group of industrials that have strong balance sheets and cash generation, using the 29 high quality undervalued stocks as a starting shortlist.
Carpenter Technology Investment Narrative Recap
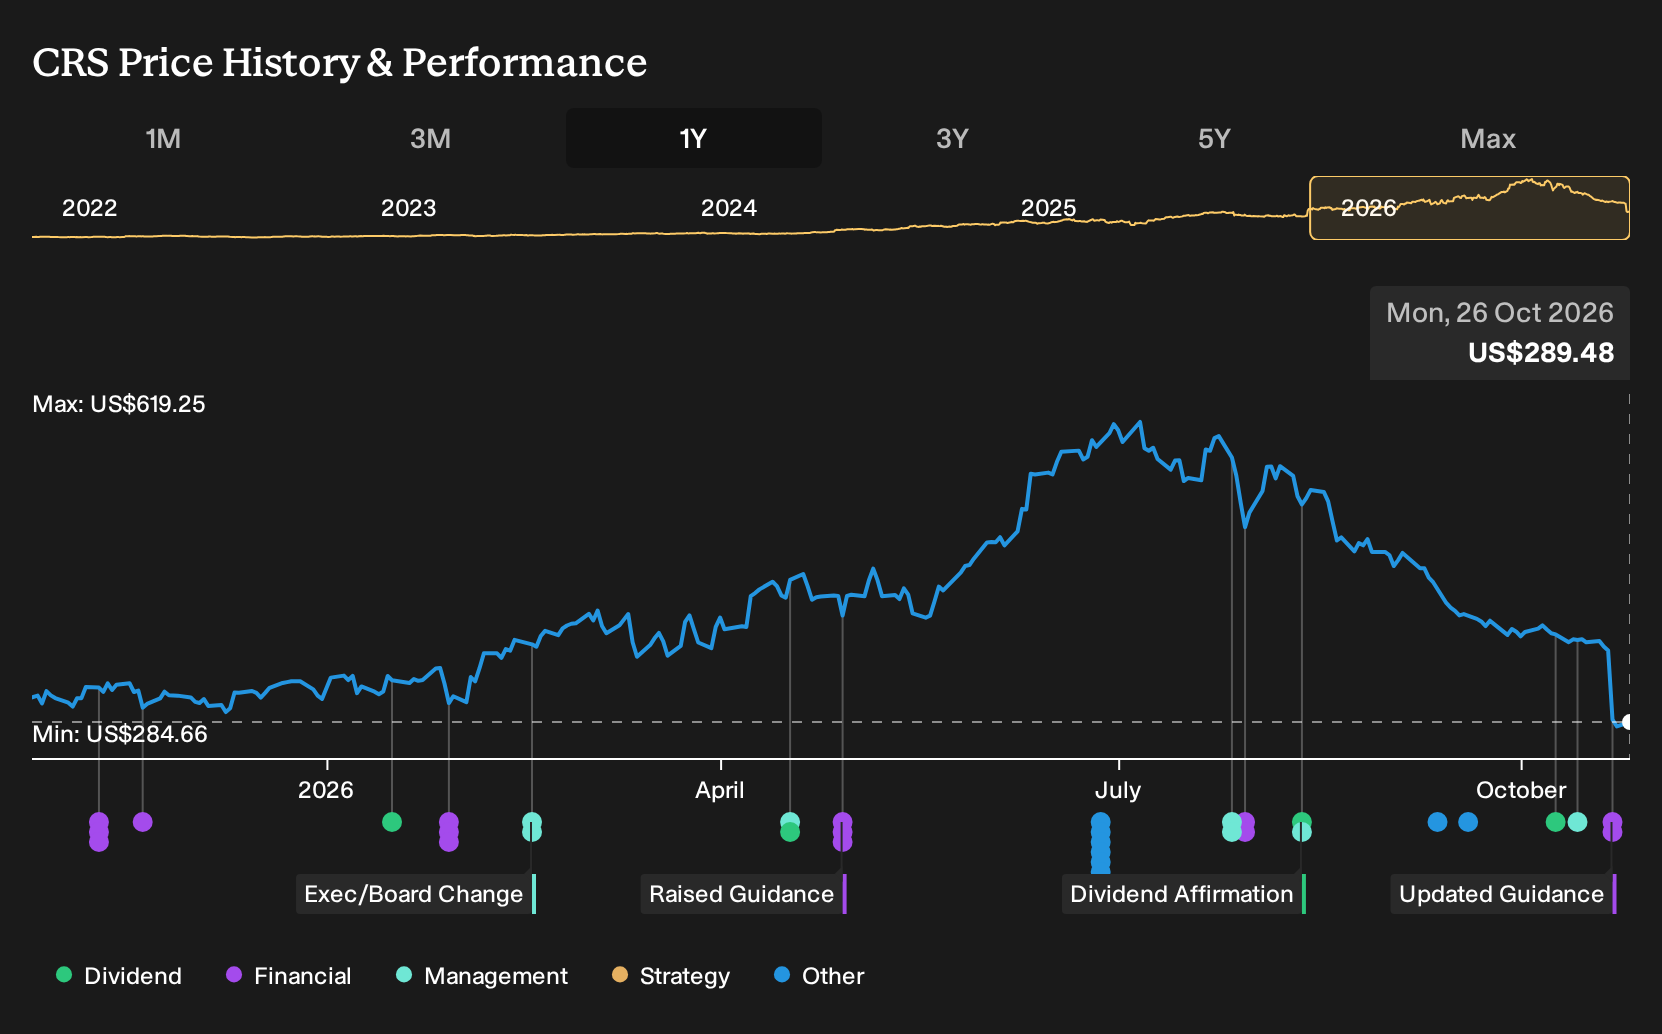
For an investor to stay with Carpenter Technology, the core belief is that aerospace, defense and related end markets continue to support the company’s premium alloy model and high operating margins. The reaffirmed fiscal 2027 operating income range of US$850 million to US$880 million keeps that thesis intact in the near term, even after the recent share price drop.
The most important short term swing factor is execution against that operating income outlook while keeping project spend and working capital in check. The main risk remains concentration in aerospace and defense demand. Any pause in aircraft builds or defense orders would challenge volumes and make the brownfield expansion harder to earn through.
The fresh US$1b share repurchase authorization ties directly into the current setup for Carpenter Technology. After a steep pullback in the stock despite strong first quarter profitability, this program gives management more flexibility in how it uses free cash flow while it pursues the same operating income targets.
For you, the key question is not the headline size of the buyback but whether the firm can keep generating enough cash from aerospace, defense and power generation orders to fund both capital projects and repurchases. If earnings or demand were to soften against guidance, the tension between capacity investment and returning cash to shareholders would become a key watchpoint.
Carpenter Technology Earnings Framework Versus Analyst Consensus
Carpenter Technology's narrative projects US$4.3b revenue and US$958.8 million earnings by 2029. Analysts are assuming 11.0% yearly revenue growth and a roughly US$429.2 million earnings increase from US$529.6 million today.
Uncover how Carpenter Technology's fair value indicates a 85% potential upside to its current price. This potential upside could narrow quickly if Carpenter Technology keeps delivering against its earnings roadmap.
Exploring Other Perspectives
One bullish twist in the alternate Carpenter Technology narrative is how optimistic analysts were on aerospace and defense demand before this news. Earlier forecasts pointed to revenue of about US$4.5b and earnings of US$995.0 million by 2029, with a higher 38.4x P/E ratio. Those expectations could shift meaningfully as guidance and the new buyback are incorporated into updated views.
Explore 2 other Carpenter Technology fair value estimates, including one that suggests as much as 85% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Carpenter Technology research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carpenter Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carpenter Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carpenter Technology?
Once you have a clear view on Carpenter Technology, it can help to widen the lens and see how other businesses with different balance sheet profiles, income streams, or risk levels compare side by side in the Simply Wall St Screener.
- If you want a shortlist of companies that combine strong cash generation with supportive balance sheets, start with this list of solid balance sheet and fundamentals (24 results) to see how they stack up on core fundamentals.
- For readers who care most about capital strength and valuation working together, use the curated 29 high quality undervalued stocks to find stocks that pair healthier finances with pricing that screens as attractive.
- If your priority is limiting downside risk rather than chasing the highest return, focus on the 30 resilient stocks with low risk scores to compare how those businesses score on stability and resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com