


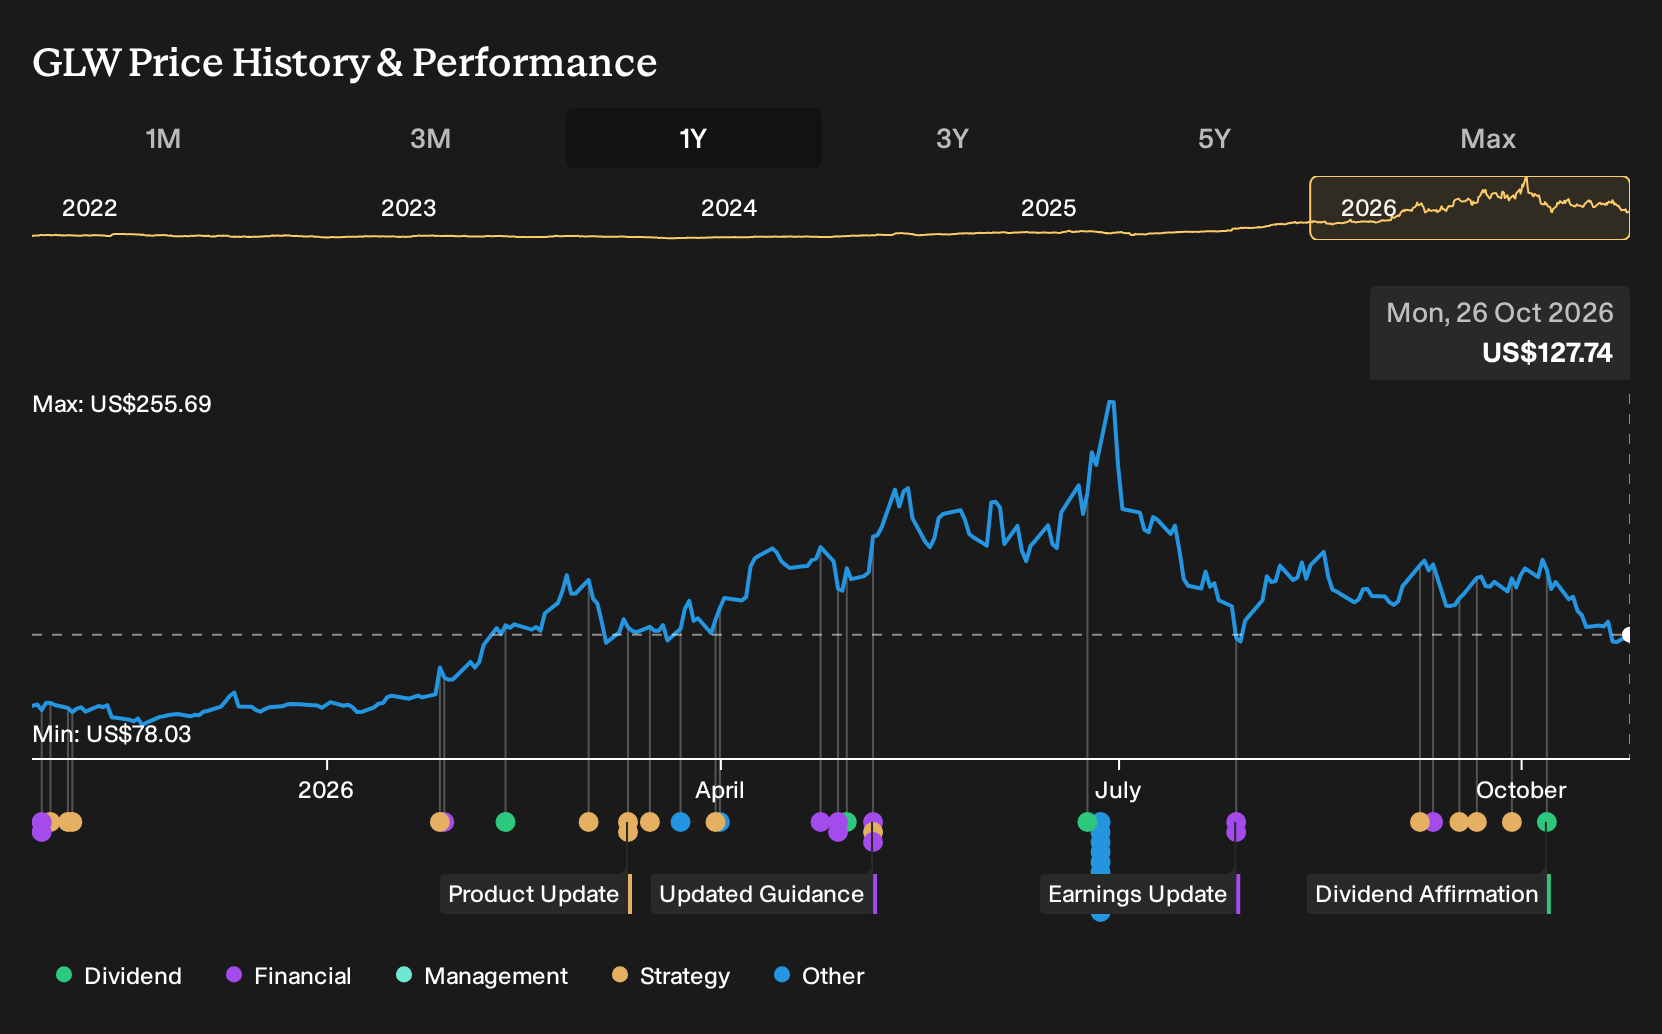
- Corning is set to report earnings on Tuesday before the bell, with analysts projecting 18.1% year on year revenue growth for the quarter, following prior guidance that did not match Wall Street expectations.
- The mix of an expected acceleration in revenue and Corning's record of topping forecasts, despite last quarter's softer outlook, puts execution under the microscope for its core glass, optical and solar businesses.
- We will now look at how Corning's anticipated revenue acceleration could reshape the investment narrative and the trade off between risk and reward.
Scan beyond Corning's print and size up other glass, optical, and hardware plays that could be setting up for similar earnings moves with our curated 55 AI infrastructure stocks.
Corning Investment Narrative Recap
For a shareholder in Corning, the central belief is that the Springboard plan and long term optical and solar demand can keep supporting higher sales and earnings quality. The expected 18.1% revenue growth this quarter puts that execution in focus. The key short term catalyst is whether the quarterly results show that optical communications orders and data center demand are converting cleanly into reported revenue.
The biggest near term risk sits in execution and funding. Corning still carries a high level of debt and has used a US$2b at the market equity program to support projects. Any sign that margins rely heavily on non GAAP adjustments or that solar issues resurface could make the growth plan look less reliable.
Recent commentary around the upgraded Springboard plan is the clearest anchor for this earnings setup. Targets for a US$20b sales run rate by Q3 2026, US$30b by 2028 and US$40b by 2030, with operating margins at or above 20%, provide a framework for how investors may judge Tuesday's revenue line and guidance. The print will be read against those longer dated ambitions.
For you as a holder or prospective buyer, the link to near term catalysts is straightforward. Stronger optical demand from AI data centers, long duration supply agreements with customers such as NVIDIA, Meta, Amazon, Verizon and AT&T, and the push to about US$3b in solar revenue by around the end of 2027 all depend on Corning turning backlog into stable cash earnings. Any stumble on execution, or further equity issuance beyond the existing US$2b program, would feed directly into that risk reward trade off.
What The Corning Earnings Setup Implies About The Longer Term
Corning's narrative projects US$29.4b revenue and US$5.7b earnings by 2029. This assumes analysts' forecast revenue growth rate of 20.1% per year and an earnings increase of about US$3.8b from US$1.9b today.
Uncover why Corning's fair value indicates a 49% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might read Corning’s upbeat AI and solar story and then see the most bearish analysts flagging the US$2b equity program as the real swing factor. They model around US$29.6b revenue and US$4.9b earnings by 2029, with a lower 29.5x P/E, which reflects a much tougher, more cautious narrative. Those views were formed before this week’s earnings, so opinions may change as fresh numbers arrive. It is worth considering which version you find more realistic.
Explore 7 other Corning fair value estimates, including one that suggests it could be worth just $129.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corning research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Ideas Beyond Corning?
Once you have a view on Corning, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener and see how different balance sheets, dividends, and growth profiles stack up.
- If capital preservation is your priority, you might prefer companies that score well on resilience and risk, which you can filter quickly using our 30 resilient stocks with low risk scores.
- Income focused investors who care about consistent cash returns can scan for higher yielding payers by starting with the 5 dividend fortresses.
- For a broader watchlist of quality businesses with room to grow, you can cast a wider net across the 21 high quality undiscovered gems and see which profiles best fit your own checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com