


Humana (HUM) just reshaped its primary care footprint by forming a new joint venture with BlackRock’s HPS Investment Partners to oversee nearly 150 CenterWell Senior Primary Care clinics and acquire WCAS’s US$2.8b equity stake.
Humana’s latest joint venture update comes after a strong run. The share price has gained 57.75% year to date and 4.85% over the past month, even though the 3-year total shareholder return is down 16.62% and the 5-year total shareholder return is down 4.72%. This suggests that momentum has picked up recently, while longer-term holders have experienced a much bumpier ride.
Capture how Humana’s primary care pivot compares by lining up other healthcare operators with strong balance sheets and cash generation using our curated list of solid balance sheet and fundamentals (24 results).Bulls see Humana using this BlackRock partnership to recycle capital into higher value Medicare and services earnings. Bears see headline momentum masking risk. Which story do the current valuation signals support next?
Most Popular Narrative: 10% Undervalued
Humana closed at $417.22, while the most followed narrative pegs fair value at $465.13 using a 7.24% discount rate and long term Medicare Advantage margin recovery as the anchor. That gap keeps the focus firmly on whether the primary care joint venture and Stars rebound can actually feed through to sustainable earnings power.
Humana’s multiyear Medicare Advantage margin restoration plan that targets at least a 3% pretax margin by 2028, including 2027 bid discipline and exits from about 600,000 lower return plans with an aim to recapture a significant portion into higher value products, may influence earnings and net margins.
See why 60 investors see Humana as 10% undervalued.
Result: Fair Value of $465.13 (UNDERVALUED)
Still, Medicare Advantage rule changes or tighter coding scrutiny could squeeze Humana’s margins faster than expected and challenge today’s view that the shares may be underpriced.
Find out about the key risks to this Humana narrative.
Another View: Humana’s P/E Sends A Different Signal
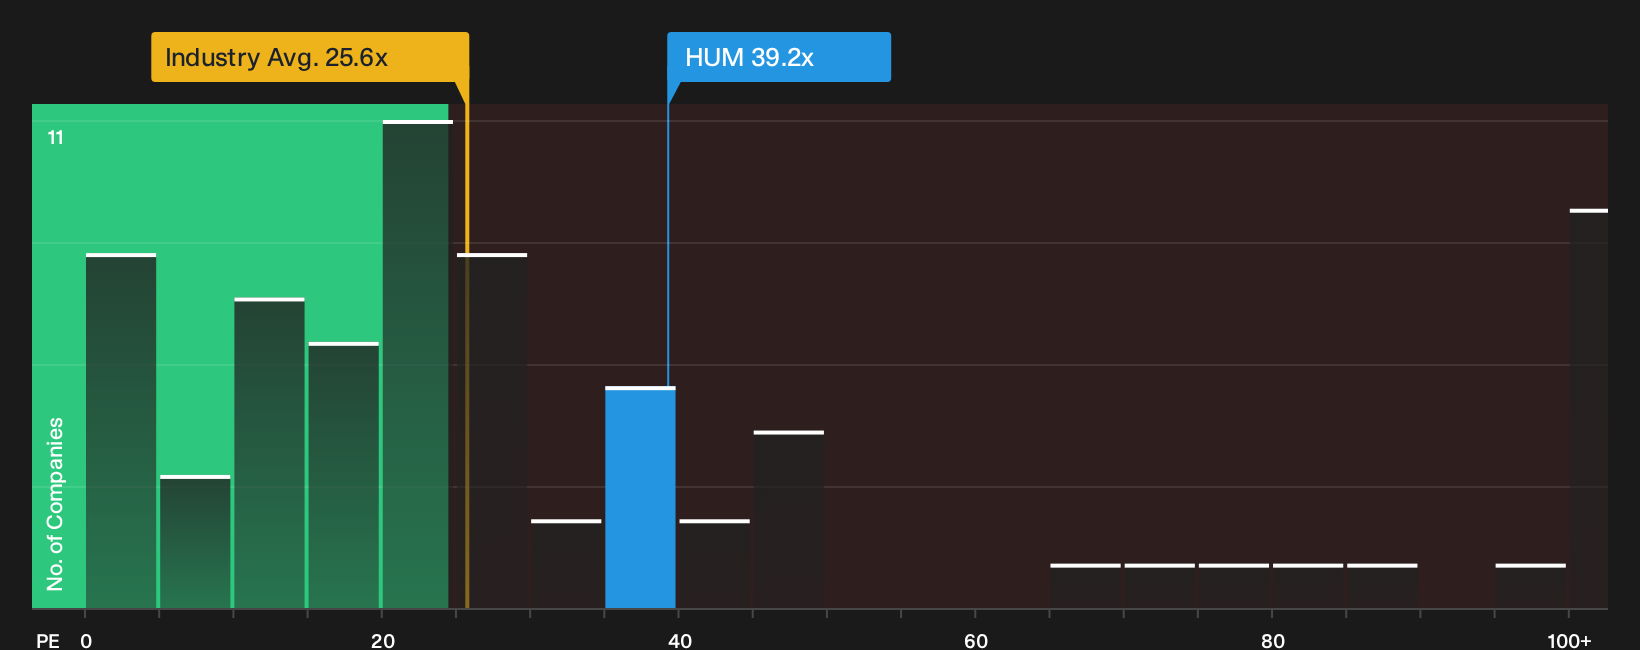
Humana might screen as 10% undervalued on fair value estimates, yet the P/E ratio tells a tighter story. The shares trade around 39.2x earnings versus 25.6x for the US Healthcare industry and 26.3x for peers, while the fair ratio is 47.4x. That gap points to a premium that could compress or expand depending on how investors update their expectations.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Humana’s valuation and risk profile make this a moment to move quickly, review the data independently, and see both sides clearly with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Humana?
If Humana has you thinking harder about where to put fresh capital, now is the moment to widen the lens and hunt for your next edge.
- Target resilient cash generators by scanning companies with strong balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (24 results).
- Spot potential mispricings before the crowd by searching for quality opportunities that appear underappreciated through our focused 29 high quality undervalued stocks.
- Prioritize sleep-at-night stability by filtering for companies with lower risk profiles using our carefully constructed 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com