


- T. Rowe Price Group has expanded its U.S. Intermediaries Wealth Management arm, adding over 50 client-facing roles across broker-dealer, RIA, alternatives, ETF, and model portfolio specialist teams to deepen advisor engagement and support.
- The build out of field sales and product specialist capacity points to a heavier push into wealth channels, where advisor relationships can influence flows into retirement, ETF, model portfolio, and alternatives offerings.
- We will explore how T. Rowe Price Group's advisor focused hiring spree reshapes its investment narrative, which is built around product diversification.
Scan how T. Rowe Price Group's wealth channel push compares with other asset managers by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
T. Rowe Price Group Investment Narrative Recap
To own T. Rowe Price Group, you need to believe its product breadth in retirement, ETFs, SMAs, and alternatives can offset pressure from active fund outflows, fee compression, and rising expenses. The wealth channel expansion fits that story by leaning harder into intermediaries who already control a large share of investor assets.
The near term swing factor remains whether net outflows and a 38.1 basis point effective fee rate stabilize without eroding margins further as 2026 costs trend 4% to 7% above 2025. This hiring push raises the cost base, so if flows do not improve meaningfully, the financial impact of this announcement may be limited.
The most relevant recent development tied to this news is T. Rowe Price Group’s focus on ETFs, SMAs, and alternatives, including around US$30b in active ETFs, US$20b in SMAs, and roughly US$112b in alternatives via OHA. Expanding advisor coverage directly supports distribution of those lower fee and higher complexity products.
For you, the key question is execution. Can the larger salesforce and specialist teams steer more retirement, ETF, model portfolio, and private credit flows toward T. Rowe offerings fast enough to offset fee pressure and elevated operating costs? If that works, it would support the existing narrative of modest earnings growth and a P/E near 10x.
T. Rowe Price Group Analyst Assumptions In Plain English
Analysts looking at T. Rowe Price Group are effectively baking in a flat top line, with revenue expected to stay roughly unchanged over the next three years while profit margins edge higher from 28.5% to 29.8%. That mix points to earnings doing a bit more of the heavy lifting than sales, helped by cost discipline and buybacks rather than aggressive growth in fee revenue. For you, the story is less about a surge in demand and more about how efficiently the existing asset base can be monetized.
On current numbers, T. Rowe Price Group is reported to be earning about US$2.2b, with analysts pointing to consensus earnings of US$2.3b by 2029. That is an increase of roughly US$0.1b in profit over the period, which lines up with the modest margin improvement and share count declining by an estimated 2.25% per year. In practical terms, the narrative depends on a slightly leaner share base and a touch more profitability on each dollar of revenue rather than a sharp change in the overall size of the business.
Framed this way, the expanded wealth management salesforce and product specialist hiring push slots into an already conservative forecast set. If the additional advisor coverage merely keeps revenue flat while margins drift up into the high 20s, then the analysts’ view holds. If that sales build out manages to do more than that, any upside would come on top of a baseline that already assumes low revenue growth and a controlled cost structure.
T. Rowe Price Group's narrative projects US$7.6b revenue and US$2.3b earnings by 2029. This implies essentially flat yearly revenue growth and an earnings increase of about US$0.1b from current earnings of roughly US$2.2b.
How The T. Rowe Price Group Valuation Ties Back To Wealth Expansion
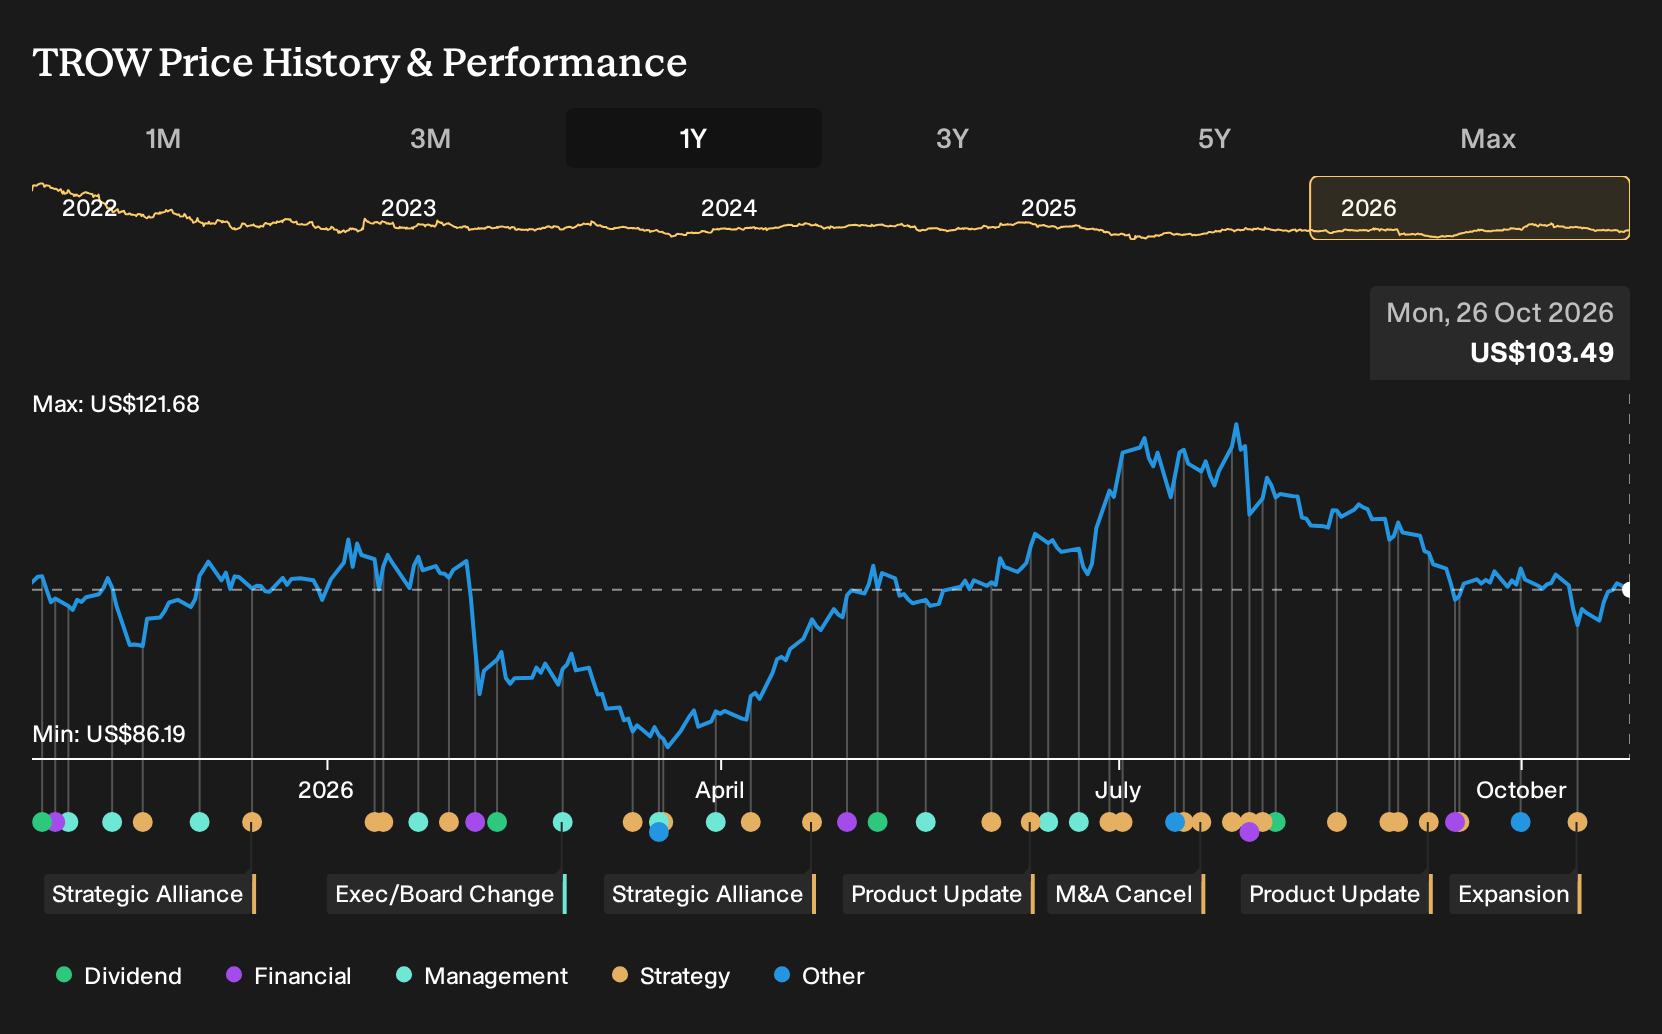
On the valuation side, the consensus view circles around a price target of US$106.0, only 4.3% above the recent share price of US$101.39. That tight gap suggests analysts see T. Rowe Price Group as roughly in line with their modeled earnings and revenue profile rather than offering a wide margin of safety or a clear mispricing. The range of targets, from US$90.0 to US$116.0, signals some disagreement about how much the product mix shift and advisor hiring will translate into future profitability.
To sit in the same camp as that consensus, you would need to be comfortable with 2029 forecasts of US$7.6b in revenue, US$2.3b in earnings, and a P/E of 11.7x on those projected profits. That multiple is above the current 10.0x that analysts cite for T. Rowe Price Group but still well below the 37.6x figure they report for the broader US capital markets group. In other words, the implied scenario is that the business remains a relatively lower multiple asset within its sector, even if earnings grind higher over time.
The key link back to the advisors and wealth channel build out is the earnings bridge that supports that 11.7x assumption. Flat revenue with slightly better margins and fewer shares is what gets the model from US$2.2b of earnings today to US$2.3b in 2029. If the new client facing headcount can help stabilize flows in retirement strategies and push more assets into active ETFs, SMAs, and alternatives, then that modest uplift in profit looks more achievable within the analyst framework already on the table.
Uncover why T. Rowe Price Group's fair value suggests that T. Rowe Price Group is closely aligned with its current market price.
Exploring Other Perspectives
One alternate view focuses squarely on continuing fee pressure. The most cautious analysts were assuming T. Rowe Price Group’s revenue would decline about 1.1% a year to roughly US$7.4b by 2029, with earnings stuck near US$2.2b. You can read that as a far more skeptical story than consensus. This fresh wealth build could be exactly the sort of development that prompts those forecasts to be revisited.
Explore 3 other T. Rowe Price Group fair value estimates, including one that suggests it could be worth just $106.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your T. Rowe Price Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T. Rowe Price Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T. Rowe Price Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond T. Rowe Price Group?
If T. Rowe Price Group's wealth channel story has sharpened your thinking, it can help to line it up against other opportunities that fit different portfolio roles. The Simply Wall St Screener offers several focused filters so you can quickly narrow the field to companies that match your risk appetite and income needs.
- If capital preservation sits high on your list, consider reviewing a group of companies screened for resilience through the 30 resilient stocks with low risk scores.
- If you want potential mispricing paired with quality fundamentals, scan a curated basket of opportunities via the 29 high quality undervalued stocks.
- If reliable income matters to you, check out a collection of higher yielding payers using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com