


- Wall Street analysts recently projected that Brinker International could report quarterly earnings of $2.49 per share and revenue of $1.45 billion, with forecasts highlighting Chili’s company sales and comparable restaurant sales as key contributors.
- The focus on Chili’s segment performance, including both company operated units and comparable restaurant sales, gives investors a clearer view of where Brinker International’s operating strength is concentrated.
- We will now look at how Brinker International's projected 29% earnings per share increase might influence the broader investment narrative.
See how Brinker International's projected earnings momentum compares with other potential breakouts across our hand picked 29 high quality undervalued stocks.
Brinker International Investment Narrative Recap
To own Brinker International, you need to be comfortable that Chili’s can keep pulling in steady traffic with value focused pricing while cost pressures stay contained. The current earnings and revenue projections sharpen that question rather than change it. The key near term catalyst is whether menu, digital and to go efforts keep comparable sales healthy without eroding guest value perception.
The biggest operational risk remains rising labor and non labor expenses, plus any drag from Maggiano’s if it continues to underperform Chili’s. The projected 29% earnings per share lift does not remove that concern. It simply raises the bar for execution on efficiency, throughput gains and off premise growth.
The clearest announcement tied to this setup is the emphasis on Chili’s higher earning restaurant model and value platform, including items like $10.99 meals and $6 margaritas. Those offers, together with Better Than Fast Food positioning, are already embedded in how analysts frame the projected $2.49 EPS and 7.3% revenue increase.
For you as a shareholder, that focus means the next few quarters are really a test of Chili’s operating playbook. If digital ordering, to go expansion around roughly 25% of sales, and simplified in restaurant workflows keep supporting average unit volumes and margins, the current earnings momentum looks more repeatable. If not, cost inflation and brand concentration risk stay front of mind.
Brinker International Earnings Outlook In Context
Brinker International's current analyst setup leans heavily on quantified expectations rather than vague optimism. Revenue is assumed to rise by 5.3% each year over the next three years, while profit margins are expected to shift from 8.4% today to 9.2% by 2029. If that occurs, more of Chili's sales mix would flow to the bottom line, based on the current modeling.
On the earnings side, analysts are working off current profits of US$487.0 million and a consensus view that Brinker International could reach US$623.0 million by 2029. That move represents an earnings increase of roughly US$136.0 million from today's level and is tied to both higher margins and an estimated 6.0% annual reduction in share count over the next three years.
Those income projections are linked directly to the long term revenue math referenced in stock commentary. The consensus case implies Brinker International could produce about US$6.8b in sales and US$623.0 million in earnings by 2029, with the equity trading at a P/E of 18.9x on those profits, described as broadly in line with the current US Hospitality peer multiple cited in the report.
Brinker International's narrative sets out a path to revenues of about US$6.8b and earnings of US$623.0 million by 2029, based on 5.3% yearly revenue growth and an earnings increase of roughly US$136.0 million from current earnings of US$487.0 million.
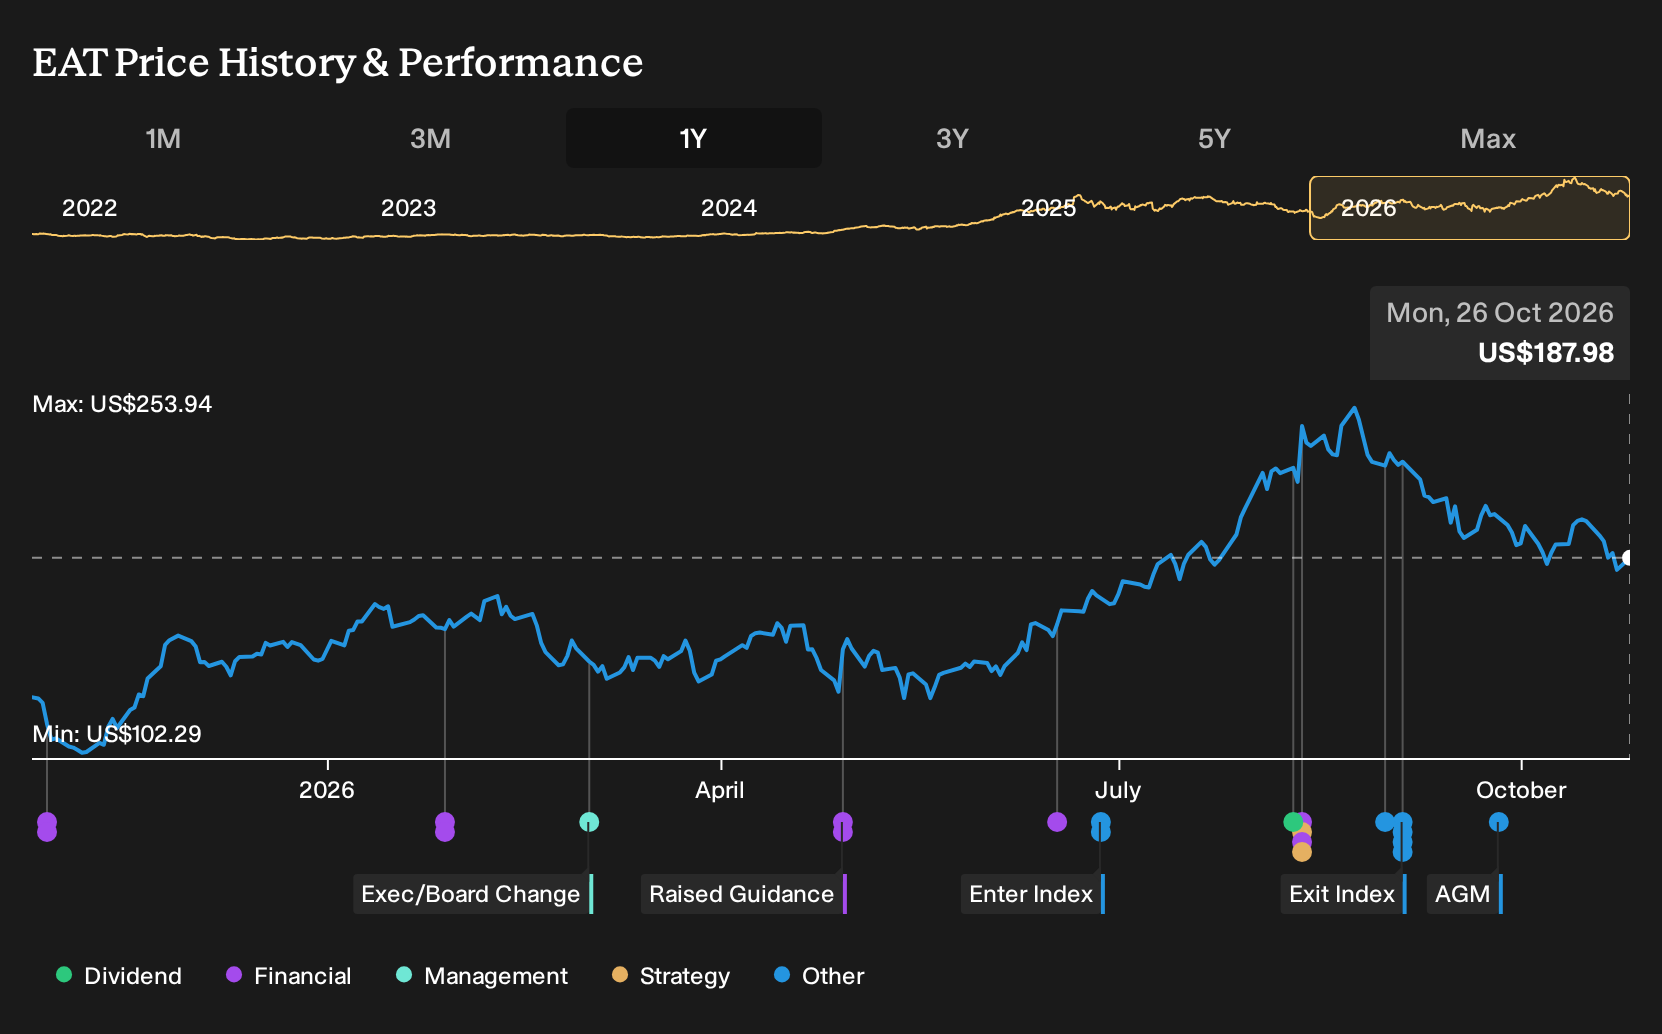
Uncover why Brinker International's fair value indicates a 40% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Brinker International leans hard into margin risk. The most cautious analysts were modeling revenue of about US$6.6b and earnings of roughly US$547.0 million by 2029, with an 8.3% margin. You can see how different that is from consensus, and the fresh EPS and revenue news may push both stories to evolve.
Explore 2 other Brinker International fair value estimates, including one that indicates up to 10% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brinker International research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brinker International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brinker International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Brinker International?
If Brinker International has sharpened your thinking around earnings quality, capital returns and brand execution, it can be useful to line that up against other opportunities using a structured stock search instead of scattered headlines.
- If you want a shortlist of companies where price and fundamentals both work in your favor, start with a curated 29 high quality undervalued stocks that filters for quality metrics as well as valuation.
- For investors who care most about balance sheet resilience and financial staying power, focus on a list of solid balance sheet and fundamentals (24 results) that only includes businesses with stronger underlying support.
- When you are hunting for less crowded opportunities with cleaner fundamentals, scan a 21 high quality undiscovered gems that highlights quality stocks the market may not be watching closely yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com