


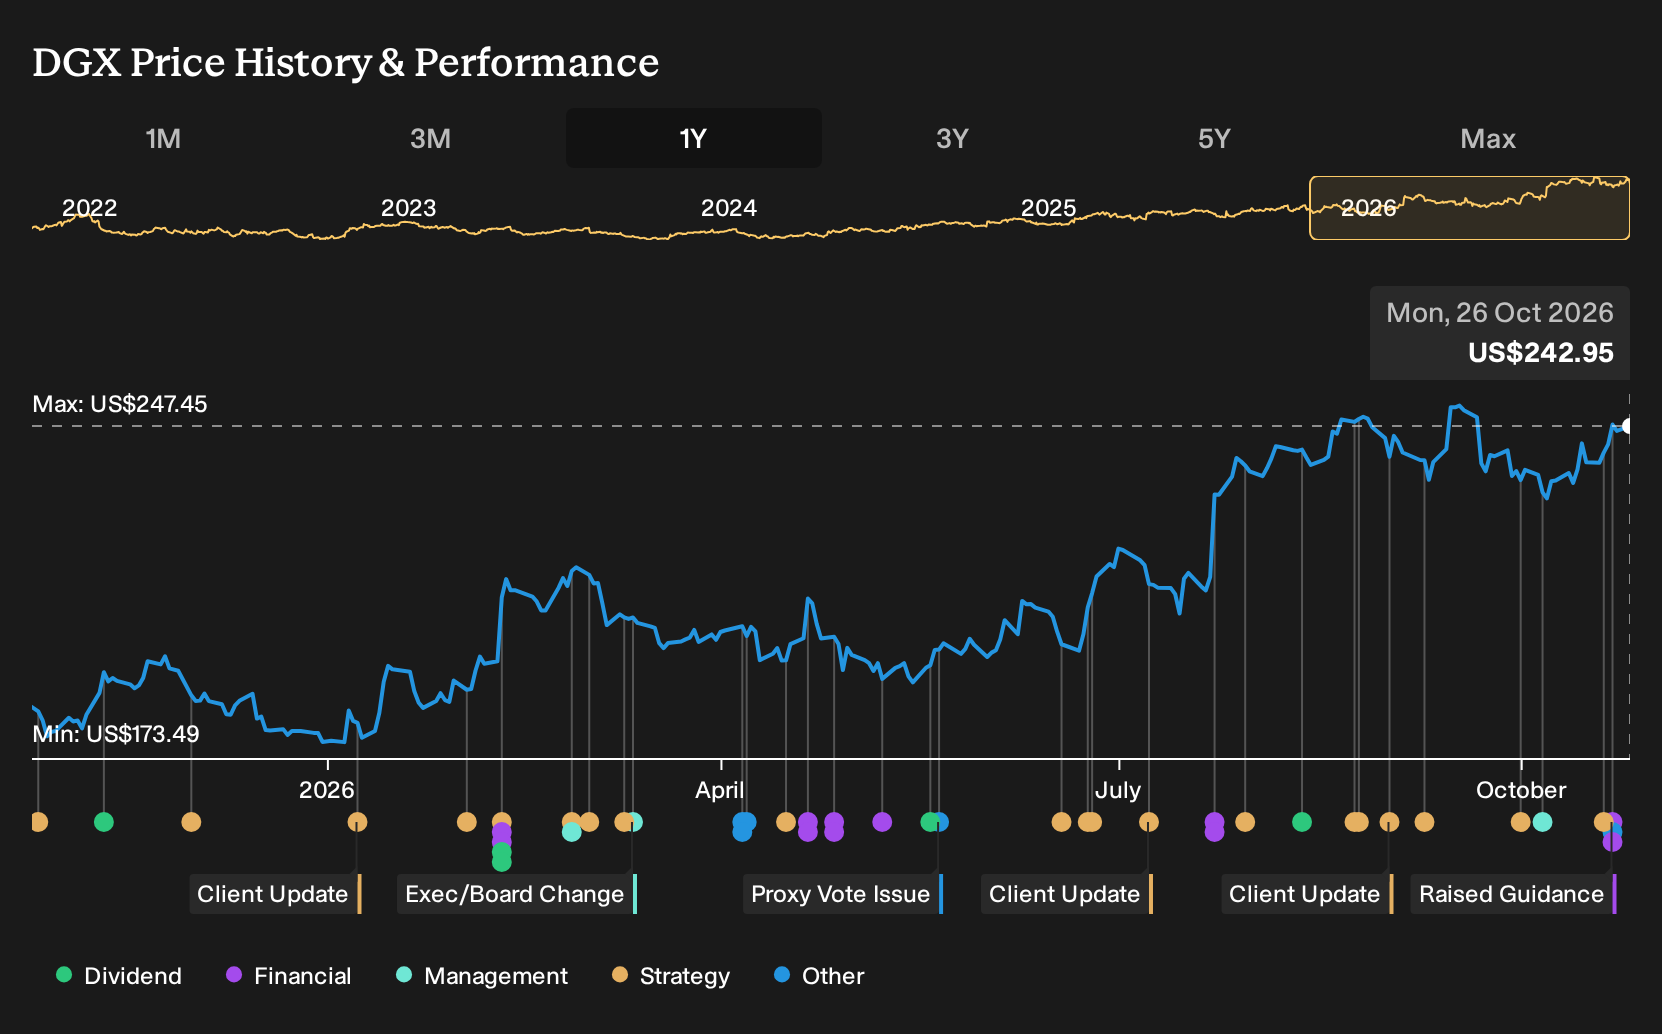
- Quest Diagnostics raised its 2026 net revenue outlook to US$12.065b to US$12.105b and lifted reported diluted EPS guidance to US$10.21 to US$10.31 after reporting higher third quarter and nine month sales and earnings compared with the prior year.
- The tighter and higher guidance range, coming alongside increased sales and earnings per share, reflects greater visibility into Quest Diagnostics' current operating performance and cost structure.
- This article will now examine how Quest Diagnostics' higher full year earnings guidance could influence the existing investment narrative around efficiency and growth.
Quest Diagnostics Investment Narrative Recap
To own Quest Diagnostics, you need to believe the lab operator can keep growing higher value testing, keep its consumer channels scaling, and make automation and AI offset rising costs. The higher 2026 revenue and EPS guidance, backed by stronger third quarter and nine month figures, supports that near term execution is on track rather than changing the thesis.
The key near term catalyst remains whether cost savings from automation and efficiency can keep margin trends moving in the right direction despite wage and inflation pressure. The biggest risk still sits with reimbursement cuts and policy driven volume headwinds, and this guidance update does not remove those structural pressures.
The Waters collaboration around the FDA cleared Onclarity Self Collection Kit ties directly into Quest Diagnostics existing focus on advanced and preventive testing and consumer initiated access. Expanding at home cervical cancer screening through Quest physician, health plan, consumer, and patient service center channels points to another potential volume and mix lever over time.
Operationally, this kind of partnership leans into two current catalysts for the business. First, it pushes more preventive testing into Quest Diagnostics labs, where automation and AI tools are already running. Second, it builds out the consumer health and wellness pipeline, which could help offset future reimbursement pressure if management continues to execute on volume, service quality, and cost control.
What The Quest Diagnostics Forecasts Assume
Quest Diagnostics' current analyst playbook is built around measured expansion rather than a dramatic reset of expectations. Consensus models point to revenues of US$13.3b and earnings of US$1.5b by 2029, tied to an assumed 4.8% annual increase in revenue over the next three years and a margin lift from 9.2% today to 11.0%.
On the earnings line, the step up from US$1.1b today to US$1.5b implies an increase of about US$400m over the period, which is a sizeable move for a business of this scale. That change reflects not just top line growth but also a belief that automation, AI tools, and lab productivity programs continue to raise profitability as a greater mix of advanced testing runs through Quest Diagnostics' network.
Those same assumptions underpin the current P/E logic around the stock. Analysts are effectively underwriting a shift from a 25.4x multiple on today's earnings to 23.1x on the 2029 consensus profit figure, with a discount rate of roughly 7.2% to 7.24% used to bring those cash flows back to today. In simple terms, this means relying on higher earnings and slightly lower valuation multiples leading to an outcome that is broadly similar to current pricing.
Quest Diagnostics' narrative projects US$13.3b in revenue and US$1.5b in earnings by 2029, which assumes 4.8% yearly revenue growth and an earnings increase of about US$400m from US$1.1b today.
Uncover why Quest Diagnostics' fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Quest Diagnostics from the Simply Wall St Community span roughly US$254 to US$333 across 2 different views, so you are seeing both low and high conviction pricing. When you set that beside rising 2026 guidance, at home cervical screening plans, and ongoing reimbursement and cost pressure, you have plenty of room for differing opinions that are worth exploring before deciding how this story fits your portfolio.
Explore another Quest Diagnostics fair value estimate, including one that suggests up to 37% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Quest Diagnostics research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quest Diagnostics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quest Diagnostics' overall financial health at a glance.
Looking for more investment ideas beyond Quest Diagnostics?
If the updated guidance and shifting forecasts around Quest Diagnostics have you thinking about broader opportunities, it can help to scan for other businesses that line up with the kind of balance sheet, income profile, or payout style you prefer. The Simply Wall St Screener offers a range of focused filters that can narrow a very wide universe into a workable watchlist in a few minutes.
- For investors who care most about financial resilience and clean balance sheets, start by reviewing a list of solid balance sheet and fundamentals (24 results) that aims to reduce the chance of nasty surprises when conditions get tougher.
- If capital preservation and a smoother ride matter to you more than chasing every rally, consider a 30 resilient stocks with low risk scores that concentrates on businesses with lower risk scores and steadier fundamentals.
- Income focused readers who want cash returns today as well as potential capital growth can assess a 5 dividend fortresses that screens for higher yielding companies with the potential for more dependable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com