


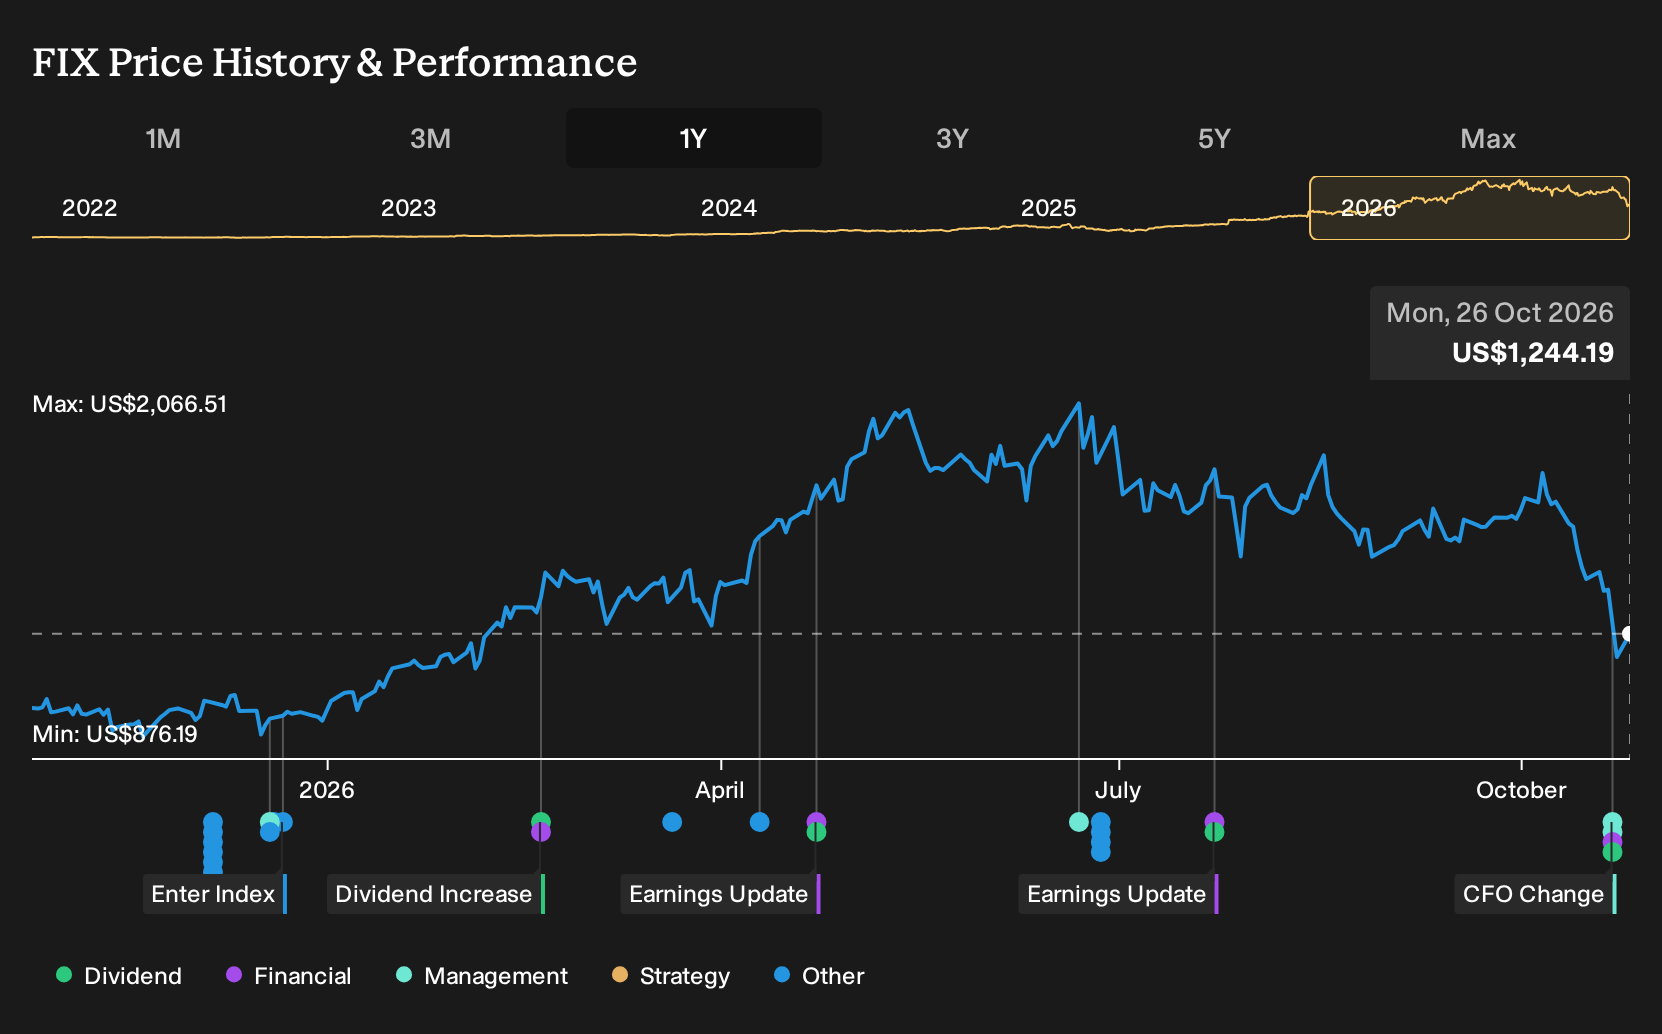
- Comfort Systems USA reported third quarter 2026 sales of US$3,766.3 million and net income of US$489.04 million, alongside a nine month sales figure of US$9,897.29 million and net income of US$1,301.02 million. The board also approved a quarterly dividend of US$1.00 per share.
- Management highlighted a record backlog supported by technology and industrial projects. Long serving CFO Bill George plans to retire in 2027, and experienced insider Julie Shaeff is set to assume the finance role, signaling continuity in capital allocation and financial oversight.
- We will now look at how Comfort Systems USA's backlog and recent earnings performance could influence the existing investment narrative.
Comfort Systems USA Investment Narrative Recap
For Comfort Systems USA, the core belief is that its record US$14.1b backlog in technology heavy and industrial projects can be converted efficiently into revenue and cash. In the short term, the key variable is execution on large AI, data center and semiconductor related builds while keeping labor, material and equipment costs under control.
The biggest near term risk is any cooling of technology build programs or policy delays that slow project awards and push out backlog conversion. Recent third quarter results and a dividend increase support the existing narrative, but they do not remove concerns about project mix, margin pressure and the possibility of investors reassessing the current P/E multiple.
The most relevant announcement here is the planned retirement of long time CFO Bill George after the 2026 Form 10 K filing, with Senior Vice President and Chief Accounting Officer Julie Shaeff stepping into the finance role. For a business as project intensive as Comfort Systems USA, investors often watch finance leadership closely when backlog and modular capacity are expanding quickly.
Shaeff has been Chief Accounting Officer since 2005 and has deep history with the company and its reporting systems. That continuity may help execution on capital allocation, acquisition screening and balance sheet management at a time when margin risks, insider selling and valuation questions are prominent catalysts for how the stock trades around each earnings update.
Comfort Systems USA's current analyst narrative points to revenue of US$24.2b and earnings of US$3.4b by 2029, based on assumed yearly top line growth of 24.5% and an earnings increase of about US$1.8b from US$1.6b today.
Uncover why Comfort Systems USA's fair value indicates a 68% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between US$1,808 and about US$2,394, with some contributors seeing Comfort Systems USA as priced well above their intrinsic value views. Set that against record backlog, a higher dividend, and an incoming CFO, and you get sharply different opinions that you should review directly.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests it could be worth just $1808!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking For More Ideas Beyond Comfort Systems USA?
If the Comfort Systems USA story has sharpened your thinking, use that momentum to scan a broader field of opportunities where balance sheets, income statements and dividend policies all line up with what you are looking for.
- If resilience matters most to you, start with a 30 resilient stocks with low risk scores that aims to filter for businesses with steadier risk profiles and fewer financial red flags.
- For investors hunting for quality at a sensible price, cast a wider net with a 29 high quality undervalued stocks that focuses on strong fundamentals at more modest valuations.
- When balance sheet strength is non negotiable, focus your research on a list of solid balance sheet and fundamentals (24 results) and look for companies where debt, cash and assets work in your favor.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com