


Riot Platforms has seen its share price fall sharply in recent months, which puts fresh attention on a basic question for investors who follow the stock closely. Given that backdrop and the shift in its business focus, is the current valuation supported by the sales the company generates today and the revenue it may be able to earn from its assets over time?
- Over the past 5 years the stock has declined 55.2%. That puts the spotlight firmly on whether the business now produces enough sales to support even the lower share price.
- Riot is investing heavily to move from pure Bitcoin mining into AI focused data center infrastructure. This can affect how quickly its sales grow relative to the capital tied up in specialized equipment and facilities.
- The analysts covering Riot Platforms have run their own numbers. See what analysts think Riot Platforms's shares could be worth.
The issue now is whether Riot Platforms' recent share price reflects a level of sales that looks reasonable when compared with the Fair Ratio benchmark for this type of valuation lens.
If you are weighing Riot Platforms against other companies tied to digital assets and AI infrastructure themes, it can help to compare it with 16 cryptocurrency and blockchain stocks.
Has Riot Platforms Run Too Far on Sales?
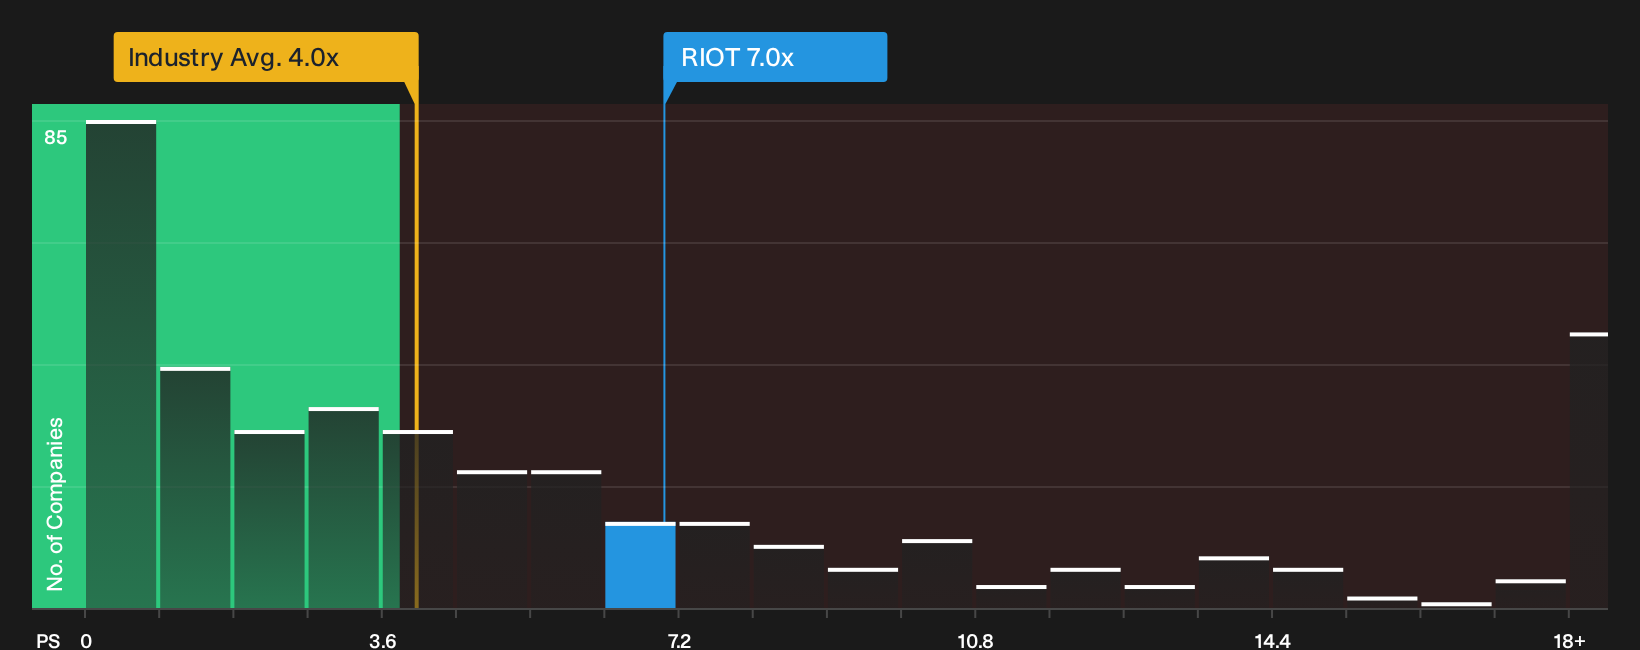
P/S is a useful lens for Riot Platforms because investors are currently paying more attention to its revenue base than to its volatile earnings. On this measure, the stock trades at about 7.0x trailing sales, which is higher than both the broader software industry on roughly 4.0x and its more direct peers around 12.9x.
The Fair Ratio model, which adjusts the P/S multiple for Riot Platforms' risk profile, margins and business mix, points to a lower level than where the shares currently change hands. That gap suggests the stock screens as overvalued on this sales based yardstick, even after a share price drop tied to concerns over costly AI data center expansion. For anyone considering the story around Bitcoin exposure and AI infrastructure, the key question is whether future contracts and utilization can eventually justify paying this kind of revenue multiple over time. Explore the numbers behind Riot Platforms's P/S valuation.
The Riot Platforms Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Riot Platforms pick up where this valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today’s price on the Community page. Rather than a single output, each framework sets out the assumptions behind its estimate of fair value so you can compare those expectations with the actual numbers as results come through.
One of the top community narratives on Riot Platforms: 59% undervalued
"Riot Platforms is building on its earlier plan to grow a scalable data center business by locking in a 20-year, 191 MW lease with a frontier AI lab..."
Discover why this Narrative puts Riot Platforms at 59% undervalued.
Riot Platforms’ valuation still leaves one crucial piece off the table
The next thing to check is who is actually steering Riot Platforms, how their incentives are structured, and whether those rewards line up with your expectations as a shareholder. See who runs Riot Platforms and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com