


Williams Companies (WMB) heads into its November 2 earnings release with investor attention elevated, as analysts have recently lifted quarterly estimates and a positive Earnings ESP of 1.65% signals expectations for a potential upside surprise.
Recent trading reflects that heightened attention. The share price is up 3.6% over the past month and 17.9% year to date, while total shareholder return of 28.2% over one year and more than double over five years points to momentum that has been building rather than fading.
Scan how Williams Companies compares with a curated set of energy infrastructure peers by running your lens across 42 power grid technology and infrastructure stocks in light of this earnings momentum story.
Bulls see Williams Companies riding earnings momentum toward a richer multiple. Bears argue the rally already prices in that optimism. Which case does the current valuation lean toward as earnings approach?
Most Popular Narrative: 16% Undervalued
Williams Companies is framed by the most widely followed narrative as trading below its inferred fair value of $85.61, compared with the recent $71.75 close. This puts real weight on the projects driving that gap.
The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects such as Socrates and Neo that carry multi year contracts. These can add incremental contracted earnings and improve overall returns on invested capital. The commercialization of Neo, a 682 MW behind the meter power project with a 12.5 year contract and an expected build multiple of about 5x, together with continued phases of Socrates, provides Williams Companies with a growing base of long duration power cash flows that can support EBITDA growth beyond the traditional pipeline business.
See why 30 investors see Williams Companies as 16% undervalued.
Result: Fair Value of $85.61 (UNDERVALUED)
Still, that 4.1x leverage path and the risk of permitting setbacks on projects like Haynesville links could quickly challenge the Williams Companies undervaluation story.
Find out about the key risks to this Williams Companies narrative.
Another View: What Multiples Say About Williams Companies
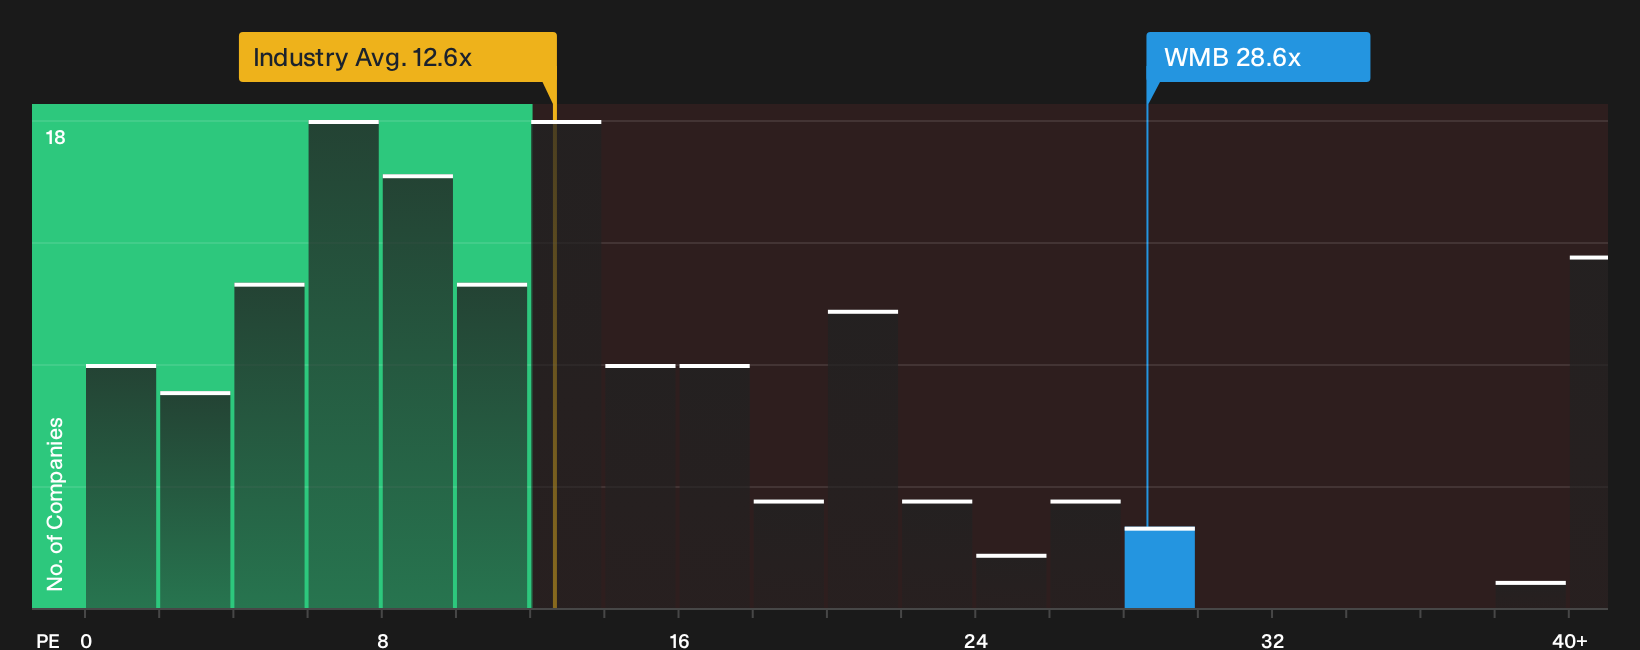
The discounted cash flow workup paints Williams Companies as deeply undervalued, yet the P/E ratio tells a different story. The stock trades at 28.6x earnings, compared with 15.2x for peers and 12.6x for the wider US Oil and Gas group, while the fair ratio is 23.7x.
That premium suggests investors already pay up for Williams Companies future earnings. This raises an obvious question: if sentiment cools and the valuation drifts closer to the fair ratio or sector levels, how much of the perceived upside would still be left on the table?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Williams Companies valuation and risk reward profile can look noisy. Move quickly, review both sides of the story, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Williams Companies?
Williams Companies gives you one angle on the energy story, but the real edge comes from lining it up against other clear, data driven opportunities.
- Target resilience by scanning companies with strong finances and steady balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by reviewing companies that screen as promising yet overlooked using the 21 high quality undiscovered gems.
- Prioritize sleep at night comfort by focusing on businesses that earn resilient risk scores with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com