


Viatris Inc. (VTRS), headquartered in Canonsburg, Pennsylvania, operates as a healthcare company. With a market cap of $20.7 billion, the company produces medicines for patients across broad range of major therapeutic areas spanning both noncommunicable and infectious diseases. The global healthcare giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Nov. 5.
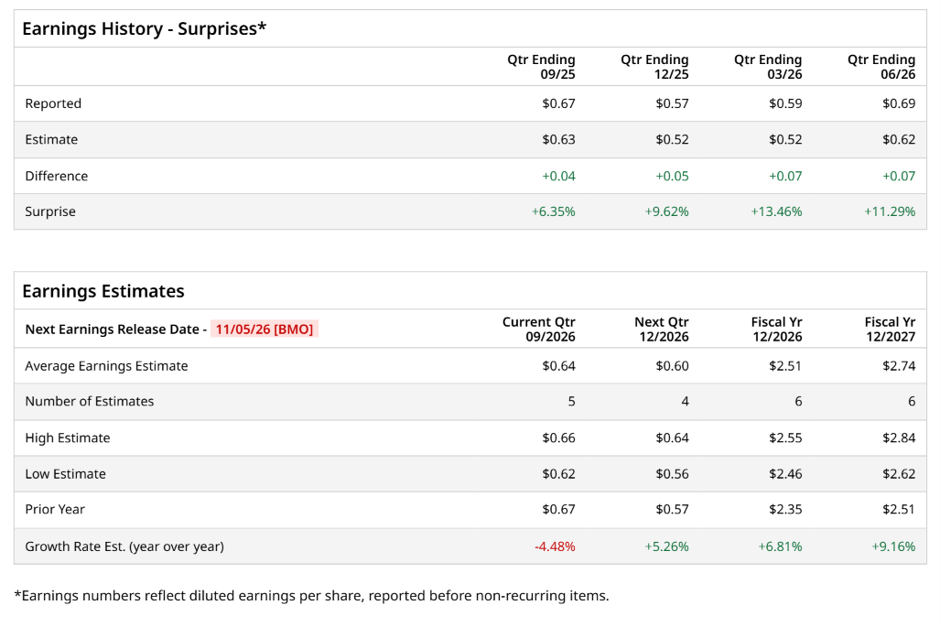
Ahead of the event, analysts expect Viatris to report a profit of $0.64 per share on a diluted basis, down 4.5% from $0.67 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Viatris to report EPS of $2.51, up 6.8% from $2.35 in fiscal 2025. Its EPS is expected to rise 9.2% year over year to $2.74 in fiscal 2027.
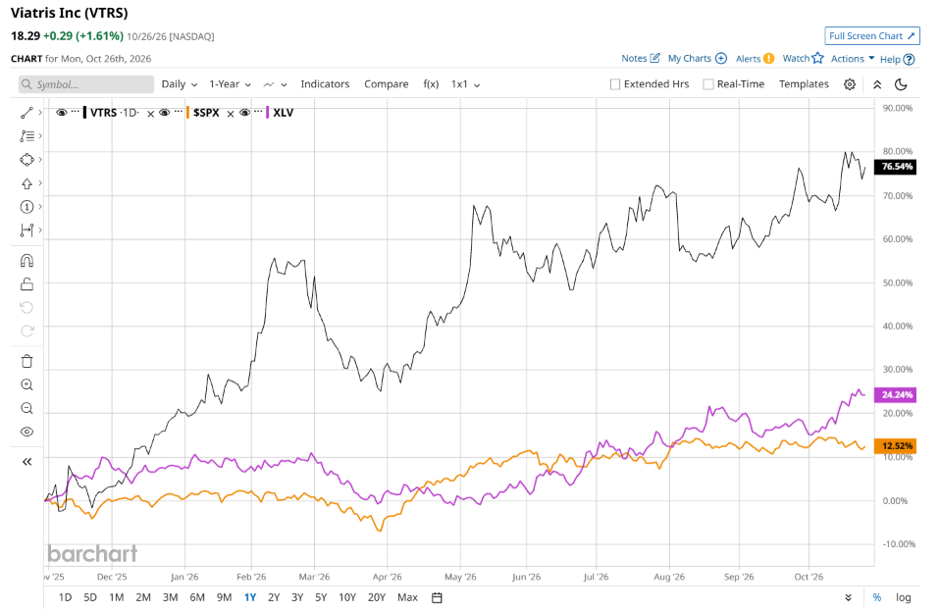
VTRS stock has considerably outperformed the S&P 500 Index’s ($SPX) 13% gains over the past 52 weeks, with shares up 76.7% during this period. Similarly, it notably outperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 22.8% returns over the same time frame.
Viatris delivered a solid performance driven by double-digit commercial growth in Greater China, robust demand for complex generics in North America, and disciplined cost control. While near-term headwinds from supply chain disruptions and China’s policy changes weighed on margins, the company is positioning itself for long-term growth through key pipeline catalysts, including recent approvals for the GwynLo patch and WAKIX in Japan, alongside portfolio-reshaping moves like the divestment of Tyrvaya and its Biocon stake.
Analysts’ consensus opinion on VTRS stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 11 analysts covering the stock, six advise a “Strong Buy” rating, four give a “Hold,” and one recommends a “Moderate Sell.” VTRS’ average analyst price target is $20.36, indicating a potential upside of 11.3% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.