


In the last week, the United States market has been flat, but it is up 8.1% over the past year with earnings forecasted to grow by 17% annually. In this environment, identifying stocks that are potentially undervalued and exhibit insider buying can be a strategic approach for investors seeking opportunities in small-cap companies.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.4x | 0.5x | 32.08% | ★★★★★☆ |
| Enovis | NA | 0.5x | 38.24% | ★★★★★☆ |
| Union Bankshares | 9.3x | 2.0x | 25.94% | ★★★★☆☆ |
| Tilray Brands | NA | 0.4x | 16.91% | ★★★★☆☆ |
| German American Bancorp | 13.5x | 5.1x | 23.63% | ★★★☆☆☆ |
| Bank of Marin Bancorp | NA | 7.4x | 35.69% | ★★★☆☆☆ |
| Tennant | 61.1x | 0.9x | 21.79% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.6x | 2.6x | 7.02% | ★★★☆☆☆ |
| Chain Bridge Bancorp | 12.6x | 5.1x | 46.33% | ★★★☆☆☆ |
| Citizens Community Bancorp | 17.1x | 3.8x | 6.95% | ★☆☆☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Citizens Financial Services (CZFS)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Citizens Financial Services operates primarily in community banking, with a focus on providing financial services to local communities, and has a market cap of $0.31 billion.
Operations: The primary revenue stream for CZFS is Community Banking, generating $114.76 million. Operating expenses have been a significant part of the cost structure, with general and administrative expenses reaching $50.61 million in the latest period. The net income margin has shown variability, recently recorded at 35.77%.
PE: 9.9x
Citizens Financial Services, a smaller player in the U.S. market, recently showcased insider confidence with share purchases in the past quarter. Despite a low allowance for bad loans at 57%, they reported solid earnings growth: net income rose to US$10.19 million for Q2 2026 from US$8.46 million year-on-year, and earnings per share increased to US$2.12 from US$1.76. The company also affirmed a quarterly dividend of US$0.51 per share, indicating financial stability amidst its challenges.
ADTRAN Holdings (ADTN)
Simply Wall St Value Rating: ★★★☆☆☆
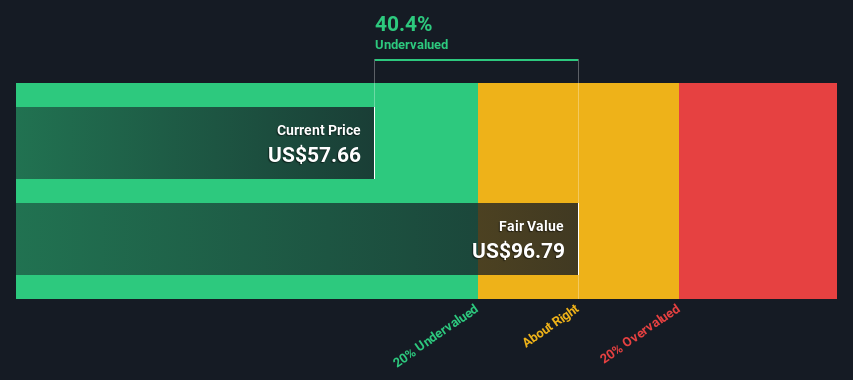
Overview: ADTRAN Holdings focuses on providing network solutions and services, with a market cap of approximately $1.29 billion.
Operations: ADTN generates revenue primarily from its Network Solutions and Services & Support segments, with the former contributing significantly more. The company has experienced fluctuations in gross profit margin, with recent figures showing a decrease to 28.95%. Operating expenses are substantial, driven by R&D and general administrative costs.
PE: -23.5x
ADTRAN Holdings, a technology player in network management and AI-driven solutions, demonstrates potential as an undervalued stock. Despite its reliance on external borrowing for funding, the company forecasts impressive annual earnings growth of 92.28%. Recent product launches like Mosaic One Agents highlight innovation in AI integration. Insider confidence is evident with recent share purchases by executives, suggesting belief in future prospects. The company's strategic board appointment and expanding market presence further bolster its growth trajectory.
- Take a closer look at ADTRAN Holdings' potential here in our valuation report.
Gain insights into ADTRAN Holdings' past trends and performance with our Past report.

Chain Bridge Bancorp (CBNA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Chain Bridge Bancorp operates as a banking institution, focusing on providing a range of financial services, with a market cap of $0.24 billion.
Operations: CBNA generates revenue primarily from its banking operations, with a notable net income margin trend peaking at 41.07% in Q3 2024 before slightly decreasing to 40.52% by mid-2026. Operating expenses are significant, with general and administrative costs being a major component, reaching $28.01 million by mid-2026.
PE: 12.6x
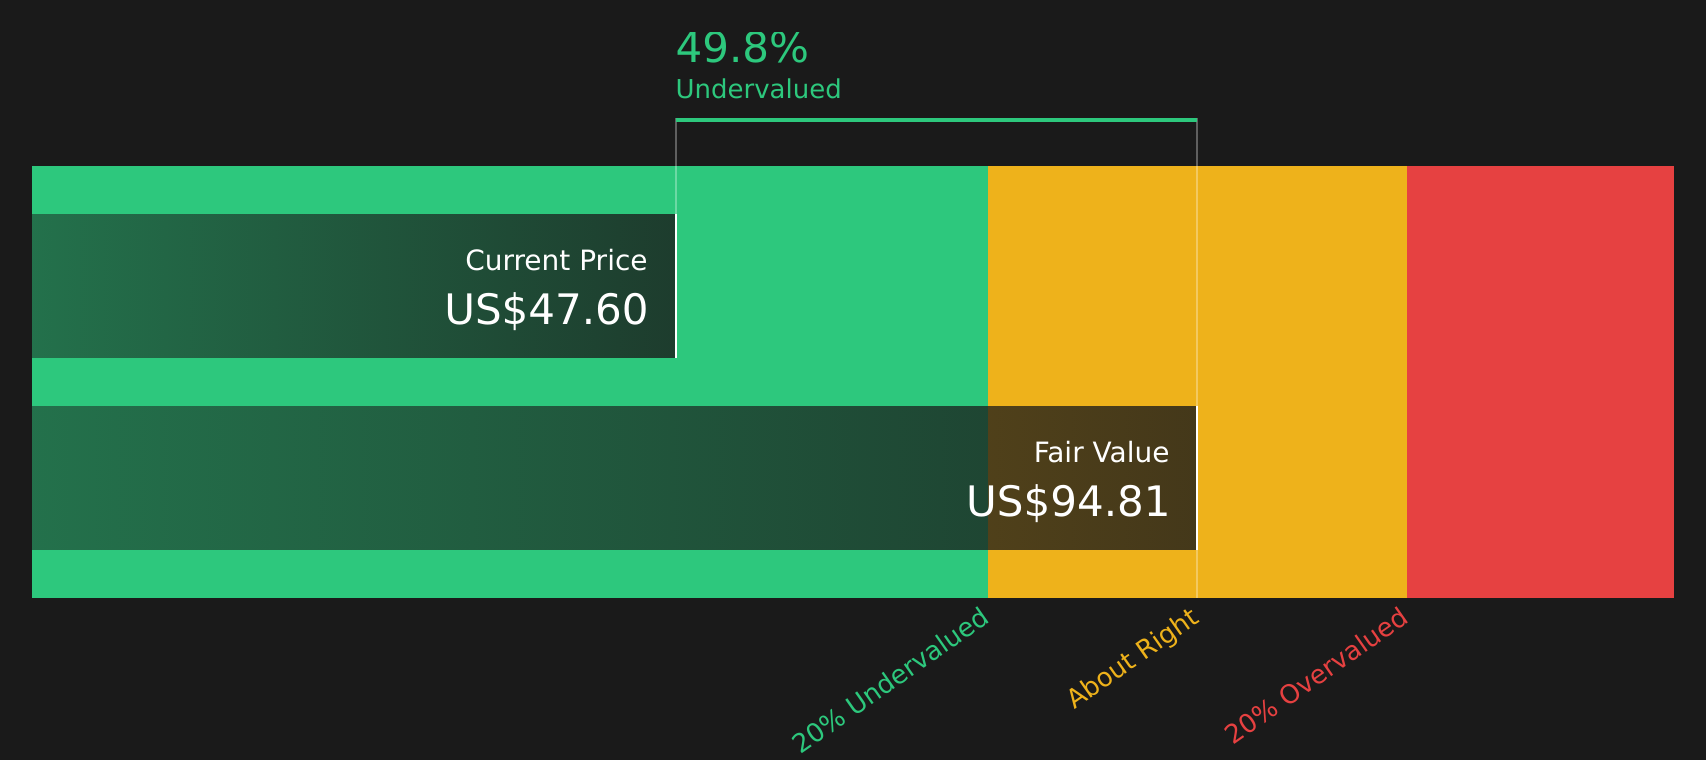
Chain Bridge Bancorp is capturing attention with its recent financial performance and insider confidence. In the second quarter of 2026, net income soared to US$9.51 million from US$4.58 million a year ago, while earnings per share doubled to US$1.45. Insiders have been purchasing shares consistently over the past few months, signaling strong belief in the company's potential. With earnings projected to grow annually by 14%, Chain Bridge offers intriguing prospects for those eyeing growth in smaller companies within the banking sector.
Make It Happen
- Click here to access our complete index of 66 Undervalued US Small Caps With Insider Buying.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com