


Coeur Mining has fallen sharply in recent weeks, yet over a three year window the stock has delivered a very large gain, so the obvious question is whether that journey now lines up with the earnings investors are paying for. With the next set of financial results on the calendar and the share price under pressure again, the market is effectively being asked what level of profit power it wants to ascribe to Coeur Mining today.
- Over the past three years the share price has climbed about 4.3x, which puts a lot of weight on whether the current earnings base can support that kind of reset in expectations.
- The company plans to release fresh operational and financial numbers soon, which can reshape how investors think about its future profit trajectory and the price they are willing to pay for those earnings.
- The analysts covering Coeur Mining have run their own numbers. See what analysts think Coeur Mining's shares could be worth.
The issue now is whether Coeur Mining's current share price is justified by the earnings it is generating and what investors expect those profits to look like over time.
If you are weighing whether Coeur Mining's recent slide still matches its earnings profile, it can help to compare that same question across 29 high quality undervalued stocks.
Is Coeur Mining a Bargain on Earnings?
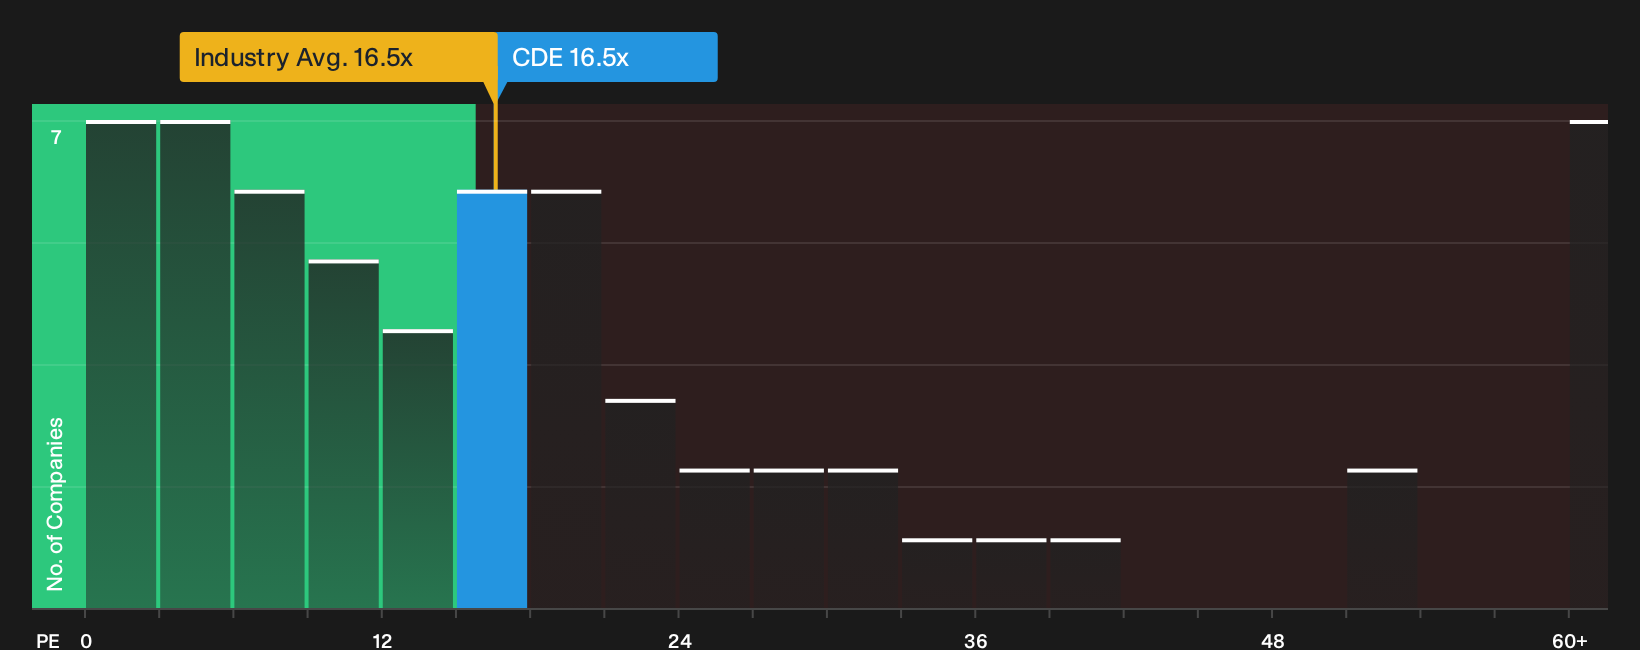
The P/E ratio is a useful yardstick for Coeur Mining because earnings are a key driver of how investors tend to value metals producers. Coeur Mining currently trades on a P/E of 16.5x, which is almost identical to the wider Metals and Mining industry average of about 16.5x. That puts the stock roughly in line with how the market is pricing earnings across the sector, rather than at a clear premium or discount to the usual sector yardstick.
The fair-value model points to a higher P/E than this as a rough anchor for Coeur Mining, so the present 16.5x reading screens as undervalued against that tailored benchmark. Because the stock has fallen sharply in recent weeks despite a recent Benzinga piece flagging the potential for a breakout, the market is still valuing the earnings stream at a level that implies some caution relative to that model. For anyone weighing whether the recent pullback has gone too far, that gap between the live multiple and the modelled range is the key figure to study next. Explore the numbers behind Coeur Mining's P/E valuation.
The Coeur Mining Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coeur Mining valuation puzzle leaves off. They spell out what kind of growth, profitability and earnings profile would need to materialise for Coeur Mining's current P/E and share price to look either stretched or conservative, and each one treats fair value as a thesis about the business that can be tracked over time rather than a single frozen estimate. These Narratives sit on Simply Wall St's Community page.
One of the top community narratives on Coeur Mining: 42% undervalued
"Aggressive brownfield exploration and land package expansion at existing sites are likely to extend mine life and expand reserves..."
Discover why this Narrative puts Coeur Mining at 42% undervalued.
One more Coeur Mining checkpoint that sits beside the share price
Before you stop at the P/E chart and recent share moves, it is worth asking who is steering Coeur Mining, how they are rewarded and whether those incentives line up with your interests. See who runs Coeur Mining and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com