


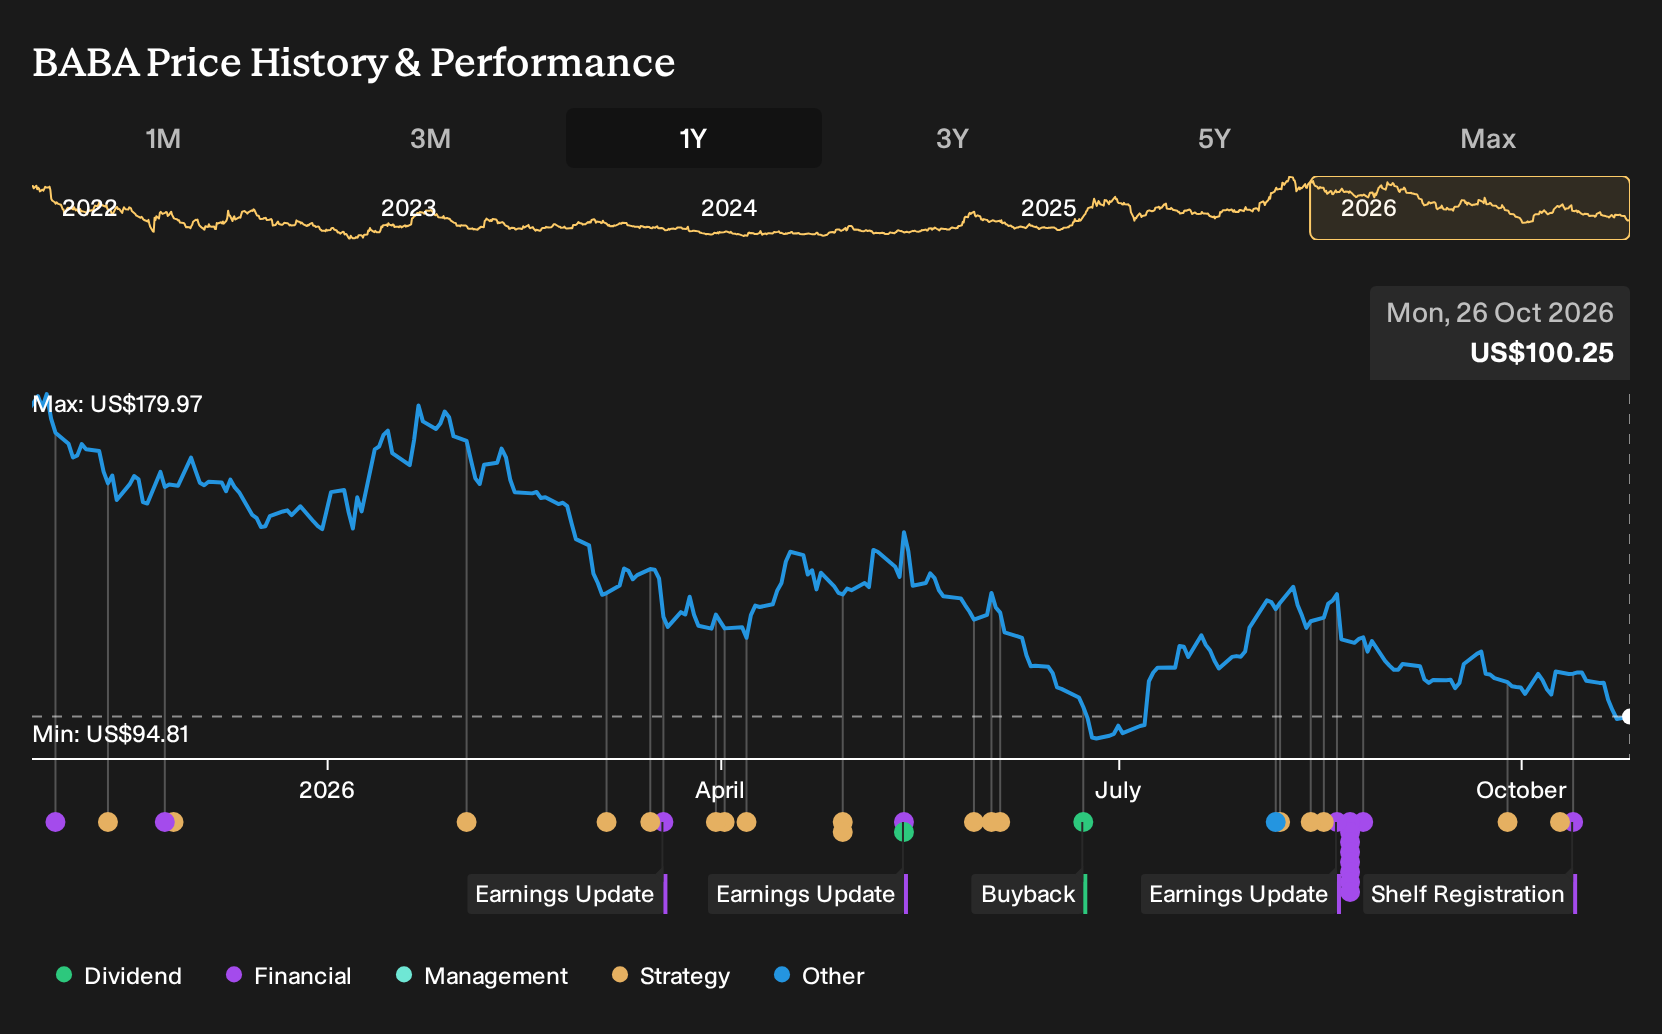
- Alibaba Group Holding recently faced renewed regulatory scrutiny from China’s State Administration for Market Regulation, while Chinese technology and AI linked stocks experienced fresh selling pressure and valuation concerns.
- The company’s push into AI and cloud, already absorbing heavy investment and compliance costs, now contends with tighter oversight. This could influence margins, execution timelines and capital allocation choices.
- We will examine how Alibaba Group Holding's investment narrative is tested by SAMR’s renewed scrutiny of e commerce platforms and AI driven businesses.
Alibaba Group Holding Investment Narrative Recap
To stay comfortable as a shareholder in Alibaba Group Holding, you need to believe that heavy AI, cloud and quick commerce spending eventually turns into durable cash generation, not just headline revenue. The sharp pullback in Chinese tech and AI linked stocks, plus renewed SAMR scrutiny, keeps that thesis under pressure but does not change what needs to go right operationally.
The key near term catalyst is evidence that AI and cloud infrastructure can lift margins rather than keep free cash flow negative. The biggest risk is that large AI lab losses and high capex persist while regulatory oversight in China and legal scrutiny overseas add more cost and slow product rollouts.
The recent US court ruling that blocked enforcement of a specific Pentagon lobbying restriction on Alibaba is the announcement that matters most here. It does not remove Alibaba from the 1260H list, yet it reduces one operational overhang around doing business with US agencies and could limit distraction from management on that narrow issue.
Set against a broad selloff in Chinese offshore shares and questions over AI spending, that ruling sits alongside a more important test. Investors are still watching whether Alibaba’s RMB 380b three year AI and cloud plan, quick commerce scale up and model subscription revenues progress fast enough to offset regulatory, legal and funding pressures.
Alibaba Group Holding Analyst Assumptions Under SAMR Scrutiny
Alibaba Group Holding's narrative indicates projected revenue of CN¥1,491.6b and projected earnings of CN¥182.9b by 2029, based on analysts assuming 12.6% yearly revenue growth and an earnings increase of about CN¥109.6b from CN¥73.3b today.
Uncover why Alibaba Group Holding's fair value indicates an 85% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Alibaba Group Holding analysts were treating the rapid AI mix shift as the key upside lever, expecting revenue to reach about CN¥1,693.3b and earnings around CN¥420.4b by 2029. With fresh SAMR scrutiny and selling across Chinese tech, you may see those upbeat forecasts rethink risk in very different ways.
Explore 12 other Alibaba Group Holding fair value estimates, including one that suggests as much as 137% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alibaba Group Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alibaba Group Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alibaba Group Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alibaba Group Holding?
If you want to cross check Alibaba Group Holding against other opportunities, use the Simply Wall St Screener to line it up beside businesses with different balance sheet strength, dividend profiles and valuation setups.
- If capital preservation sits high on your list, compare Alibaba against a 30 resilient stocks with low risk scores that screens for resilience and lower overall risk scores.
- If income is a priority, weigh Alibaba beside a 5 dividend fortresses that focuses on companies offering higher yields with the potential for steadier payouts.
- If you prefer to hunt for quality at a discount, set Alibaba next to a 21 high quality undiscovered gems that highlights lesser known businesses with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com