


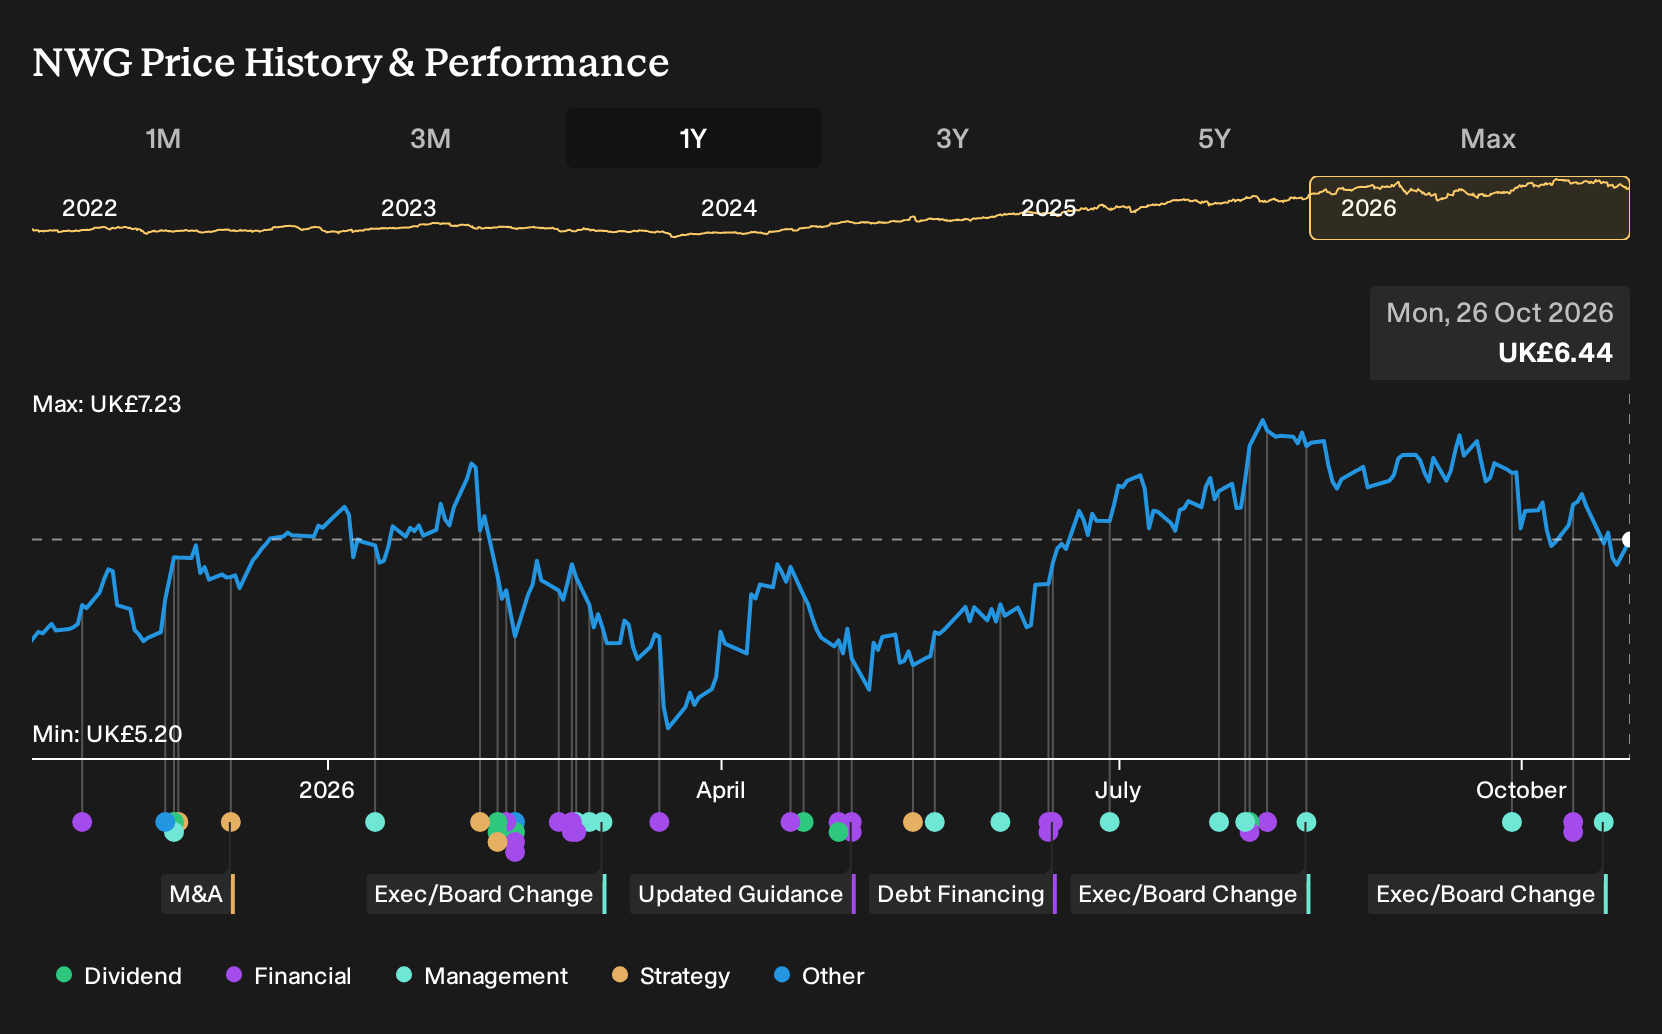
- NatWest Group has reshaped its senior leadership, promoting Isabelle Girolami to CEO of Commercial Institutional from January 2027 and appointing Walid Assaf as CEO of Markets, alongside new roles for Jonathan Peberdy and Robert Begbie.
- The reshuffle concentrates experienced leadership around the Commercial and Institutional division, which already serves over 1.5 million business customers and supports areas such as infrastructure, social housing and high growth ventures.
- We will now look at how NatWest Group's investment narrative could be influenced by Isabelle Girolami taking charge of Commercial Institutional.
Scan how NatWest Group's leadership reshuffle compares with other banks tightening their executive benches by reviewing our curated list of list of solid balance sheet and fundamentals (10 results).
NatWest Group Investment Narrative Recap
To own NatWest Group, you need to be comfortable with a large UK bank leaning into fee income, capital light lending and AI driven efficiency, while net interest margin is guided to flatten in the second half of 2026. The leadership reshuffle concentrates senior experience around Commercial and Institutional banking, but it does not obviously change that near term earnings hinge on cost control and fee resilience.
The biggest operational risk still sits in funding and political pressure. Loan volumes are running ahead of deposits, which could push the loan to deposit ratio higher and increase reliance on wholesale funding. Any rise in sector specific taxation would also matter for shareholder distributions more than for day to day operations.
The Evelyn Partners acquisition remains the key recent announcement to watch against this leadership change. That deal more than doubled assets under management and administration to £131b and is expected to lift group fee income by about 20%, which points to a larger wealth and advice engine sitting alongside the core lending book.
Bringing Isabelle Girolami onto the Group Executive Committee to run Commercial and Institutional places an experienced CIB leader closer to that enlarged fee platform and the infrastructure, social housing and renewables lending book. Execution around integrating Evelyn, scaling AI use and balancing lower margin loans with funding costs will likely matter more to the near term investment case than the job titles themselves.
NatWest Group's current analyst narrative points to £20.7 billion in revenue and £6.9 billion in earnings by 2029, based on forecasts that assume 7.2% yearly revenue growth and an earnings increase of about £0.9 billion from £6.0 billion today.
Uncover why NatWest Group's fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between £7.98 and £13.55 per share, which points to wide disagreement on where NatWest Group should trade. You are weighing those retail views against risks around mortgage margins and funding costs, so it makes sense to explore several alternative viewpoints.
Explore 2 other NatWest Group fair value estimates, including one that suggests as much as 110% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your NatWest Group research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NatWest Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NatWest Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond NatWest Group?
If the NatWest Group story has sharpened your thinking, use that edge to compare it with other opportunities that fit different risk and income profiles.
- For investors who want quality on sale, scan a focused set of companies trading below what their fundamentals might justify using our 10 high quality undervalued stocks.
- If capital preservation comes first for you, filter for businesses with sturdier finances and lower overall risk scores through the 4 resilient stocks with low risk scores.
- For those hunting for potential future favourites before they are widely followed, sort through our 5 high quality undiscovered gems and see which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com