


Pre-market market trends
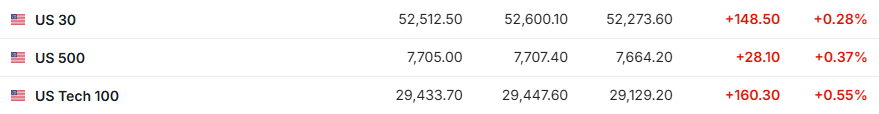
1. On October 27 (Tuesday), the futures of the three major US stock indexes rose sharply before the US stock market. As of press release, Dow futures were up 0.28%, S&P 500 futures were up 0.37%, and NASDAQ futures were up 0.55%.
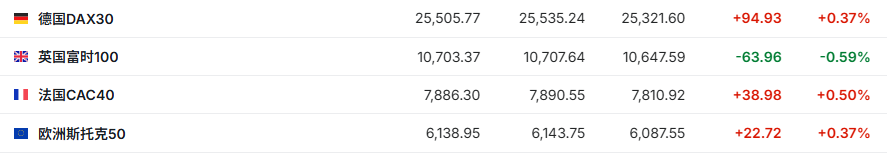
2. As of press release, the German DAX index rose 0.37%, the UK FTSE 100 index fell 0.59%, the French CAC40 index rose 0.50%, and the European Stoxx 50 index rose 0.37%.
3. As of press release, WTI crude oil fell 0.93% to $100.81 per barrel. Brent crude fell 0.82% to $109.83 per barrel.

Market news
The Federal Reserve is expected to remain on hold this week. Dama warned that interest rates may still be raised by 75 to 100 basis points in the future. The Federal Reserve will announce the October interest rate decision on Wednesday EST. The market generally expects the Federal Reserve to keep interest rates unchanged at that time. Michael Gapon, the chief US economist at Morgan Stanley, agreed with the market judgment. He said that the Federal Reserve will stay on hold in October, but the market should still expect policy interest rates to rise in the future. Gabon believes that the Federal Reserve will adopt a wait-and-see attitude, saying it will observe potential trends to evaluate the final direction of the policy. The Federal Reserve may argue that it will judge for itself whether the tightening of the financial environment is sufficient, and then decide the policy path based on this. Whichever path the Federal Reserve takes, there are risks, but it is more likely to take a “more gradual step.” The economist also believes that the Middle East war and rising oil prices will pose risks to inflation, adding that Morgan Stanley is “incorporating some of the effects into next year's inflation forecast,” and the Federal Open Market Committee (FOMC) may also consider this. “I think the economy can withstand a total of 75 to 100 basis points of interest rate hikes without causing huge concerns about yield,” Gapon said. But he warned that if the Federal Reserve needs to raise interest rates six to seven times in total to return to 2023 levels, it may raise some concerns.
Damo shouted that the US stock adjustment is coming to an end! Stick to the S&P target of 8,000 points at the end of the year and target the three major counterattack catalysts. Michael Wilson, chief stock market strategist at Morgan Stanley, judged in the latest research report that the internal adjustments of US stocks that began in June have entered the final stage, but the index may still experience the final round of decline. Wilson said the digestion of three key uncertainties — AI-related capital issues, mid-term election uncertainty, and changes in the Federal Reserve's liquidity — is expected to drive the market bottom and lay a major foundation for the S&P 500 index to rebound to a record point around 8,000 points at the end of the year. Morgan Stanley's composite sentiment index is currently at a neutral level, and third-quarter earnings are expected to increase 27% year over year. Based on this, Wilson maintains his judgment: as these key uncertainties gradually become clear in the coming weeks, the market should present attractive buying opportunities.
Risk appetite has fallen below zero, and the window to increase stock positions has finally opened? Under the semiconductor rebound trend, Goldman Sachs insisted on “overallocating” stock assets. Goldman Sachs's recently released “GOAL Kickstart” research report, which focuses on financial market risk appetite and stock and bond allocation positions, shows that technology-led risk revaluation has significantly reduced market congestion, but credit pressure has not been lifted; profit support, declining valuations, and reduced positions are still sufficient to support Goldman Sachs's financial market strategist team's “moderate pro-risk” (pro-risk) asset allocation position that favors optimistic predictions in the stock and treasury bond markets. The report lowered the risk appetite index compiled exclusively by Goldman Sachs to -0.5, the decline in excess credit returns, the rebound in major treasury bonds, pressure on European assets, and leading quality and defense style, explained in the same cross-asset framework, and cross-validated using valuation, profit correction, capital flow, volatility, liquidity, and recession models. As a result, Goldman Sachs maintained its bullish rating of “overallocated” for 3-month and 12-month term stock assets that it had recently released.
Castle Investment warns: The sell-off in tech stocks is only the first wake-up call, and there is “almost no room for fault tolerance” in AI transactions. Norshad Shah, head of EMEA fixed income sales at Citadel Investments (Citadel), said that the sell-off of technology stocks shows that investors' requirements for whether huge AI spending can eventually generate sufficient profits are getting higher and higher. “Given the current economy and stock market betting on AI transactions in such a high proportion, once other risks begin to emerge, there is almost no room for fault tolerance.” Shah said that tariffs, fiscal incentives, and high energy prices have made the financing and operating costs of AI investments more expensive, and public opposition to data center construction may slow down the progress of the project and drive up costs. He added that the reason the US has been able to absorb these pressures so far is because profits and confidence are still strong. However, the continued decline in AI investment and financing may threaten previously helping the economy cushion higher-cost growth and household wealth.
Morgan Asset Management CIO: The return on US bonds is expected to reach 7%-8% in the next 12 months, making it more valuable in the long run. Bob Michelle, chief investment officer and head of global fixed income at Morgan Asset Management, said that the US bond market is expected to achieve a return of about 7% to 8% over the next 12 months. He also believes that the long-term end of the US Treasury yield curve is the most valuable. Michelle said, “The US Treasury yield curve is close to 5%,” and the front-end yield is slightly below this level. “Therefore, we first expect prices to rise. After that, you can also get holding income”. He sees the long-term end of the US Treasury yield curve as the most valuable. Since this month, the overall price of US Treasury bonds has risen. Factors such as the sell-off of AI-related stocks, the French crisis, and ongoing tension in the Middle East have made US government bonds the preferred safe-haven asset for global investors. The yield on the benchmark 10-year US Treasury has fallen by more than 30 basis points since October, which is likely to end the previous seven-month continuous upward trend.
Individual stock news
Anthropic (ANT.US) officially submitted a prospectus, sprinting to the biggest IPO in history. Anthropic publicly submitted S-1 documents to the SEC on Monday to list on the NASDAQ under the code “ANT.” The company plans to complete its IPO in the week of November 16. The market's valuation of Anthropic is expected to be between 1.5 trillion and 2 trillion US dollars, and the fundraising scale may be as high as 100 billion US dollars or more, which will set the record for the largest IPO in global history. According to S-1 documents, Anthropic achieved revenue of about US$16.3 billion in the first half of this year, exceeding US$4.6 billion in revenue for the full year of 2025. However, at the same time, the company's net loss for the same period reached 80.7 billion US dollars, of which about 72.4 billion US dollars came from accounting expenses for changes in the fair value of instruments such as convertible bonds. Operating cash flow has been corrected to $3.93 billion. Computing power investment is the biggest highlight: computing power spending was nearly 9 billion US dollars in the first half of the year, and future infrastructure spending of 518 billion US dollars has been promised, of which at least 110 billion US dollars has been promised to Amazon and at least 114.5 billion US dollars to Google. Analysts believe the prospectus will be a “teaser” for this week's earnings reports from Google, Microsoft, and Amazon — a shadow of Anthropic demand in the cloud revenue of all three companies.
Memory chip stocks generally rose before the market, and it is rumored that SK Hynix (SKHY.US) plans to launch a record shareholder return. Before the US stock market on Tuesday, as of press release, SK Hynix rose more than 3%, Micron Technology (MU.US) and Seagate (STX.US) rose more than 2%, SanDisk (SNDK.US) rose nearly 2%, and Western Digital (WDC.US) rose more than 1%. According to the news, SK Hynix will announce financial results for the third quarter of 2026 after the US stock market on Tuesday. After months of adjustments to AI-related assets, this financial report will also be the latest window for the market to test the high bandwidth memory (HBM) boom and the continued demand for AI infrastructure. Furthermore, according to reports, SK Hynix plans to simultaneously announce an additional shareholder return plan of 50 trillion to 60 trillion won (about 38 billion to 45 billion US dollars) on the day the third quarter results are released. Combined with the recently completed 40 trillion won share repurchase cancellation, the company's total shareholder return this year will reach 90 trillion to 100 trillion won, the highest in history, about 7 times the size of last year.
Microsoft (MSFT.US) offered a voluntary buyout to approximately 60,000 employees: covering more than a quarter of the global workforce, reducing costs to make room for AI capital expenses. Microsoft has opened a voluntary separation (buyout) program for approximately 60,000 employees. This is the broadest coverage of Microsoft's series of team adjustments since 2026. It also indicates that the company is reducing labor costs and reallocating resources in a more intensive manner against the backdrop of continued increase in investment in artificial intelligence. That number is more than a quarter of its total global workforce. People familiar with the matter revealed that Xbox, Windows, Copilot, finance and other departments are all included in this plan; some positions related to data centers, sales, marketing, cybersecurity, and quantum computing are not within the scope of application. This boundary arrangement shows that while “slimming down,” Microsoft is focusing on protecting teams directly related to AI infrastructure and core growth engines.
Selling chips, leasing, and supporting residual value: Broadcom (AVGO.US) teamed up with the Big Four Wall Street to raise $63 billion to purchase “blood transfusions” for Anthropic chips. Broadcom and the four major Wall Street financial giants, Bank of America, Blackstone Group, Citigroup, and Morgan Stanley, have jointly arranged a financing transaction of about 63 billion US dollars to provide significant financing support for Anthropic, the world's top AI model developer/AI application leader, to purchase AI chips. Participating agencies said in a joint statement that the deal will be carried out through a new special purpose vehicle, where the financial institutions mentioned above will provide promised financing to purchase Broadcom chips and rent them to Anthropic. Broadcom guarantees part of the financing through an arrangement known as “residual value support”. The financing took shape over a few weeks and has been closely watched by Wall Street and Silicon Valley professionals. At a time when opposition to the expansion of data centers and market concerns about future demand, they hope to confirm that investors are still willing to support the construction of AI infrastructure.
Corning (GLW.US) Q3 results and Q4 guidance all exceeded expectations. According to financial reports, Corning's Q3 sales increased 19% year over year to US$5.81 billion, slightly better than market expectations of US$5.028 billion; core earnings per share were US$0.91, better than market expectations of US$0.88, an increase of nearly 36% year over year. Among them, sales in the optical communications business increased 44% year over year to US$2.38 billion. In terms of guidance, Corning expects core earnings per share for the fourth quarter to be $0.96 to $1.00, and the market estimate is $0.93; core sales are 5.2 billion to 5.3 billion US dollars, and the market estimate is 5.2 billion US dollars. As of press release, Corning's US stocks rose more than 2% in the premarket on Tuesday.
Coca Cola (KO.US) Q3 revenue and EPS exceeded expectations and raised full-year profit guidelines. Coca Cola's net revenue for the third quarter increased 7% to US$13.4 billion, better than market expectations of US$12.92 billion. Organic revenue increased 7%, thanks to a 5% increase in unit sales and a 1% positive contribution from price/product mix. Operating profit increased 12% to US$4.5 billion, and operating margin increased from 32.0% to 33.4%. Earnings per share increased 8% to $0.93; comparable earnings per share increased 11% to $0.91, better than market expectations of $0.88. Coca Cola raised its 2026 full-year guideline: organic revenue increased by at least 5%, comparable earnings per share increased by at least 11% (previously expected to increase 9%-10%), and free cash flow to reach at least US$13 billion. CEO Henrique Braun said the company's momentum continues and is confident in the updated guidance.
PayPal (PYPL.US) Q3 revenue fell short of expectations and raised full-year profit guidance. According to financial reports, PayPal's Q3 revenue was 8.6 billion US dollars, up 2.4% year over year, lower than market expectations; non-GAAP earnings per share were 1.45 US dollars, exceeding market expectations. Transaction fees for the quarter were US$4.248 billion, up from US$4,063 billion in the same period last year; transaction and credit losses were US$386 million, which is significantly narrower than US$483 million in the same period last year, indicating an improvement in credit quality. The company raised its full-year adjusted profit guidance, signaling progress in business transformation. PayPal raised its 2026 full-year non-GAAP earnings per share guide to $5.60, higher than market expectations of $5.39; at the same time, it also gave the fourth quarter EPS guidance of $1.43, which was also higher than market expectations of $1.35. As of press release, PayPal's US stocks fell nearly 2% before the market on Tuesday.
AI chip design demand is strong! CDNS.US (CDNS.US)'s Q3 revenue increased 22% year over year, raising full-year results guidance. According to financial reports, Keng Teng Electronics' Q3 revenue reached US$1,633 million, up 22% year on year; non-GAAP adjusted earnings per share were US$2.11, up from US$1.93 in the same period last year. Driven by the demand for AI-driven chip design, all of the company's major businesses achieved double-digit revenue growth. Among them, core electronic design automation (EDA) business revenue increased 20% year over year, mainly due to extensive product portfolio growth and increased customer adoption of memory chips and hyperscale data centers. The company also won 16 new digital design and signing full-process projects during the quarter. Intellectual property (IP) business revenue increased 24% year over year, benefiting from strong demand for interfaces, storage and basic IP products, as well as continued cooperation with large cloud computing companies, semiconductor companies, and foundry foundries. Looking ahead to the full year of 2026, Keng Teng Electronics raised its performance forecast. The annual revenue is expected to be between 6.387 billion and 6.417 billion US dollars, with a median value of about 6.402 billion US dollars according to the corresponding guidelines, an increase of about 21% over the previous year. As of press release, Keng Teng Electronics's US stock rose more than 3% before the market on Tuesday.
United Parcel Service (UPS.US) raised its full-year revenue guidance, signaling strong demand during the holiday season. Financial reports show that United Parcel's Q3 revenue increased 6.7% year over year to US$22.85 billion, higher than market expectations of US$22.29 billion. Almost all of this quarter's revenue growth came from price rather than volume. In terms of earnings, GAAP operating profit was $1.74 billion, and diluted earnings per share were $1.37, down 3.3% and 11.6% year over year, respectively; adjusted diluted earnings of $1.69 per share were higher than market expectations of $1.63. The company raised its fourth quarter and full year guidelines at the same time, for the second consecutive quarter, indicating that the express delivery giant is expected to benefit from high prices and resilient demand during the holiday season. The company expects annual revenue of approximately US$92.6 billion (previous value of US$91.2 billion), adjusted operating profit of approximately US$8.75 billion, adjusted earnings per share of approximately US$7.28, and adjusted free cash flow target raised from approximately US$5.5 billion to approximately US$6.1 billion.
Novartis Pharmaceuticals (NVS.US)'s Q3 revenue increased 4% year over year, and long-end pipeline impairment dragged down net profit. According to financial reports, Novartis Pharmaceuticals' Q3 net sales were US$14.522 billion, up 4% year on year (same increase of 4% at fixed exchange rates), falling short of market expectations; core operating profit of US$6.036 billion, up 11% year on year; core earnings per share of 2.46 US dollars, up 9% year on year, better than market expectations. The profit margin of core operations reached 41.6%, up 2.3 percentage points from the previous year, mainly due to sales growth. IFRS operating profit was US$1,843 million, down 59% year on year, and operating margin was 12.7%, down 19.7 percentage points. The main drag factors include: R&D expenses, which rose to US$5.150 billion (+75%) due to partial impairment of the Del-Desiran IPR&D assets of US$1.9 billion acquired by Avidity; other expenses rose to US$1,575 billion due to increased long-term supply agreement provisions and restructuring expenses. The impairment was due to the fact that the DM1 Indication Phase III HARBOR study announced in September 2026 did not reach the main end point, and the book value of assets fell to 5.5 billion US dollars.
Key economic data and event forecasts
22:00 Beijing time US October Conference Consumer Confidence Index
Performance Forecast
Wednesday morning: Visa (V.US), Seagate (STX.US), Robinhood (HOOD.US), NXP Semiconductors (NXPI.US)
Wednesday pre-market: UBS (UBS.US), Deutsche Bank (DB.US), Nomura (NMR.US), New Oriental (EDU.US), GE Vernova (GEV.US), Amphenol (APH.US), automatic data processing (ADP.US)