


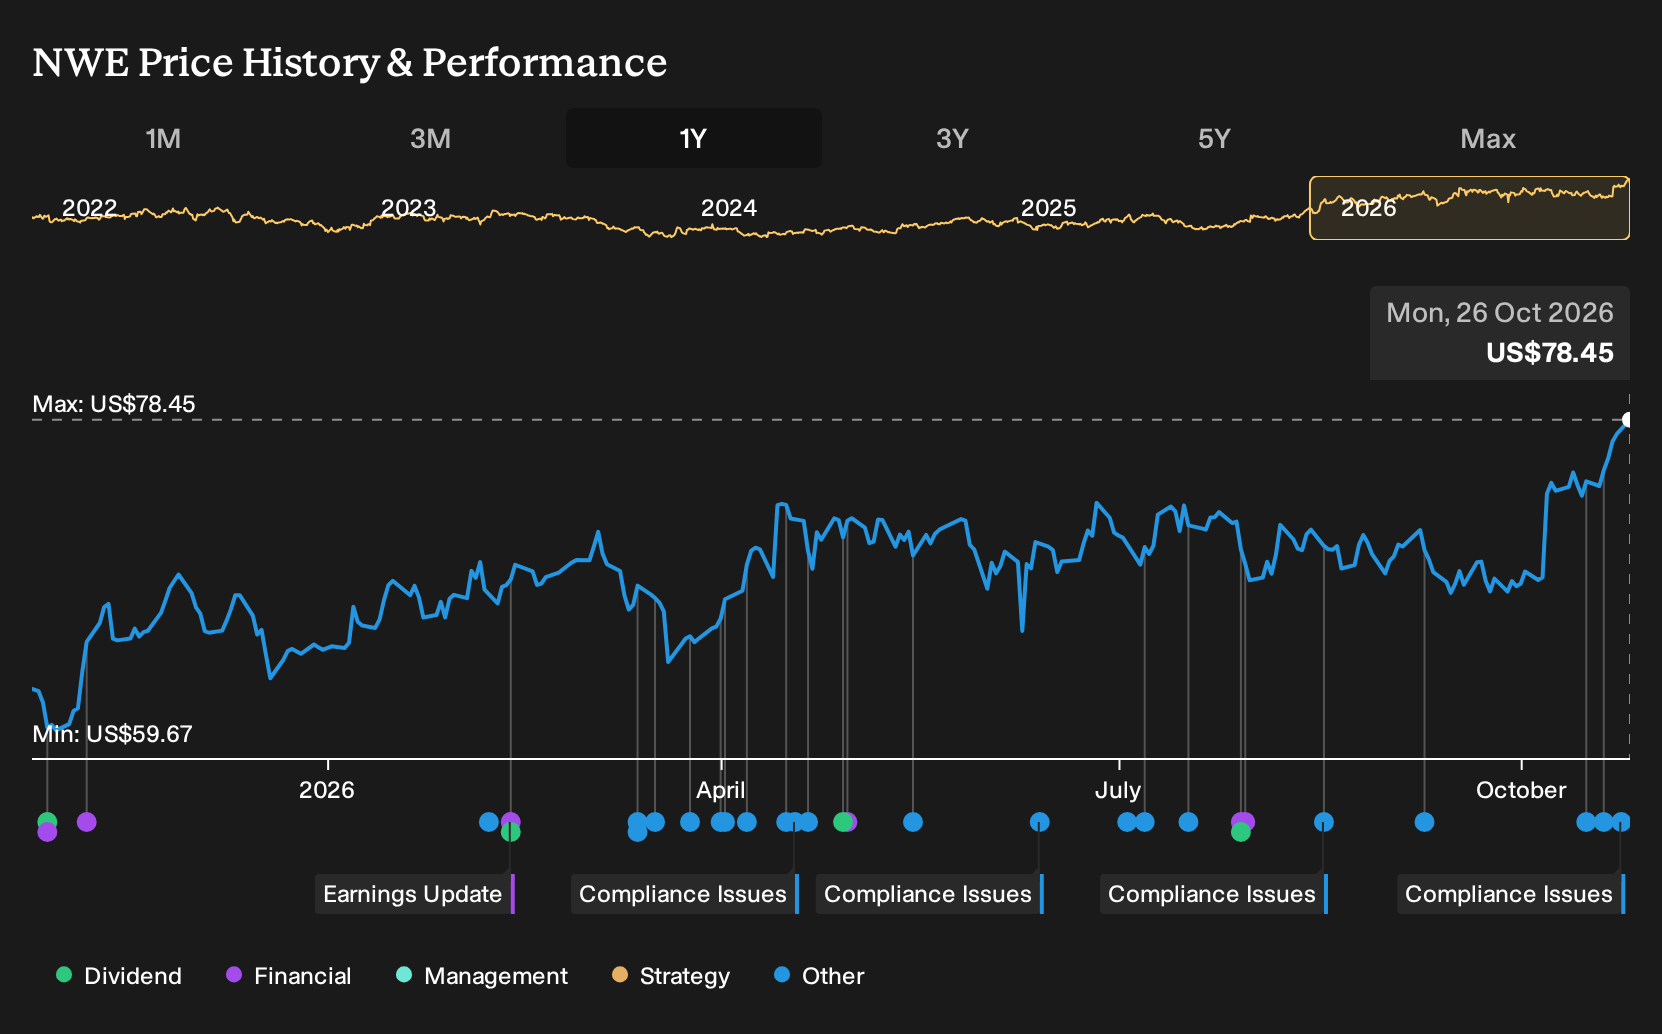
- NorthWestern Energy filed a permit application for a new 131 megawatt power generation station near Aberdeen and reported multiple FERC compliance filings confirming satisfactory dam safety and facility performance at existing hydro projects.
- The mix of a proposed new plant and detailed regulatory reporting highlights how NorthWestern Energy is balancing capacity expansion with disciplined asset monitoring and operational risk control.
- Now the focus shifts to how NorthWestern Energy's investment narrative incorporates a 131 megawatt project proposal alongside steady compliance disclosures.
What Is NorthWestern Energy Group's Investment Narrative?
To own NorthWestern Energy Group you need to be comfortable with a regulated utility that leans on long lived electric and gas infrastructure, steady but modest forecast revenue growth of 4.1% a year, and meaningful capital needs. The Aberdeen 131 megawatt proposal and the ongoing Black Eagle and Thompson Falls work underline that reality. These projects can support reliability and capacity, but they also require funding in a business where earnings growth is expected to trail the broader US market and profit margins recently compressed from 14.8% to 10.1%.
The fresh FERC filings matter less for near term earnings than for confirming dam performance and operational oversight. The brief minimum flow miss at Thompson Falls, plus rehabilitation spending, shows execution risk is real but presently managed with close monitoring and root cause analysis. That all sits on top of a balance sheet where interest costs and a 3.42% dividend strain coverage, which makes new build decisions for NorthWestern Energy Group a central part of the risk reward trade off.
Even so, there is a less comfortable angle to this story that sits in how those future capital commitments intersect with ...
There's only one way to know the right time to buy, sell or hold NorthWestern Energy Group. Head to Simply Wall St's company report for the latest analysis of NorthWestern Energy Group's Fair Value.
Exploring Other Perspectives
Some of the lowest NorthWestern Energy Group analysts were already more optimistic than the baseline, leaning on catalysts like future data center load. They were penciling in revenue of about US$1.9b and earnings of US$276.0 million by 2029. Fresh dam safety findings and the Aberdeen proposal could easily shift those expectations, in either direction.
Explore 2 other NorthWestern Energy Group fair value estimates, including one that suggests as much as 76% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NorthWestern Energy Group research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NorthWestern Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NorthWestern Energy Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond NorthWestern Energy Group?
Once you have a handle on NorthWestern Energy Group, it can help to compare it with other opportunities that share similar traits or offer a different balance of risk and reward. The Simply Wall St Screener gives you quick access to focused shortlists so you can test your thesis against a wider field of companies.
- If capital preservation sits high on your priority list, start with a curated 30 resilient stocks with low risk scores that emphasizes businesses with steadier profiles and fewer red flags on core risk checks.
- If you are hunting for quality at a reasonable price, compare NorthWestern Energy Group with a 29 high quality undervalued stocks that blends solid fundamentals with valuations that may be out of step with underlying strength.
- If predictable income is your anchor, line up regulated utilities beside a 5 dividend fortresses that focuses on higher yielding companies with an eye on payout resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com