


Olympus (TSE:7733) is back in focus after the U.S. rollout of its BF-UCP190F slim diameter endobronchial ultrasound bronchoscope, which extends the group’s reach in lung cancer diagnosis and staging.
Olympus shares trade at ¥1,752.0. Despite a slight 7 day share price gain of 1.27%, the 30 day share price return is down 13.44% and the 1 year total shareholder return declined 9.03%, suggesting recent product news is emerging against a backdrop of fading momentum and lingering concern after the recent FDA Warning Letter.
Scan beyond Olympus and see how other medical technology players are setting up for their next move with our hand picked 22 resilient stocks with low risk scores focused on resilient fundamentals and lower risk profiles.
Olympus now looks like a solid medical devices franchise facing a very different question: Do recent share price declines leave this business attractively valued, or is the market still asking a fair price?
Most Popular Narrative: 16% Undervalued
Against a last close of ¥1,752, the most followed narrative pegs Olympus at a fair value of ¥2,084.62, implying a material upside gap that investors are trying to reconcile with recent regulatory noise and restructuring progress.
The completion of Project Elevate in FY26 and the move to embed quality spending into SG&A, together with the expected sharp drop in large below the line remediation charges, is set up to support the guided 100 plus basis points of annual operating margin expansion from FY27 and a higher level of reported earnings.
See why 2 investors see Olympus as 16% undervalued.
Analysts building this framework are using a 5.65% discount rate and assume Olympus can move its net profit margin toward 11.7% over time while growing revenue at about 4.0% a year, which they judge sufficient to justify that ¥2,084.62 fair value figure.
Those same models also lean on earnings reaching ¥137.0b and a future P/E of 16.8x, which is higher than the current JP Medical Equipment industry level and signals that this storyline depends on Olympus maintaining a strong position in gastrointestinal endoscopy and adjacent devices.
At the current share price the market value of roughly ¥1.86t implies investors are weighing that margin expansion path and cost saving plan against recent issues like the FDA Warning Letter, the sizable one off loss of ¥35.9b and the fact that net margins of 7.5% are some distance from the projected 11.7%.
Result: Fair Value of ¥2,084.62 (UNDERVALUED)
Still, the FDA Warning Letter and ongoing tariff burden in the U.S. could pressure Olympus if remediation drags out or trade costs stay elevated.
Find out about the key risks to this Olympus narrative.
Another View on Olympus Valuation
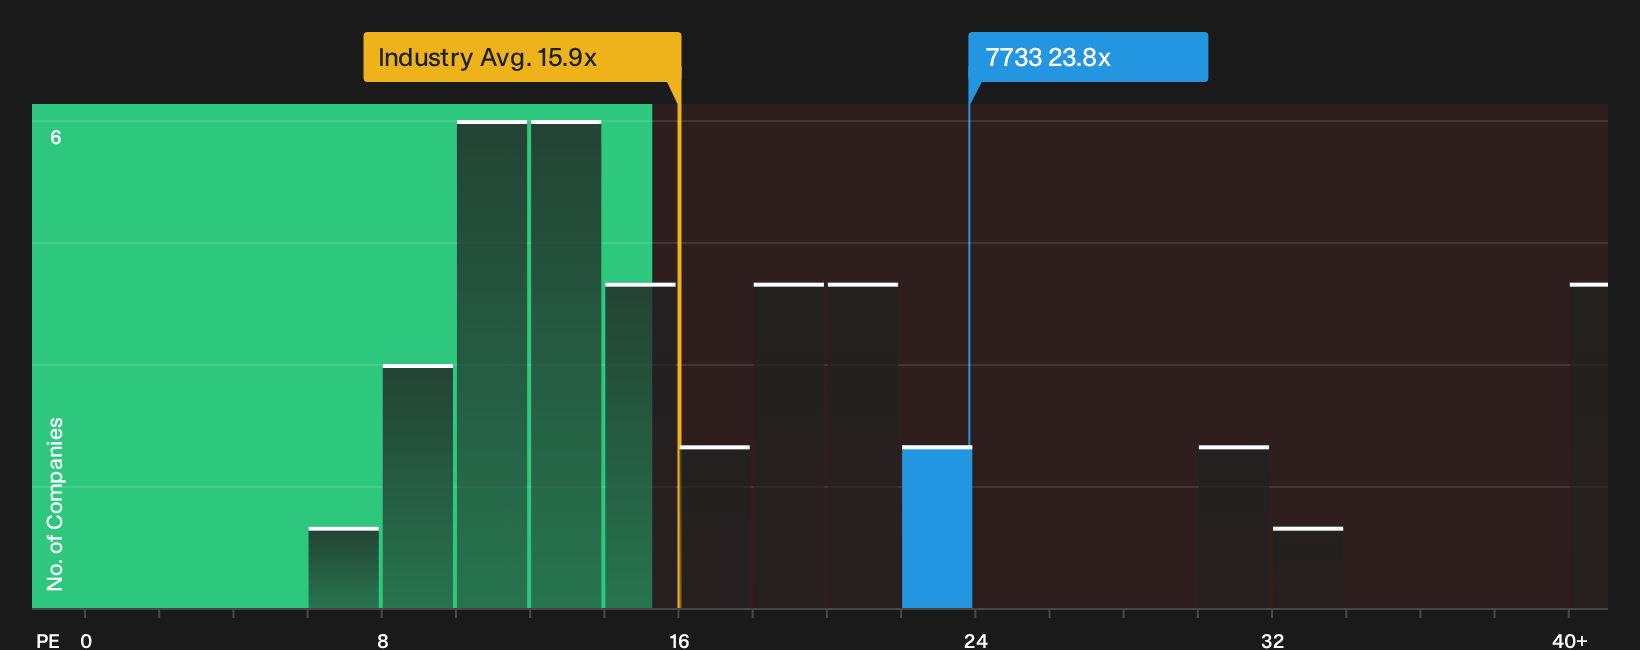
The popular narrative leans on discounted future earnings. A simpler cross check looks at Olympus on its current P/E of 23.8x, which sits above the JP Medical Equipment peer average of 21.4x yet below its fair ratio of 26.6x. That mix points to both upside potential and valuation risk. Which side do you think matters more over your holding period?
To see how that current multiple could move toward the fair ratio, and what that might mean for future returns, take a look at the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
For a visual snapshot of how Olympus compares with its industry on this yardstick, see
Next Steps
Mixed messages in the Olympus story so far. Act while the data is fresh and weigh both sides for yourself by checking the 2 key rewards and 3 important warning signs.
Looking for more Olympus investment ideas?
If Olympus has your attention, do not stop here. You owe it to your portfolio to see what else the market is offering right now.
- Hunt for quality at a discount by scanning companies with strong fundamentals that appear mispriced through our 16 high quality undervalued stocks.
- Lock in potential income streams by reviewing resilient payers featured in the 29 dividend fortresses.
- Strengthen your defence by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com