


Packaged food company Simply Good Foods (NASDAQ:SMPL) reported calendar Q3 2026 (fiscal Q4 2026) results beating Wall Street’s revenue expectations, but revenue fell by 9.7% year on year to $333.3 million. On the other hand, next quarter’s revenue guidance of $270.5 million was less impressive, coming in 9.8% below analysts’ consensus estimates. Its non-GAAP profit of $0.44 per share was 11% above analysts’ consensus estimates.
For more on Simply Good Foods, read our full research report, available free.
Simply Good Foods (SMPL) Q3 CY2026 highlights:
- Revenue $333.3 million vs S&P analysts’ consensus estimates of $327.2 million (9.7% year-on-year decline, 1.9% beat)
- Adjusted EPS $0.44 vs S&P analysts’ consensus estimates of $0.40 (11% beat)
- Adjusted EBITDA $57.49 million vs analysts’ consensus estimates of $53.96 million (17.2% margin, 6.5% beat)
- Revenue guidance $270.5 million at the midpoint for Q4 CY2026, below analysts’ consensus estimates of $299.9 million
- Operating margin 13.8%, up from -3.2% in the same quarter last year
- Free cash flow margin 19.5%, up from 7.4% in the same quarter last year
- Market capitalization $892.6 million
“Fiscal 2026 was a year of decisive action. We recognized that our performance was not where it needed to be and moved quickly to reset the business. We aligned the organization around a focused set of priorities, accelerated work to improve our cost structure, strengthened our financial flexibility, and overhauled our marketing approach across Quest, Atkins, and OWYN. We delivered on the modest financial commitments we made following our second quarter reset, continued to generate significant cash flow despite lower net sales, and completed much of the foundational work necessary to improve the long-term trajectory of the business,” said Joe Scalzo, President and Chief Executive Officer.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years.
With $1.36 billion in revenue over the past 12 months, Simply Good Foods is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
Simply Good Foods’s revenue grew at a sluggish 3% compounded annual growth rate over the last three years. This shows it failed to generate meaningful demand.
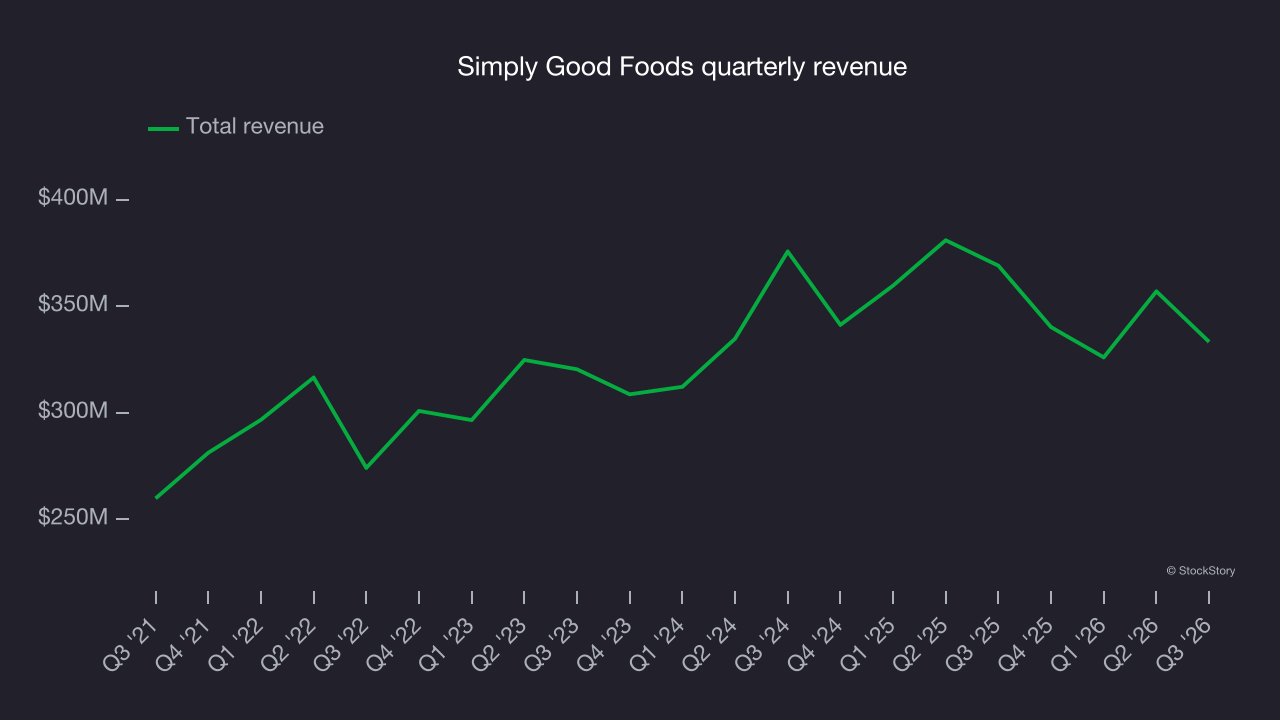
This quarter, Simply Good Foods’s revenue fell by 9.7% year on year to $333.3 million but beat Wall Street’s consensus estimates by 1.9%. Company management is currently guiding for a 20.5% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 9.2% over the next 12 months, according to S&P, a deceleration versus the last three years. This uninspiring projection indicates its products will face some demand challenges.
Free cash flow
Earnings are valuable for assessing company performance, but cash flow matters because accounting profits alone can’t pay the bills.
Simply Good Foods has shown strong cash profitability, giving it an edge over its competitors and the ability to reinvest or return capital to investors. The company’s free cash flow margin averaged 11.2% over the last two years, impressive for a consumer staples business. The divergence from its underwhelming operating margin stems from the add-back of non-cash charges like depreciation and stock-based compensation. GAAP operating profit expenses these line items, but free cash flow does not.
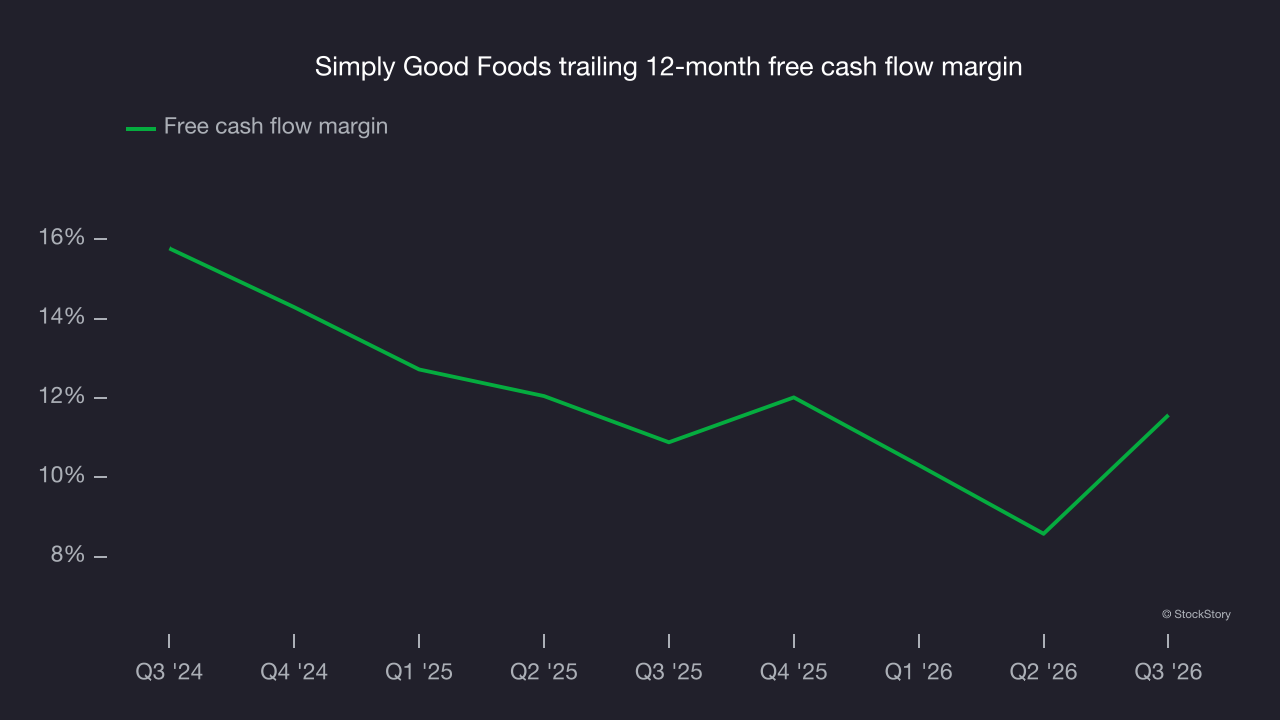
Simply Good Foods’s free cash flow totaled $64.87 million in Q3, equivalent to a 19.5% margin. This was a positive result as its margin was 12.1 percentage points higher than in the same quarter last year, but short-term results warrant caution because investment needs can be seasonal, leading to temporary swings. Long-term trends carry greater meaning.
Key takeaways from Simply Good Foods’s Q3 results
Simply Good Foods delivered a quarter with some key positives: EBITDA beat analysts’ consensus estimates, and revenue topped Wall Street’s consensus. But next-quarter revenue guidance missed expectations, leaving the outlook less positive. The market seemed to be hoping for more, with shares falling 2.9% to $9.80 immediately after the results.
Considering Simply Good Foods at its current price? If you’re making that decision, consider its valuation, business quality and latest earnings. Read more in our full research report here (it’s free).