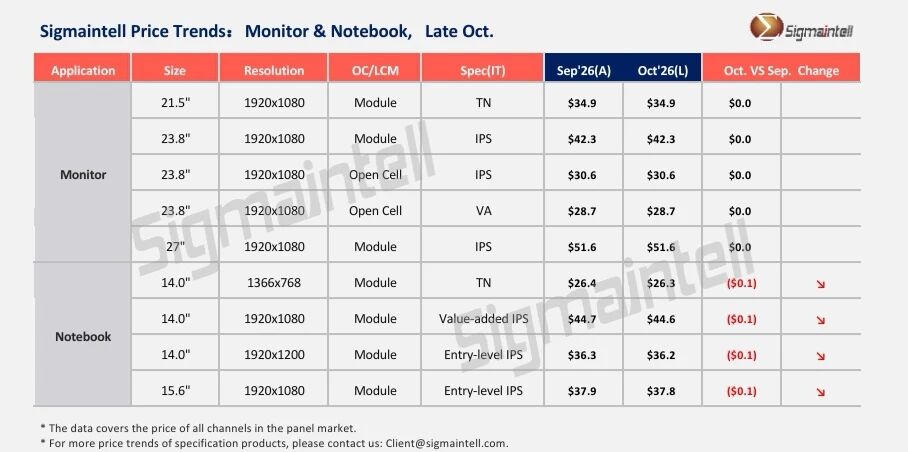
The Zhitong Finance App learned that Qunzhi Consulting published an article stating that in October, the price of mainstream display panels in the world remained flat across the board, and the market continued the price stability game under a weak balance. On the demand side, pre-holiday preparation for “Double Eleven” and “Black Five” has basically ended, and brand inventory gradually increased, while terminal sales recovery was weak and demand momentum was insufficient, and brand procurement was still dominated by inventory removal; on the supply side, panel manufacturers continued to maintain a dynamic production control strategy, and the decline in supply was broadly consistent with the decline in demand, and the display panel market maintained a dynamic balance and slightly relaxed pattern; based on the current upstream material cost trend, panels that improved slightly in the first half of the year were gradually eroded, and the profit attitude of panel manufacturers continued to grow. Heated up; but driven by continued weak demand in the fourth quarter The impetus for price increases is still insufficient.
According to Sigmaintell (Sigmaintell), mainstream specification prices will continue to trend steadily in October, and subsequent bargaining factors between supply and demand will become more complex, affected by multiple factors such as panel material cost trends, the pace of production control in large generations of LCD production lines, and price trends for major applications:
21.5" FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in October;
23.8"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in October;
27"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in October;
Notebook panel
In October, global laptop panel prices will continue to loosen, and prices for mainstream and entry-level models will generally decline. On the demand side, inventory removal has become a common strategy adopted by notebook brands, and the momentum to pull the panel is insufficient; however, when GPUs are out of stock, the retail price of superimposed machines soared, which also had a negative impact on promotional demand in the fourth quarter. On the supply side, panel component costs are rising and will continue to drive up panel BOM costs in the fourth quarter of 2026. Looking at both sides of supply and demand, although cost pressure is still present, the sharp decline in demand contradicts the aggressive shipping targets of panel manufacturers. Sigmaintell (Sigmaintell) predicts that the typical price of notebook panels will continue to decline in October, and the performance of various specifications will diverge. The panel price performance is as follows:
Low-end HD TN: October price reduced by $0.1 month-on-month;
IPS FHD&FHD+ products: On October 16:9, mainstream specifications were reduced by $0.1 month-on-month; at 16:10, the price of entry-level specifications was reduced by $0.1 to 0.2; the price of mid-range and high-end panels continued to diverge.