


USAA alliance puts LegalZoom.com in front of a large military audience
LegalZoom.com (LZ) just announced a new partnership with USAA that gives roughly 14 million members access to discounted online legal services, including estate planning and business formation tools.
The USAA alliance lands at a time when LegalZoom.com’s share price has shown a 25.62% 1 month share price return and 12.06% 7 day share price return, yet the 1 year total shareholder return is down 31.05% and the 5 year total shareholder return is down 73.73%. This signals short term momentum against a weaker long term record as investors reassess growth potential and risk around new partnerships like this one.
Spot 21 high quality undiscovered gems that, like LegalZoom.com, aim to tap under-served niches with scalable, subscription-style services for consumers and small businesses.LegalZoom.com’s sharp rebound sits against years of weak shareholder returns, so the jump around the USAA deal forces a simple test: Is price finally catching up to the business, or has sentiment just swung too far?
Most Popular Narrative: 7% Undervalued
LegalZoom.com closed at $7.06 against a widely followed fair value anchor of $7.60, which frames the recent rebound as only partly pricing in the longer term subscription and AI story.
Enhanced automation and AI deployment across LegalZoom.com, including 55% faster trademark searches, 30% faster patent drafting, and AI resolving about 40% of customer care chats, is reducing unit costs and has already coincided with gross margin of 71% and adjusted EBITDA margin of 22% in Q2 2026. This is described as positioning the company for further EBITDA margin expansion.
See why 11 investors see LegalZoom.com as 7% undervalued.
Result: Fair Value of $7.60 (UNDERVALUED)
Still, the LegalZoom.com story can crack if AI driven search cuts formation volumes further or if reduced 2026 revenue guidance keeps investor confidence under pressure.
Find out about the key risks to this LegalZoom.com narrative.
Another View: LegalZoom.com On Earnings Multiples
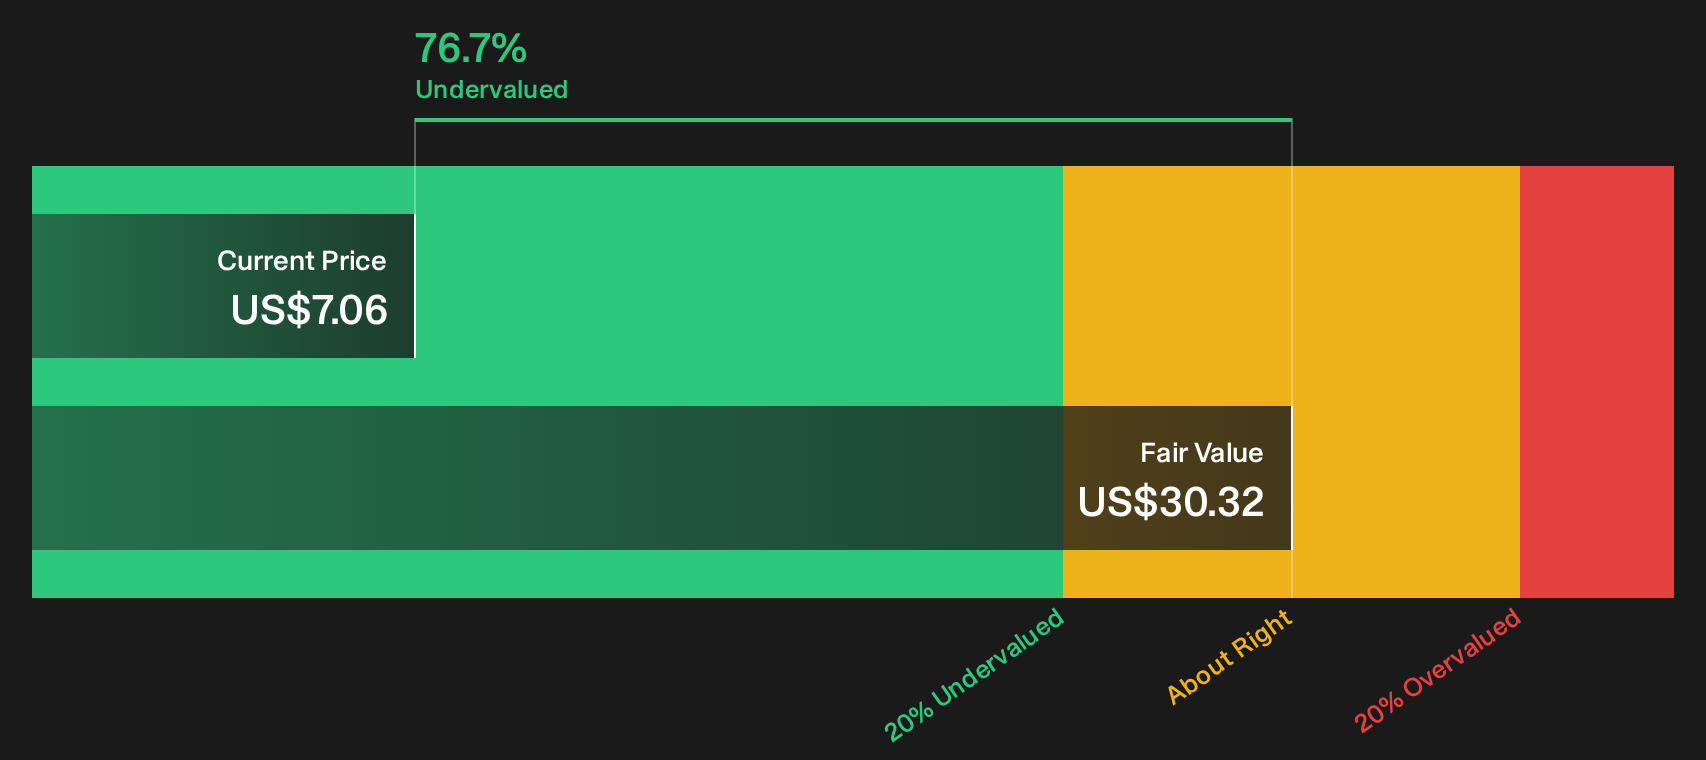
There is a catch. While the SWS DCF model points to LegalZoom.com trading well below an estimated future cash flow value of $30.32, the earnings multiples tell a very different story, with the stock on a P/E of 71.7x versus an industry average of 23.1x and a fair ratio estimate of 33.5x. That gap signals real valuation risk if sentiment cools before earnings catch up, so which yardstick do you give more weight to?
For a deeper look at how that cash flow view is built, and how sensitive it is to the assumptions that go into it, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on LegalZoom.com so far. If you want a clear stance, move quickly through the numbers, the AI story, and the partnership details, then weigh the 2 key rewards and 3 important warning signs for yourself.
Looking for more investment ideas beyond LegalZoom.com?
If LegalZoom.com has you rethinking what belongs in your portfolio, do not stop here. Fresh opportunities often sit just one smart search away.
- Target potential mispricing by scanning a curated pool of high quality companies with strong fundamentals through the 29 high quality undervalued stocks.
- Build resilience into your portfolio by filtering for companies with clean finances and sturdy fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Spot overlooked potential by zeroing in on financially sound businesses that have yet to gain broad attention through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com