


Fifth Third Bancorp (FITB) just posted third quarter 2026 results that combined higher net interest income and net income with sharply lower net charge offs, a mix many bank investors watch closely.
Those third quarter credit gains come as Fifth Third Bancorp’s share price has risen 11.3% year to date to about $53.10, even though the stock is down 8.1% over the past 90 days. Meanwhile, a 1 year total shareholder return of 29.3% and a very large 3 year total shareholder return above 7x suggest that longer term momentum has been much stronger than the recent pullback implies.
Scan how Fifth Third Bancorp’s credit improvement compares with peers by reviewing banks on the 30 resilient stocks with low risk scores.So is Fifth Third Bancorp’s recent pullback just sentiment cooling after a huge multi year run, or has the business moved further than the share price suggests?
Most Popular Narrative: 14% Undervalued
Against a last close of $53.10, the most followed narrative pegs Fifth Third Bancorp’s fair value at $61.54, which frames the recent pullback as a gap between execution and what the models imply.
Expansion and densification in fast growing Southeast and Southwest markets is being extended through the Comerica footprint and an accelerated de novo program, with the recent outperformance of de novo deposit goals and sizeable Southwest consumer deposit inflows supporting potential future revenue and market share growth.
See why 23 investors see Fifth Third Bancorp as 14% undervalued.
Result: Fair Value of $61.54 (UNDERVALUED)
Still, the bullish Fifth Third Bancorp story can unravel if deposit competition keeps pushing funding costs higher or if Comerica integration issues trigger lasting customer churn.
Find out about the key risks to this Fifth Third Bancorp narrative.
Another View: Multiples Point To A Richer Price Tag
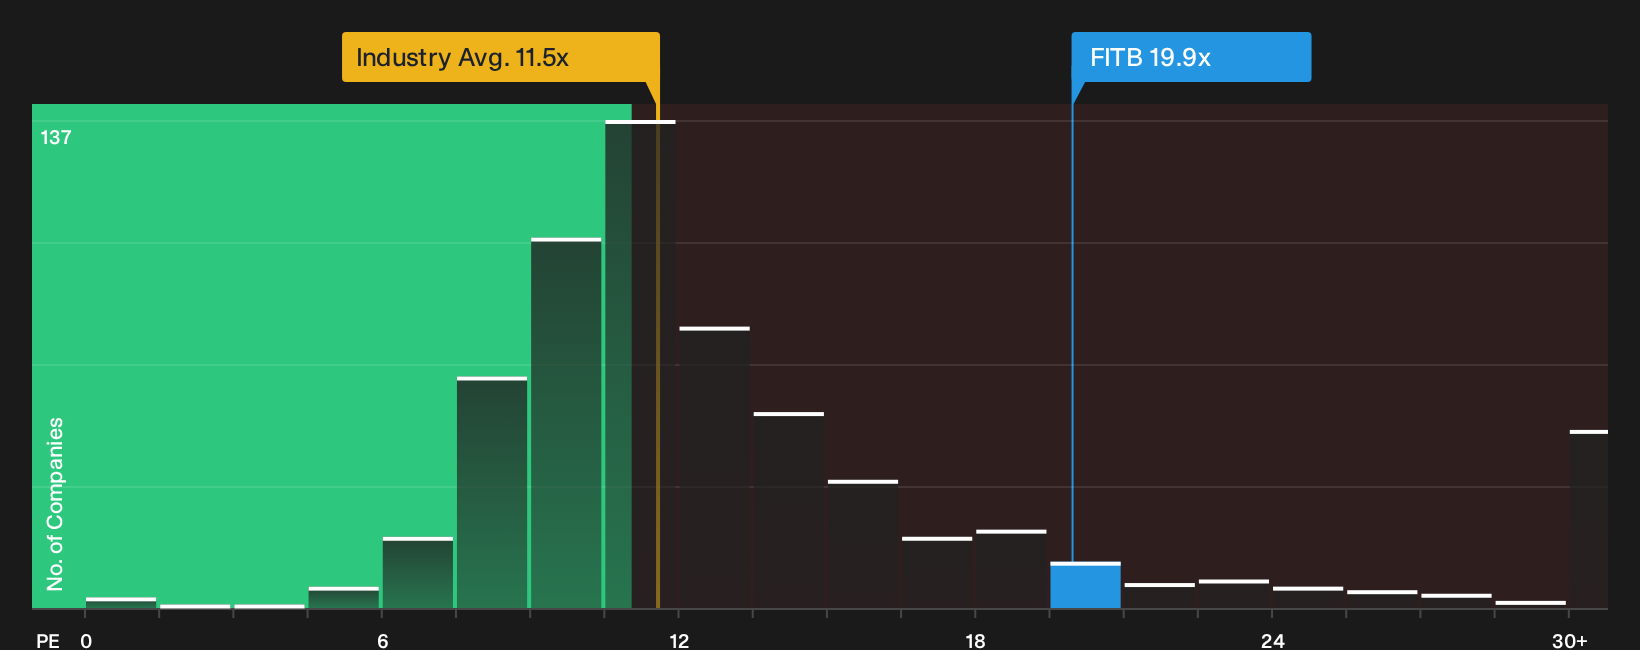
Looking at Fifth Third Bancorp through a simple P/E lens changes the picture. The shares trade on roughly 19.9x earnings, compared with 12.2x for peers and 11.5x for the wider US Banks group, while the fair ratio is lower at 16.8x.
This gap suggests investors are already paying a premium for Fifth Third Bancorp’s story, even though the earlier models frame the stock as undervalued. The key question is whether that premium is seen as justified upside or as additional valuation risk if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Fifth Third Bancorp so far. If you want to move past headlines and sentiment, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fifth Third Bancorp?
If you want a wider watchlist with clear themes, use targeted screeners that surface stocks matching your risk tolerance, income needs, and value focus in minutes.
- Target income first and shortlist companies with strong yields and resilience through the 5 dividend fortresses.
- Hunt for potential mispricings by focusing on quality businesses flagged in the 29 high quality undervalued stocks.
- Strengthen capital preservation by filtering for financially robust candidates through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com