


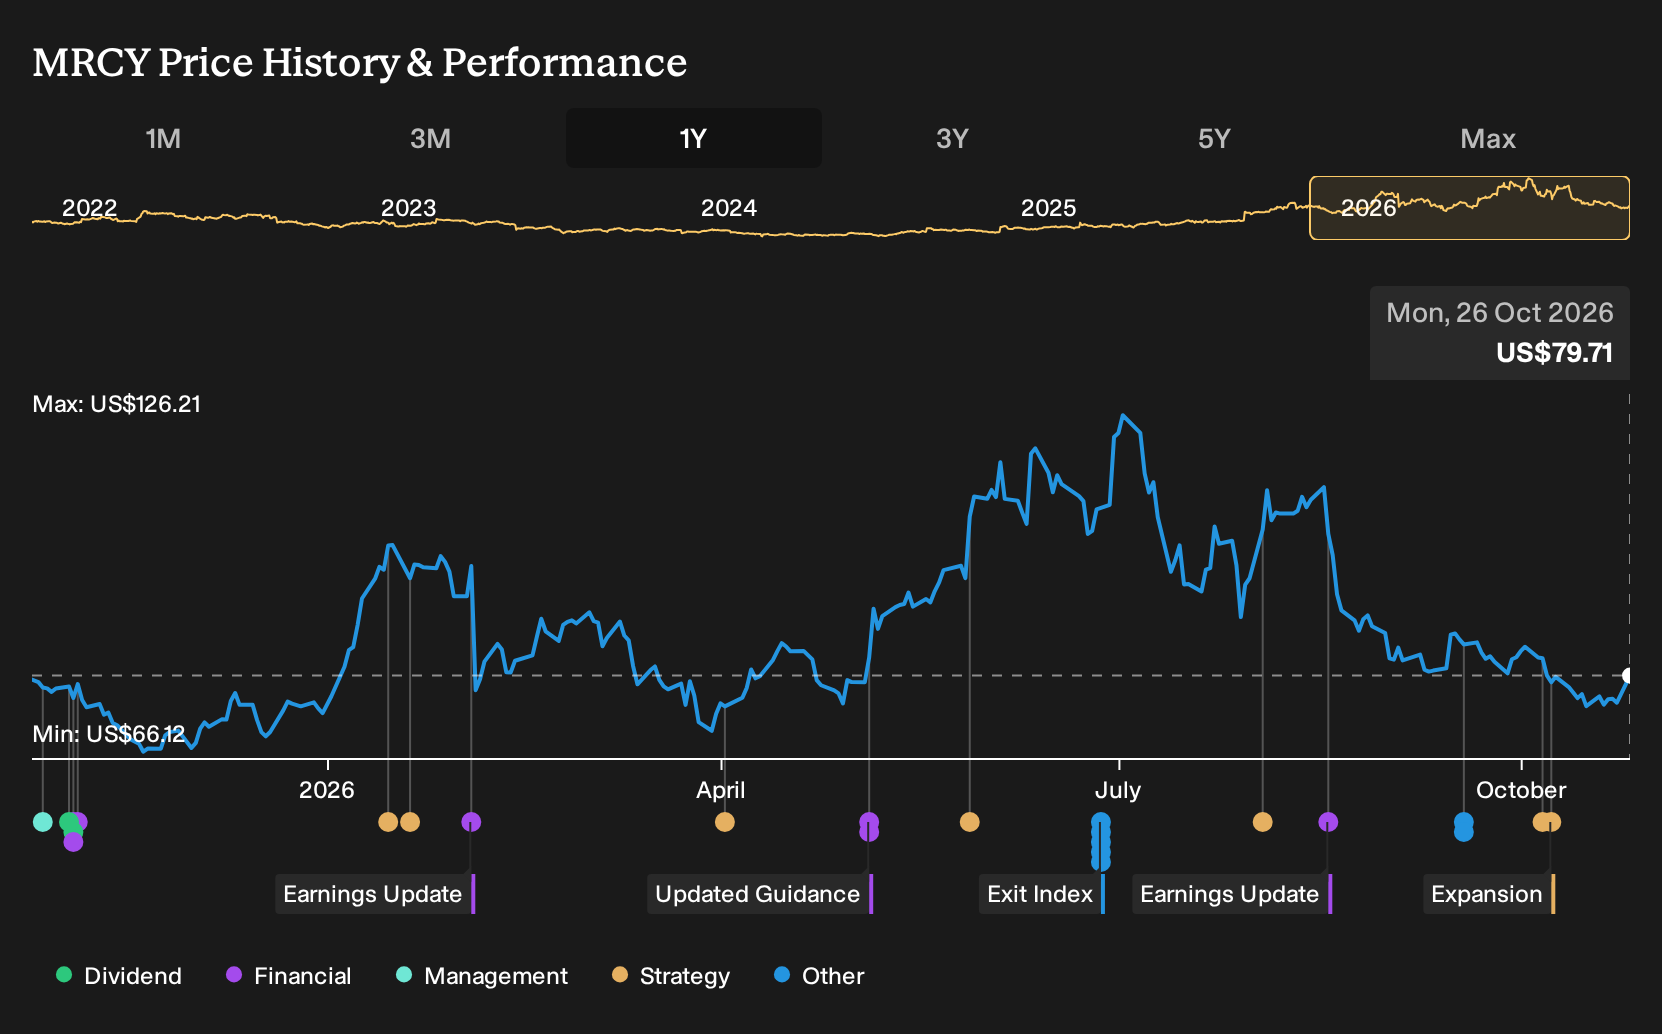
- Piper Sandler recently highlighted Mercury Systems as one of its preferred defense technology companies ahead of earnings, pointing to strong contract awards, roughly 93% bookings growth last quarter, and a backlog that management is working through despite lower legacy margins.
- The focus on profitability improvement, as Mercury Systems executes older, lower-margin work alongside newer awards, offers a clear window into how backlog quality, not just size, may influence future financial outcomes.
- We will now look at how Mercury Systems' investment narrative could be shaped by Piper Sandler's emphasis on its strong recent bookings.
Scan how Mercury Systems fits into the broader defense-tech story by lining it up against 30 resilient stocks with low risk scores, which is built to handle contract cycles and funding uncertainty.
Mercury Systems Investment Narrative Recap
To own Mercury Systems, you need to believe the defense electronics demand story holds up and that management can convert its contract wins into healthier earnings. The near term hinges on how efficiently the firm turns that roughly 93% bookings jump into revenue and margins while still working through older, weaker contracts that weigh on profitability.
The immediate swing factor is execution on the backlog transition, from legacy work toward newer awards that are expected to be higher quality. The biggest risk is that capacity tied to low margin programs and prior delivery pull forwards keeps crimping revenue growth and net income, even as bookings headlines look strong.
Recent commentary on Mercury Systems from Piper Sandler leans heavily on those strong contract awards and the sharp bookings increase. That matters because the core operational debate right now is not whether orders exist, but how quickly and cleanly those orders convert into production, cash, and a return to consistent profitability.
Interest rate moves and uncertainty over U.S. defense spending are also part of the backdrop the brokerage flagged. For you, the link is simple: slower budget decisions or higher funding costs could stretch program timelines, which would test Mercury’s ability to keep improving margins, work down legacy backlog, and hit the catalysts analysts are focused on.
Mercury Systems is being modeled on a path where revenues reach about $1.3b and earnings come to roughly $115.7 million by 2029. That profile lines up with analyst assumptions of 10.1% yearly revenue growth and an earnings swing of about $145.4 million from a loss of $29.7 million today to the 2029 forecast level.
Uncover why Mercury Systems' fair value indicates a 38% potential upside to its current price that could narrow quickly as the backlog story plays out.
Exploring Other Perspectives
One alternative view on Mercury Systems puts cash generation front and center. The most cautious analysts worry that free cash flow could lag even with strong orders. Before this Piper Sandler news, they were penciling in revenue of about US$1.3b by 2029 but only US$83.2 million of earnings. That is a far more muted profitability story than the consensus path of US$115.7 million. Use that gap as a reminder that forecasts differ widely and that this latest bookings update may prompt some models to shift in very different directions.
Explore 4 other Mercury Systems fair value estimates, including one that suggests as much as 44% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mercury Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mercury Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury Systems' overall financial health at a glance.
Looking for more investment ideas beyond Mercury Systems?
If the Mercury Systems story has sharpened your thinking but you want a wider bench of candidates, the Simply Wall St Screener can help you line up other stocks against the same kind of risk, balance sheet, and income filters that matter here.
- Prefer resilient businesses that aim to keep downside risk contained? Start with a 30 resilient stocks with low risk scores and see which listings match that profile.
- If income is your priority, scan a curated set of 5 dividend fortresses that combine meaningful yields with an eye on durability.
- For investors hunting for underfollowed opportunities with solid fundamentals, browse a 21 high quality undiscovered gems that might deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com