


Par Pacific Holdings (PARR) has drawn fresh attention after recently closing at US$83.17. The move comes with the energy operator carrying a US$3.87b market value and mixed annual revenue and net income trends.
The sharp 7.8% one-day share price return at Par Pacific Holdings sits on top of a strong run, with a 132.19% year-to-date share price gain and a five-year total shareholder return of 415.94%. This points to momentum that investors will likely compare closely with the company’s current earnings power and valuation.
Compare Par Pacific Holdings' run with a curated group of US-listed refiners and fuel retailers in the 29 high quality undervalued stocks that also pair momentum with underlying fundamentals.
The jump in Par Pacific Holdings now collides with softer recent revenue and net income trends. Is this latest surge a read on business strength, or a reset in investor sentiment that the valuation no longer ignores?
Most Popular Narrative: 10.8% Undervalued
Par Pacific Holdings is now trading at $83.17 against a widely followed fair value estimate of $93.29, so the key question for investors is whether current earnings power and future assumptions justify that gap.
The numbers and recent share repurchases imply the market is valuing Par Pacific as fairly valued with a bearish tilt, with current earnings, balance sheet strength, and finite tax benefits already largely reflected in the share price.
See why 21 investors see Par Pacific Holdings as 11% undervalued.
Result: Fair Value of $93.29 (UNDERVALUED)
Still, Par Pacific Holdings depends on older refinery assets and regional hubs, where outages, regulation or weaker local demand could quickly challenge the current valuation story.
Find out about the key risks to this Par Pacific Holdings narrative.
Another View: Cash Flows Point in a Different Direction
Par Pacific Holdings looks inexpensive on earnings, with a P/E of 4.9x, yet the SWS DCF model paints a less generous picture. On that framework, the stock at $83.17 sits well above an estimated future cash flow value of $52.95, which implies overvaluation instead of a margin of safety. Which lens do you trust more: cheap earnings or cautious cash flow math?
For readers who want to see how this cash flow view is built line by line, the SWS DCF model is laid out in full detail in the valuation report, including every major input and assumption Look into how the SWS DCF model arrives at its fair value.
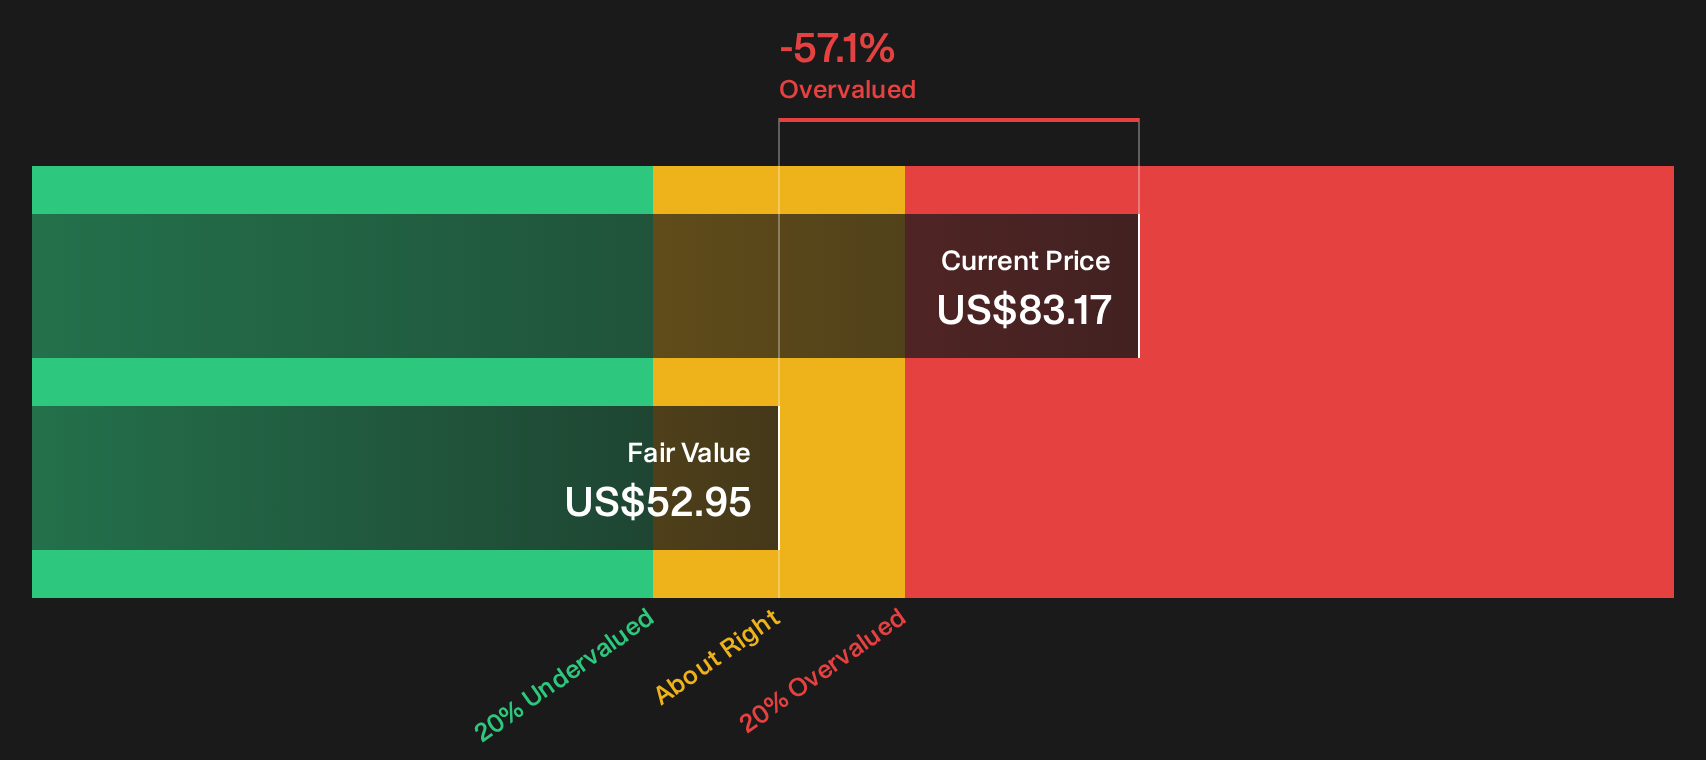
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Par Pacific Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Par Pacific Holdings can be useful if you are willing to scrutinize the data yourself and move before sentiment swings again, so weigh the upside and downside by checking the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Par Pacific Holdings?
If Par Pacific Holdings already sits on your watchlist, broaden your opportunity set with other potential ideas that line up with your risk and return preferences.
- Target higher upside potential by scanning a curated pool of strong fundamentals and valuation support through the 21 high quality undiscovered gems.
- Prioritise resilience by reviewing companies with healthier financing, liquidity, and debt metrics using the list of solid balance sheet and fundamentals (24 results).
- Focus on income plus durability by zeroing in on payouts that aim for both yield and staying power in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com