


Marketplaces have connected buyers and sellers for centuries, whether along bustling town streets or inside sprawling suburban malls. Their appeal lies in offering shoppers convenience and choice while allowing merchants to benefit from shared foot traffic. Now, online marketplaces have taken this model further.
Few companies illustrate this evolution better than eBay (EBAY). Once known primarily as the Internet’s pioneering auction site, eBay has grown into one of the world’s largest online marketplaces. After surpassing expectations for both revenue and earnings in its latest quarter, the company is set to report its Q3 FY2026 results on Wednesday, Oct. 28, after markets close.
Much of the momentum is expected to come from established strengths, particularly collectibles, Motors, fashion, and refurbished goods. Meanwhile, eBay’s expanding consumer-to-consumer (C2C) and recommerce businesses are expected to have gained further traction following its acquisition of Depop in July.
Beyond these categories, eBay’s growing advertising business and expanding shipping and financial services capabilities are expected to support Q3 revenue. However, expansion brings added costs. The Depop acquisition and increased investment in strategic growth initiatives might weigh on profitability, leaving investors to watch whether eBay can sustain its momentum while protecting its bottom line.
About eBay Stock
Based in San Jose, California, eBay operates a global e-commerce business that connects buyers and sellers through its online marketplaces. Its website, eBay.com, mobile applications, and other businesses allow users to list, purchase, sell, and pay for an extensive range of products, making the platform a meeting point for shoppers and merchants worldwide.
With a market cap of nearly $52.8 billion, eBay’s shares have gained 22% over the past 52 weeks and climbed 36.2% in 2026. The rally has continued even in the short term, with the stock advancing another 9.9% over the past month.
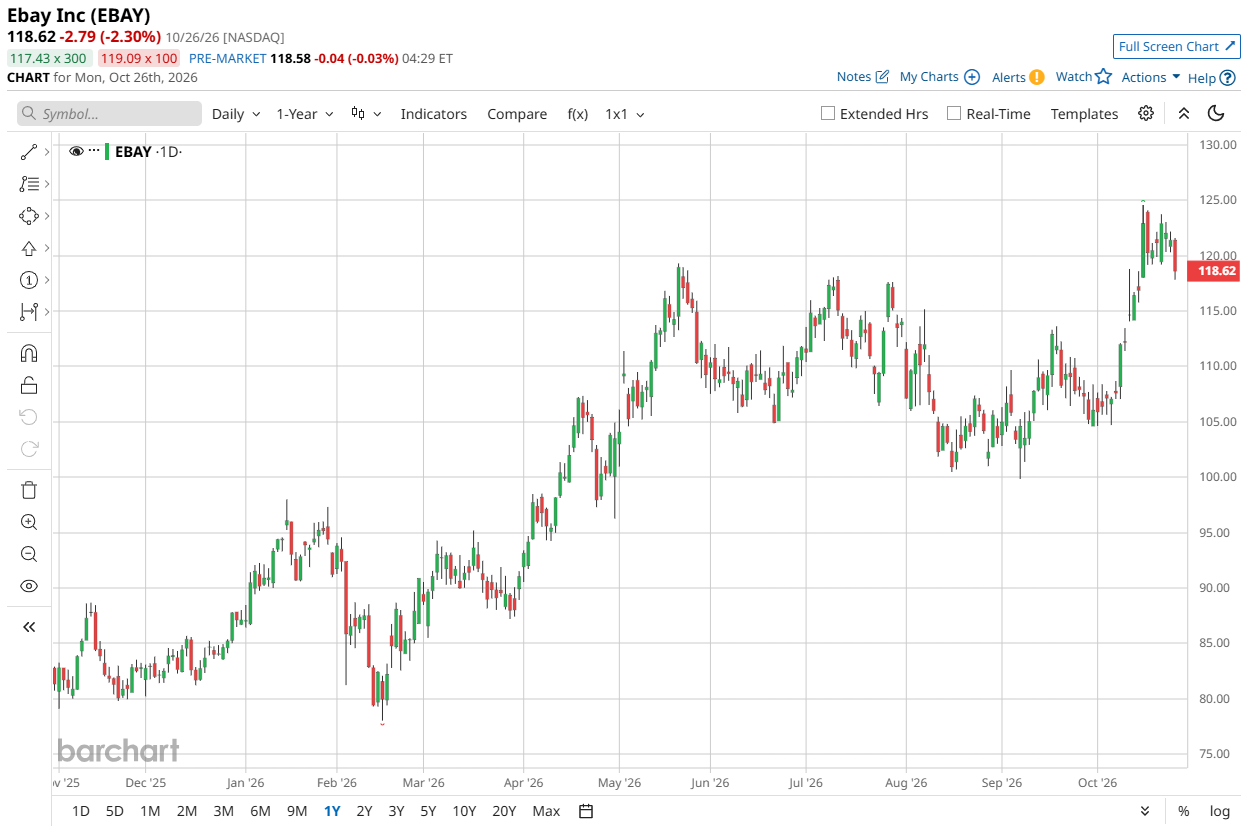
On the valuation front, EBAY stock is currently trading at 19.32 times forward adjusted earnings and 4.21 times sales. Both multiples stand above the respective industry averages and eBay’s own five-year average valuations, suggesting a premium.
eBay has also increased its dividend for six consecutive years and currently distributes $1.24 per share annually, translating into a yield of 1.05%. Its most recent dividend of $0.31 per share is scheduled to be paid on Monday, Nov. 9 to shareholders of record as of Monday, Aug. 28.
Surpasses Q2 Earnings
On Aug. 5, eBay’s shares gained 1.4% as the company released its Q2 FY2026 results. Revenue climbed 14.8% year-over-year (YoY) to $3.13 billion, exceeding analyst estimates of $3.02 billion. Non-GAAP EPS also grew 17.6% from the year-ago value to $1.60, surpassing the Street’s forecast of $1.51.
The strength extended beyond revenue and earnings. Gross merchandise volume (GMV) rose 14.8% from the prior year’s quarter to $22.4 billion, while non-GAAP operating income reached $893 million. Moreover, non-GAAP net income from continuing operations increased 13.6% YoY to $727 million.
These results highlighted broad-based marketplace momentum, supported by continued outperformance in the United States and improving trends across international markets. Behind this performance is eBay’s continued focus on its key strategic priorities, including focused categories, its consumer-to-consumer (C2C) business, and recommerce, which covers the sale of pre-owned and refurbished items.
Emerging growth opportunities and expanding platform capabilities, including eBay Live, vehicles, and shipping, provided additional support, helping the company build on its core marketplace strengths.
eBay also ended the quarter with a stronger cash position. Cash and cash equivalents totaled $2.3 billion, up from $1.9 billion as of Dec. 31, 2025. Free cash flow came in at $326 million, compared with negative $441 million in the year-ago period. Looking ahead, management expects Q3 revenue to range from $3.07 billion to $3.12 billion, with non-GAAP EPS projected between $1.36 and $1.42.
Analysts, however, have a more measured outlook for the upcoming quarter, forecasting Q3 FY2026 EPS of $1.11, a marginal increase YoY. For full FY2026, EPS is expected to climb 17.2% from the previous year to $4.90, while for FY2027, analysts project a 9.4% increase to $5.36.
What Do Analysts Expect for EBAY Stock?
Recent analyst moves suggest that Wall Street sees more room for eBay to grow. Nathan Feather of Morgan Stanley has reiterated a “Buy” rating and raised his price target from $127 to $132, signaling greater confidence in eBay’s growth prospects as marketplace improvements, stronger consumer demand, and better profitability potentially bolster its performance.
Mike McGovern of Bank of America Securities also raised his price target from $123 to $129 but stopped short of turning bullish, maintaining a “Hold” rating.
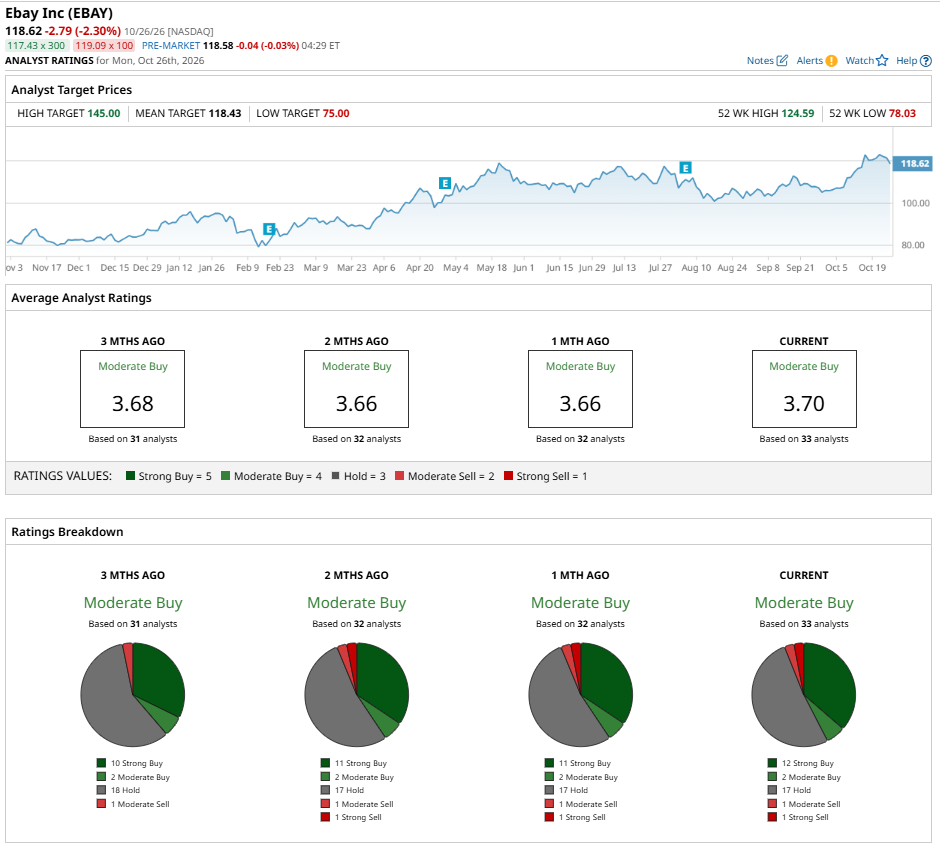
Across Wall Street, the consensus verdict is a “Moderate Buy.” Of the 33 analysts covering EBAY stock, 12 rate the stock a “Strong Buy,” two recommend a “Moderate Buy,” 17 maintain a “Hold,” one assigns a “Moderate Sell,” and one recommends a “Strong Sell.”
The stock’s recent rally, however, has already carried it above the average price target of $118.43. However, the Street-high target of $145 suggests further gains of 22.2% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.