


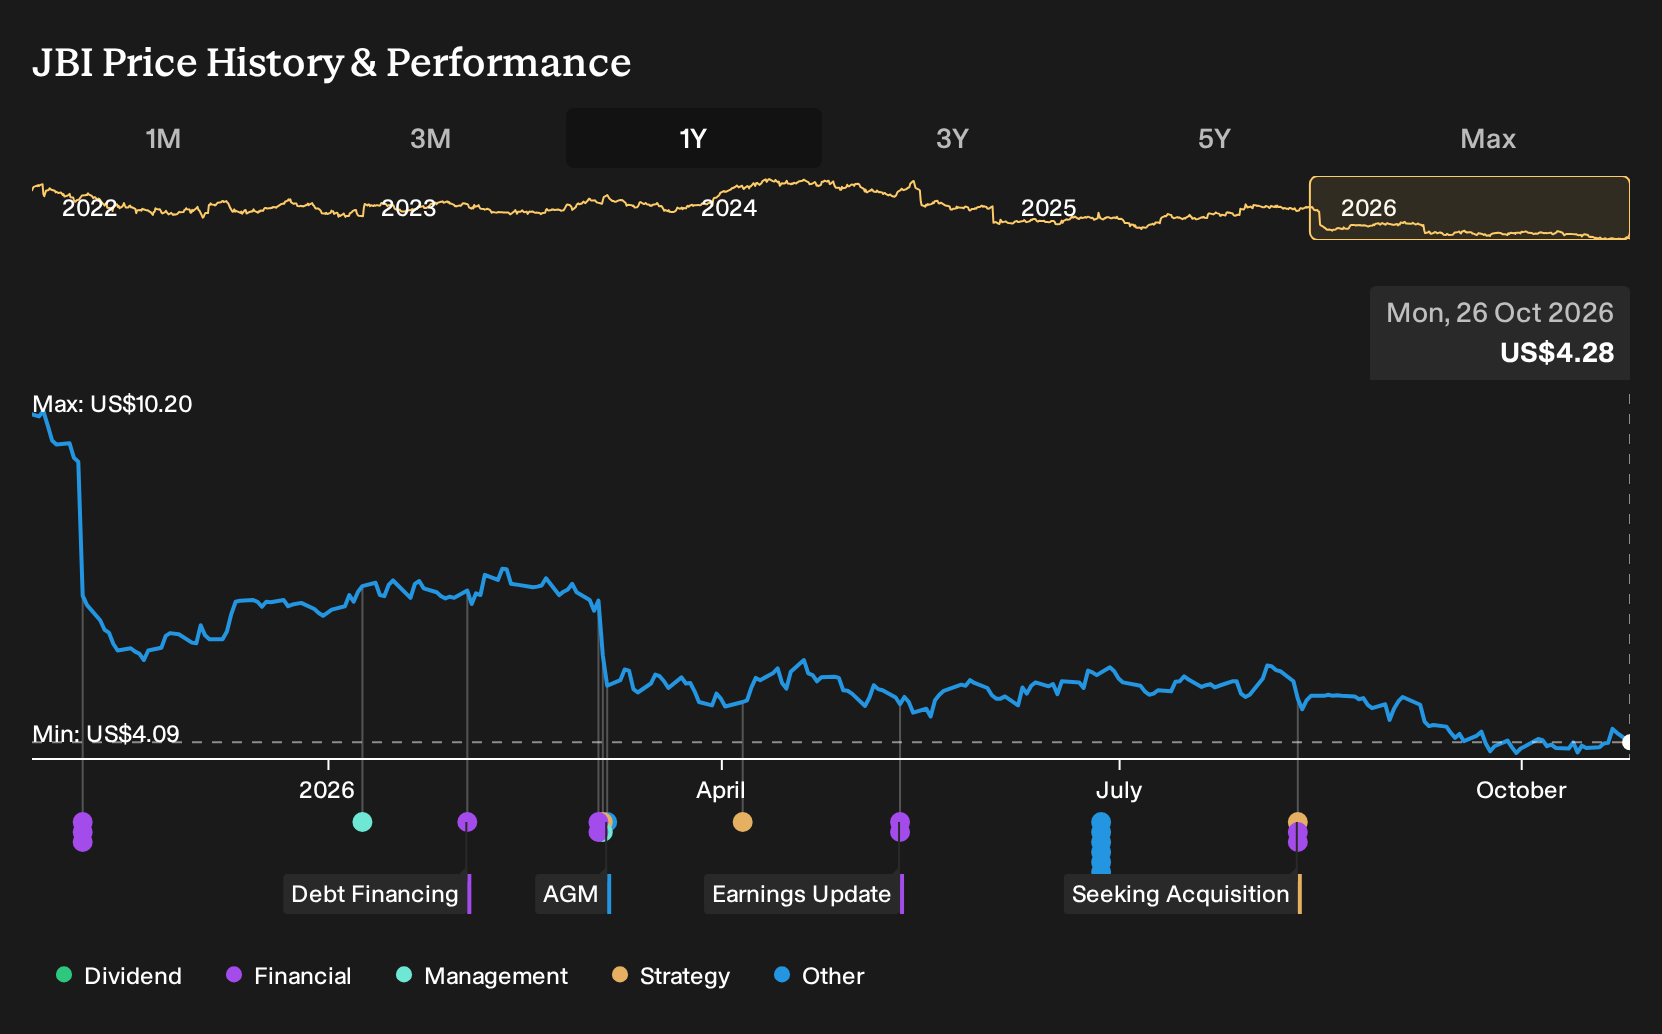
If you had backed the bullish story on urban densification, smart access control and R3 upgrades at Janus International Group, the result would have been brutal. Holding Janus International Group over the past year would have meant a 57.6% loss, including dividends. If that decision sat on the table on 26 October 2025, what did the original case for 2.8% annual revenue growth, a 13.7% margin and a 14.6x future P/E fail to allow for?
Janus International Group has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On Janus International Group
The shares cost US$10.17 at the start of the period, and anyone looking at Janus International Group had to choose between two very different but reasonable stories.
The bullish narrative saw a Fair Value of US$11.4, a price implied by assumptions that 2.8% annual revenue growth and a 13.7% profit margin could be reached over about three years, supported by urban densification and smart access control.
The bearish view anchored on a Fair Value of US$9, focused on self-storage demand softening as high interest rates weighed on new construction and left Janus exposed to weaker R3 activity and concentrated customers.
What The Results Changed For Janus International Group
The key update for Janus International Group was the Q2 2026 earnings print. Revenue reached US$233.5m, above the prior US$228.1m, which lent some support to the growth side of the bullish story. Net income dropped from US$20.7m to US$10.7m and the net margin moved from 9.1% to 4.6%, which challenged the margin expansion narrative. Overall, the evidence cut both ways.
The useful takeaway is simple. When a thesis leans on margin expansion, do not just watch sales. Track net margin and absolute profit in each report and ask whether they are moving toward the story you paid for.
What You Would Be Paying For In Janus International Group Today
Today Janus International Group trades at US$4.28. The selected Narrative’s Fair Value sits above the current price and leans on the idea that smart access, R3 retrofit work and international self storage can reshape the earnings mix.
For that view to hold, a buyer today would need confidence that Noke adoption, R3 renovation activity and overseas expansion translate into durable, higher quality earnings despite margin pressure.
"The main thing that has to go right is that Janus converts its growing Noke smart security installed base, international self-storage expansion, and R3 renovation activity into sustained, higher quality earnings while managing ongoing margin pressure and weaker North American new construction demand."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 37% below our estimate - helps clients run complex user research, failure analysis and regulatory integration projects.
- Company 2 - 32% below our estimate - supplies high-density GPU systems and software stack for specialised AI training workflows.
- Company 3 - 22% below our estimate - embeds adaptive AI tools into productivity, cloud and developer environments enterprises already use.
Three companies from the same screener. Open the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com