


Bond yields sit near 5%, the Fed is hinting at tighter policy ahead, and inflation keeps showing up in more than just energy bills. That mix punishes expensive stories and pushes attention toward companies that pay you to wait with dividends and trade on more grounded valuations. This article walks through three high-quality dividend value stocks exposed to these forces and discusses how they might fit, or not fit, into your playbook.
The three stocks below are a sample pulled from a wider pool, and the full screen surfaced 15 more large, dividend paying businesses with similar financial quality and story potential that are not covered here.
If you want to go straight to the source and identify your own highest conviction candidates, analyze and filter the full High-Quality Dividend Value Stocks list through the High-Quality Dividend Value Stocks screener.
Artesian Resources (ARTN.A)
Overview: Artesian Resources is a regulated water and wastewater utility serving households, businesses, and public customers across Delaware, Maryland, and Pennsylvania, aligning with the screener’s defensive dividend value focus.
Operations: Artesian Resources generates about $109 million from regulated utility services and $8 million from other activities, all within the United States.
Market Cap: $352 million
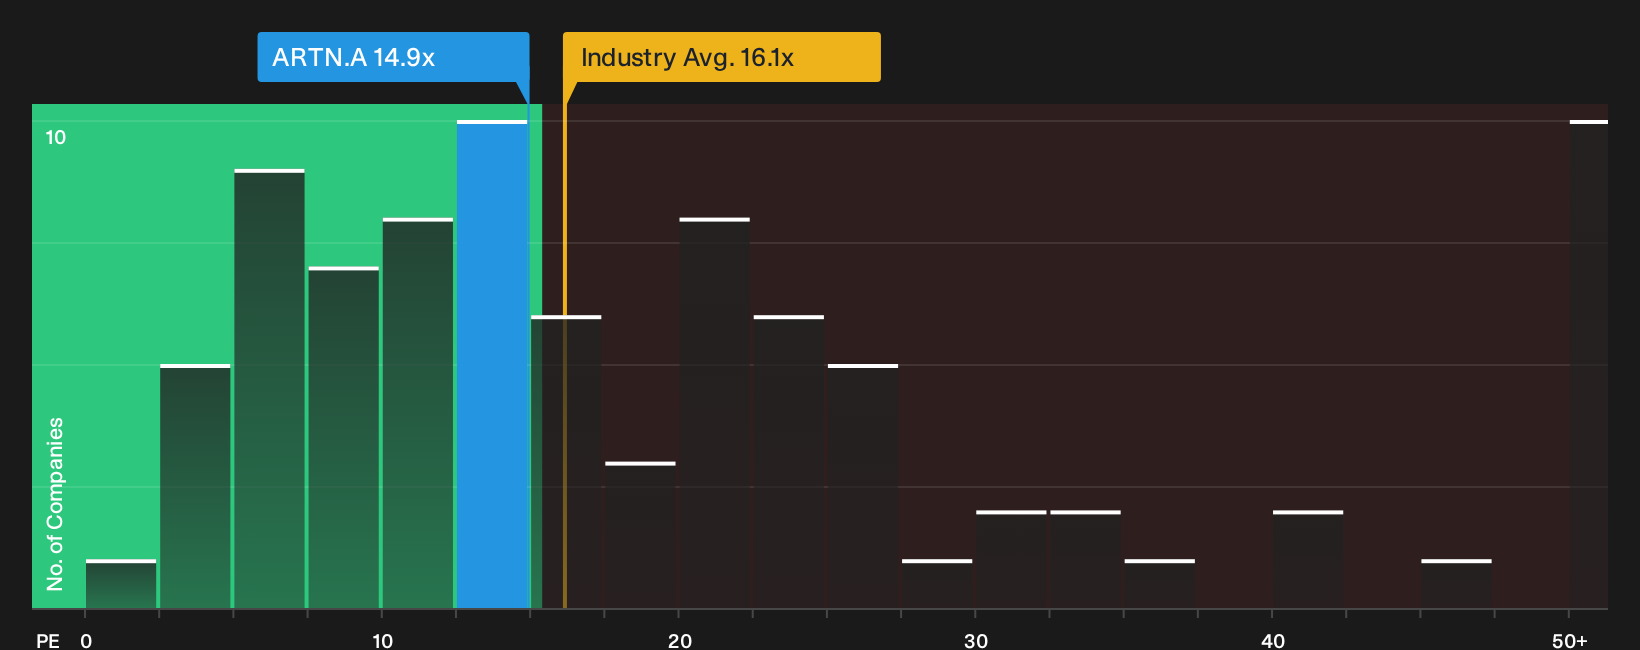
Artesian Resources offers characteristics that may appeal to income-focused value investors in higher rate settings, including its status as a regulated utility with a 3.76% dividend yield, a P/E of 14.9x that sits below both its peer average and the global utilities group, and a history of earnings growth that has outpaced its water utility peers. The appeal of that mix depends in part on how one unseen pressure on its balance sheet develops over time.
That hidden pressure is exactly why it helps to see the full picture through the Artesian Resources financial health report, so you can judge how resilient Artesian Resources really looks.
ResMed (RMD)
Overview: ResMed is a global medical technology group that sells cloud connected devices and software to diagnose, monitor, and treat sleep and breathing disorders, fitting the screener’s tilt toward large, cash generative healthcare dividend payers.
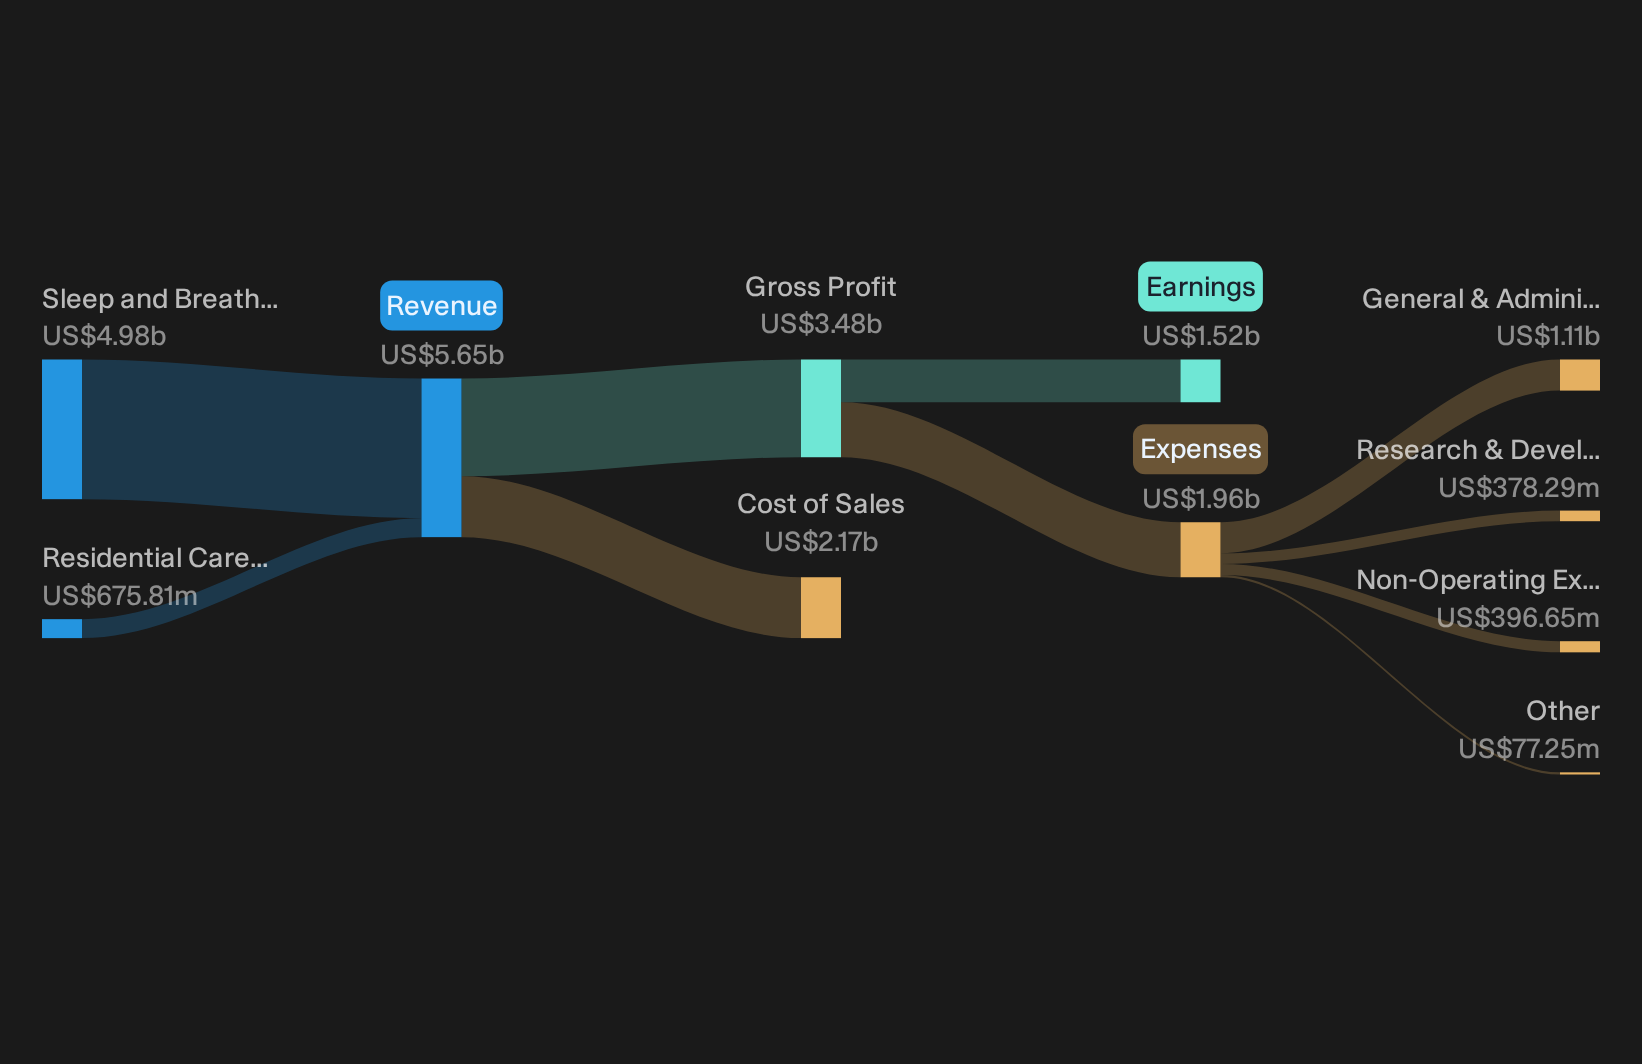
Operations: ResMed generates about US$5.0b from Sleep and Breathing Health and US$676 million from Residential Care Software, mainly across the United States and the rest of the world.
Market Cap: US$35.6b
ResMed brings something slightly different to this dividend value screen by combining a sizeable recurring hardware and software footprint with healthcare resilience that can matter when higher discount rates pressure more speculative growth stories.
"Expansion of the diagnosis and treatment funnel through partnerships with consumer wearables and GLP-1 driven patient flows is bringing more previously undiagnosed sleep apnea patients into the ResMed ecosystem, which can support future device and mask revenue growth."
One key consideration for ResMed is how one less visible margin lever evolves under tighter money conditions and rising equity discount rates.
That hidden lever is exactly what the full narrative for ResMed unpacks, showing where ResMed’s profit engine could accelerate or stall as funding costs bite.
Quest Diagnostics (DGX)
Overview: Quest Diagnostics is a large U.S. lab operator that runs diagnostic testing and health data services for doctors, hospitals, insurers, employers, and consumers, which fits the screener’s tilt toward recurring, dividend paying healthcare businesses.
Operations: Quest Diagnostics generates about US$11.6b from Diagnostic Information Services and US$254 million from DS Revenues, almost entirely in the United States.
Market Cap: US$26.6b
Quest Diagnostics brings a different angle to this dividend value screen, pairing a broad diagnostic footprint with cash flow that often tracks routine healthcare demand rather than market cycles. This may matter more as higher for longer rates push some investors toward steadier earnings streams.
"The continuing shift toward preventive healthcare and wellness, supported by Quest Diagnostics’ roughly US$300 million consumer business that is growing at about 30% and is expected by management to grow more than 20% annually over the next 3 to 5 years with margins above the corporate average, is setting up a larger recurring revenue base and higher earnings contribution from cash-pay testing."
What happens to that earnings profile if one less visible pressure on reimbursement and testing volumes turns out harsher than current assumptions?
If that pressure actually reshapes Quest Diagnostics’ earnings path, the full narrative for Quest Diagnostics shows where recurring demand could still accelerate and where margins might quietly stall.

Seeking Fresh Alternatives Before Others?
Fresh opportunities move first. Breakout momentum, dropping risk, and under the radar stories rarely stay quiet for long. Check these curated ideas before the crowd and consider them at an early stage.
- Spot early potential in smaller companies that already show financial discipline by using the curated 7 elite penny stocks with strong financials before momentum really accelerates.
- Track where real business adoption of crypto and blockchain is happening, rather than hype, by scanning the focused 16 cryptocurrency and blockchain stocks while it still flies under most radars.
- Focus on resilient balance sheets and clean fundamentals with the hand picked list of solid balance sheet and fundamentals (24 results) before changing valuations narrow the opportunity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com