


- H2O America reported Q3 2026 sales of US$250.23 million and net income of US$43.04 million, alongside nine month sales of US$644 million and net income of US$88.65 million, and declared a quarterly dividend of US$0.44 per share.
- The dividend increase to an expected US$1.76 per share for 2026, compared with US$1.68 in 2025, highlights how management is using the current earnings base to balance higher capital needs, recent Texas expansion and shareholder cash returns.
- We will examine how H2O America’s investment narrative is influenced by Q3 earnings and the higher 2026 dividend run rate.
Scan how H2O America compares with other income-focused utilities by reviewing a curated list of 5 dividend fortresses that pair shareholder payouts with robust underlying businesses.
H2O America Investment Narrative Recap
To own H2O America, you need to be comfortable with a regulated utility that is leaning into a bigger capex and Texas build out story while absorbing higher water production costs. The latest quarter showed higher sales alongside lower quarterly earnings per share, so the near term swing factor is how well management keeps project spending and financing costs aligned with earnings power.
The biggest operational risk still sits in execution of the US$2.7b capital plan and PFAS program while dealing with wholesale water prices and sometimes tough regulators. The recent results do not fundamentally change that setup. They simply underline that cost recovery timing and rate case outcomes remain the key watchpoints for the next year.
The most directly relevant update is the quarterly dividend of US$0.44 per share, with the 2026 annualized payout expected at US$1.76, compared with US$1.68 in 2025. For a regulated utility such as H2O America, that decision signals confidence that current earnings can support both a higher cash return and the enlarged infrastructure pipeline.
For you as an investor, the trade off is clear. The dividend stream looks more generous, yet free cash flow coverage and interest costs are already flagged as pressure points. The catalyst to track is whether new Texas connections, PFAS spend going into rate base, and ongoing rate decisions can keep pace with that higher dividend run rate without eroding financial flexibility.
What The Current H2O America Forecasts Assume
Analysts are building a fairly specific roadmap for H2O America that ties the Texas build out and PFAS program into a higher earnings profile by the late 2020s. The story on paper is that the capital plan, acquisitions and regulatory outcomes can support both a growing dividend stream and a larger profit pool over the next few years.
The consensus framework pegs revenue growth at 9.0% per year over the next 3 years, paired with an increase in profit margins from 12.9% today to 17.5% in that same window. The core earnings anchor is US$107.0 million of earnings today, with analysts projecting this to reach US$188.3 million and earnings per share of US$3.75 by about 2029, while the more optimistic forecasts point to as much as US$215.4 million.
On those 2029 earnings expectations, the current analyst model assumes H2O America would trade on a P/E of 22.5x. This is slightly below the 22.9x multiple implied today and above the cited 21.3x for the broader US water utilities group. That setup effectively bakes in higher profits but not a meaningfully richer multiple, so most of the upside case leans on execution rather than a re rating.
H2O America's narrative projects US$1.1b revenue and US$188.3 million earnings by 2029. This implies 9.0% yearly revenue growth and an earnings increase of about US$81 million from US$107.0 million today.
Uncover why H2O America's fair value indicates a 15% potential upside to its current price before the market closes that discount.
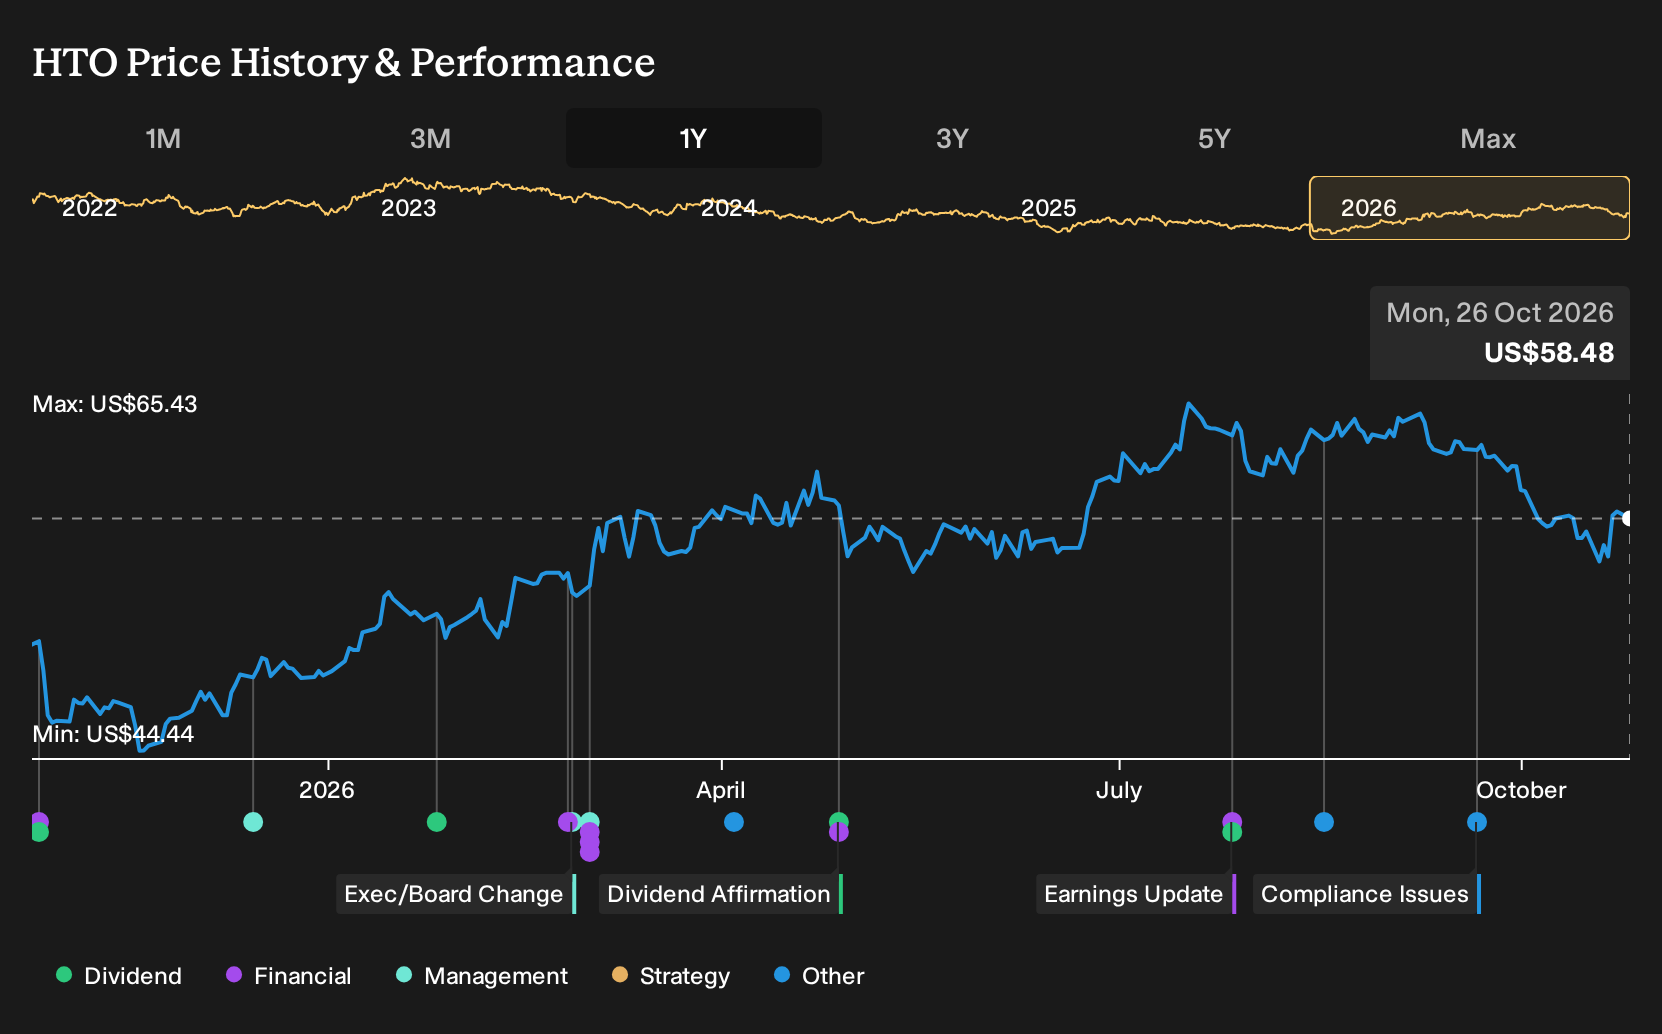
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$47.14 to US$67 per share for H2O America, so private investors are clearly not aligned on upside. In addition, rising wholesale water costs and a US$2.7b capex plan are prompting real debate on long term earnings power. Use that spread as a prompt to explore multiple viewpoints before deciding how H2O America fits your own income and risk mix.
Explore 2 other H2O America fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your H2O America research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for H2O America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H2O America's overall financial health at a glance.
Looking For More Investment Ideas Beyond H2O America?
Once you are comfortable with where H2O America fits in your portfolio, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly filter the market by quality, balance sheet strength, income potential and more so you can build a watchlist that matches your own goals instead of relying on a single story.
- For investors who care most about stability and capital preservation, focus on companies with resilient balance sheets and dependable fundamentals through a list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced opportunities where business quality and valuation work together, scan a 21 high quality undiscovered gems that the wider market may not be paying much attention to yet.
- When income is your priority and you want to compare H2O America's payout against peers, line it up against a 5 dividend fortresses built around higher yields supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com