


Sun Hung Kai Properties (SEHK:16) just cleared all 153 price listed units in the final sales round of its Sierra Sea Phase 2C(2) project, drawing investor attention to the development’s momentum.
That sales clean sweep comes at a time when Sun Hung Kai Properties’ shares trade at HK$107.7. The stock has a year to date share price return of 11.49% and a 1 year total shareholder return of 16.56%. This follows a 90 day share price decline of 11.29%, which tempers shorter term momentum compared with stronger multi year gains, including a 3 year total shareholder return of 54.11% and a 5 year total shareholder return of 34.51%.
Capitalize on the interest around Sun Hung Kai Properties by scanning a hand picked 195 high quality undervalued stocks that share solid fundamentals and potential for stronger long term total returns.Sun Hung Kai Properties has a broad, profitable platform and fresh demand signals from Sierra Sea, but the recent share pullback raises a sharper issue. Is this still a strong business at a fair price today?
Most Popular Narrative: 24% Undervalued
On the most followed narrative, Sun Hung Kai Properties screens as undervalued, with a fair value of HK$141.41 against the last close of HK$107.7. This puts the recent share pullback in a different light for anyone weighing the balance between Sierra Sea momentum and longer term income visibility.
The key factor is that Sun Hung Kai Properties continues to convert its low gearing, Hong Kong and Mainland land bank, and new commercial clusters into profitable projects with resilient occupancies and margins, despite pressure on parts of the rental portfolio.
See why 5 investors see Sun Hung Kai Properties as 24% undervalued.
Result: Fair Value of HK$141.41 (UNDERVALUED)
Still, the thesis on Sun Hung Kai Properties hinges on areas that could disappoint, including softer Hong Kong residential margins and more cautious contracted sales guidance for FY 2027.
Find out about the key risks to this Sun Hung Kai Properties narrative.
Another View: Our DCF Comes To A Lower Number
The analyst narrative frames Sun Hung Kai Properties as 24% undervalued at a fair value of HK$141.41. Our DCF model paints a cooler picture. At HK$107.7, the share price sits above an estimated future cash flow value of HK$80.65, which points to a premium rather than a discount.
That gap between earnings based optimism and cash flow based caution raises a practical question for investors. Which matters more for Sun Hung Kai Properties today: the income pipeline, or what the SWS DCF model suggests about future cash generation?
Look into how the SWS DCF model arrives at its fair value.
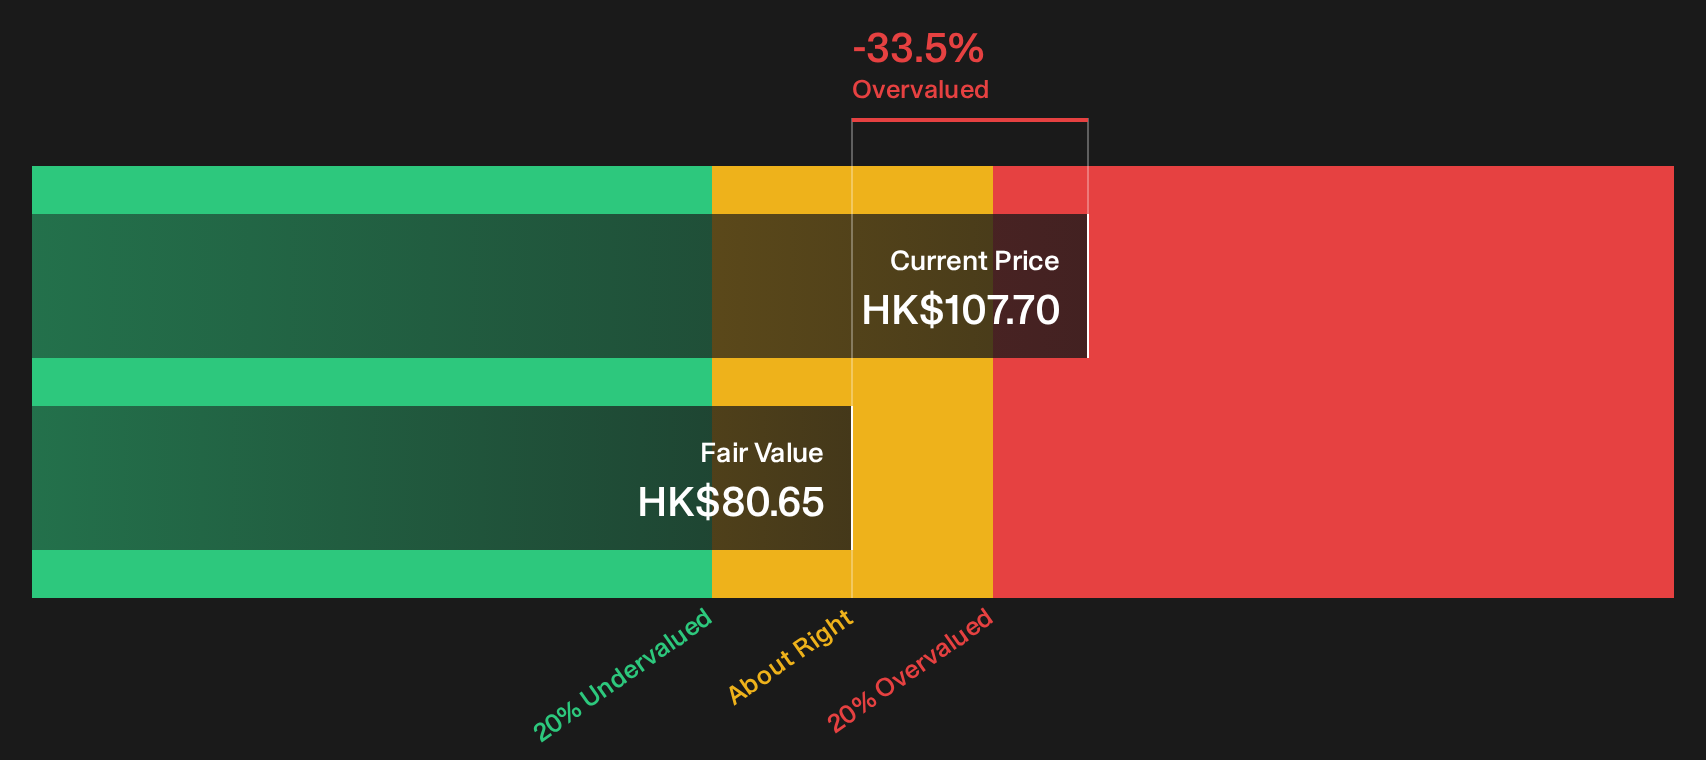
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sun Hung Kai Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sun Hung Kai Properties so far. Check the data now, weigh both sides, and anchor your own call using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sun Hung Kai Properties?
Do not stop your research with Sun Hung Kai Properties. Broaden your watchlist now so you are not relying on a single story to drive future returns.
- Target reliable cash flows from established businesses by scanning a curated set of income focused candidates using the 224 dividend fortresses.
- Hunt for resilient balance sheets and healthier fundamentals by reviewing the hand picked list of solid balance sheet and fundamentals (207 results) before the crowd pays closer attention.
- Spot under followed opportunities with strong metrics by working through a focused 610 high quality undiscovered gems that many investors may not yet be tracking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com