


- Northeast Bank reported first quarter 2027 results for the period ended September 30, 2026, with net interest income of US$58.92 million, net income of US$28.99 million, and basic earnings per share from continuing operations of US$3.47.
- The gap between net interest income and net income, alongside both basic and diluted EPS from continuing operations, provides a clearer view of how Northeast Bank is converting its interest spread into bottom line profitability.
- We will now look at how Northeast Bank’s higher net interest income could affect the investment narrative investors held before these results.
Scan how Northeast Bank’s latest interest income and earnings compare with peers by reviewing a curated list of list of solid balance sheet and fundamentals (24 results).
Northeast Bank Investment Narrative Recap
For an investor to stay in Northeast Bank, the core belief is that its national lending platform can keep sourcing attractive purchased and originated loans while holding asset quality and efficiency roughly where they are. The latest quarter supports that narrative in the near term, with higher net interest income and earnings pointing to an engine that is still converting its loan book into profit.
The most important short term catalyst remains execution on loan volume and pricing, especially in purchased commercial real estate and SBA lending. The biggest risk is margin pressure from competition and higher tech spending. This earnings print does not materially change either factor, but it does show the current model still producing strong bottom line results.
The fresh Q1 2027 report on October 26 is the key update to plug into that thesis. Net interest income of US$58.92 million, net income of US$28.99 million, and basic EPS from continuing operations of US$3.47 provide concrete evidence of how Northeast Bank is monetising its purchased loan pipeline right now.
Context matters for catalysts. Analysts see value in remaining purchase discounts in the commercial real estate portfolio and in targeted SBA 7(a) production once rule changes are fully absorbed. The latest earnings confirm there is still profit coming through while SBA volumes sit below prior levels. As a shareholder, the focus stays on whether management can keep sourcing quality pools and scaling volumes without losing discipline on pricing or costs.
Northeast Bank's current earnings of US$107.5 million are set against analyst expectations for US$147.6 million of earnings on US$342.6 million of revenue by 2029, which implies revenue growth of 13.1% per year and an earnings increase of about US$40 million by the forecast year.
Uncover how Northeast Bank's fair value indicates a 9% potential upside to its current price that may not last much longer.
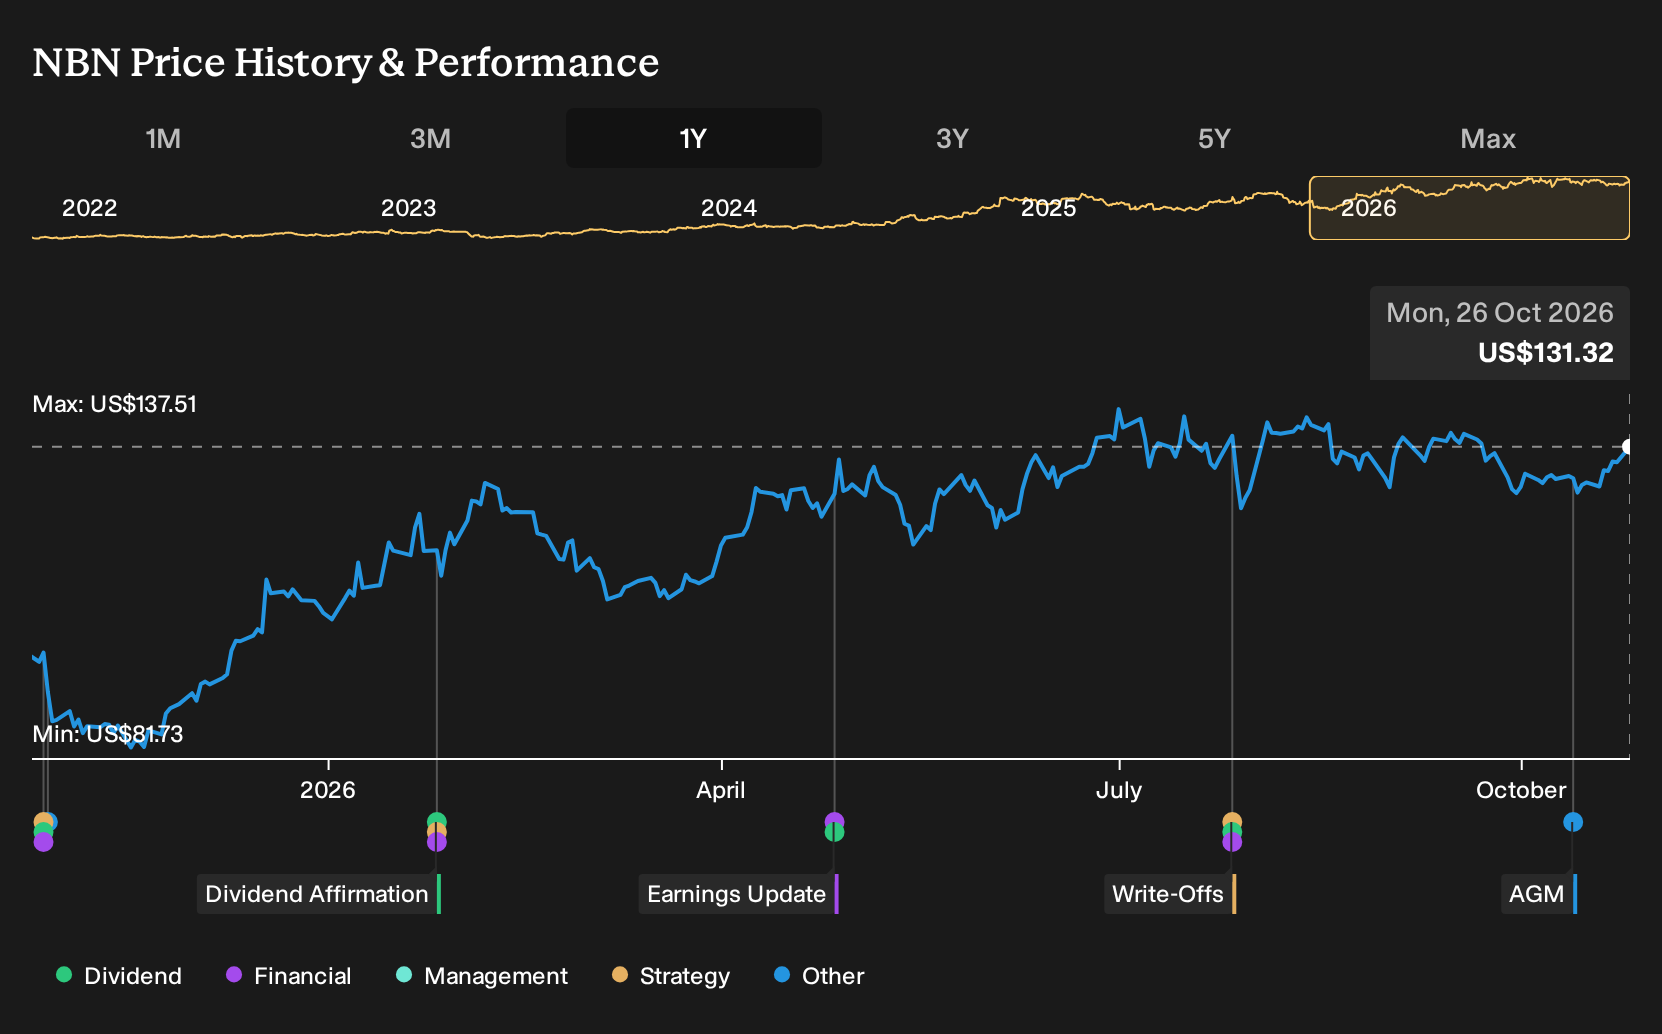
Exploring Other Perspectives
One alternate angle you might consider focuses on funding costs. The most pessimistic analysts were already cautious, even while assuming revenue of about US$354.8 million and earnings near US$152.1 million by 2029. They worry that reliance on wholesale funding could squeeze Northeast Bank’s net interest margin, so this new earnings report may spark fresh debate and potentially shift those estimates.
Explore 2 other Northeast Bank fair value estimates, including one that suggests it could be worth just $136.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Northeast Bank research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Northeast Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northeast Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Northeast Bank?
If this update on Northeast Bank has sharpened your thinking and you want to stress test your approach across a wider watchlist, the Simply Wall St Screener can quickly surface other opportunities that fit your style.
- If you care most about resilient balance sheets and steady fundamentals, start by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor the risk side of your portfolio.
- For investors who want value to be front and centre, filter for companies trading below their estimated worth through a focused set of 29 high quality undervalued stocks that may deserve a closer look.
- Income focused readers who prefer to be paid while they wait can zero in on yield opportunities by reviewing a curated pool of 5 dividend fortresses that combine higher payouts with robust financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com