


If Microchip Technology was on your watchlist instead of in your portfolio, the recent move probably caught your eye. Investors who held Microchip Technology over the past year are up 20.7%, including dividends. That outcome looks simple in hindsight, yet back on 26 October 2025 investors had to judge whether industrial, automotive and edge computing demand would really turn elevated inventories into higher factory utilization and healthier margins. How could you have assessed that basic operating assumption at the time?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Microchip Technology is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Two Microchip Technology Stories Investors Had To Choose Between
The shares cost US$63.13 at the start, so any Narrative around Microchip Technology had to stack up against that live quote.
On the optimistic side, the bull case put Fair Value at US$76, about 20% above the start price, assuming 15.8% revenue growth and a 22.0% profit margin within three years. That view hinged on industrial, automotive and edge computing demand lifting utilization and earnings.
The more cautious argument marked Fair Value at US$57.92, about 8% below the start price, and focused on elevated inventories plus a 9-point restructuring plan. This scenario treated factory consolidation, higher expenses and refinancing risk as potential drags even if efficiency improved later.
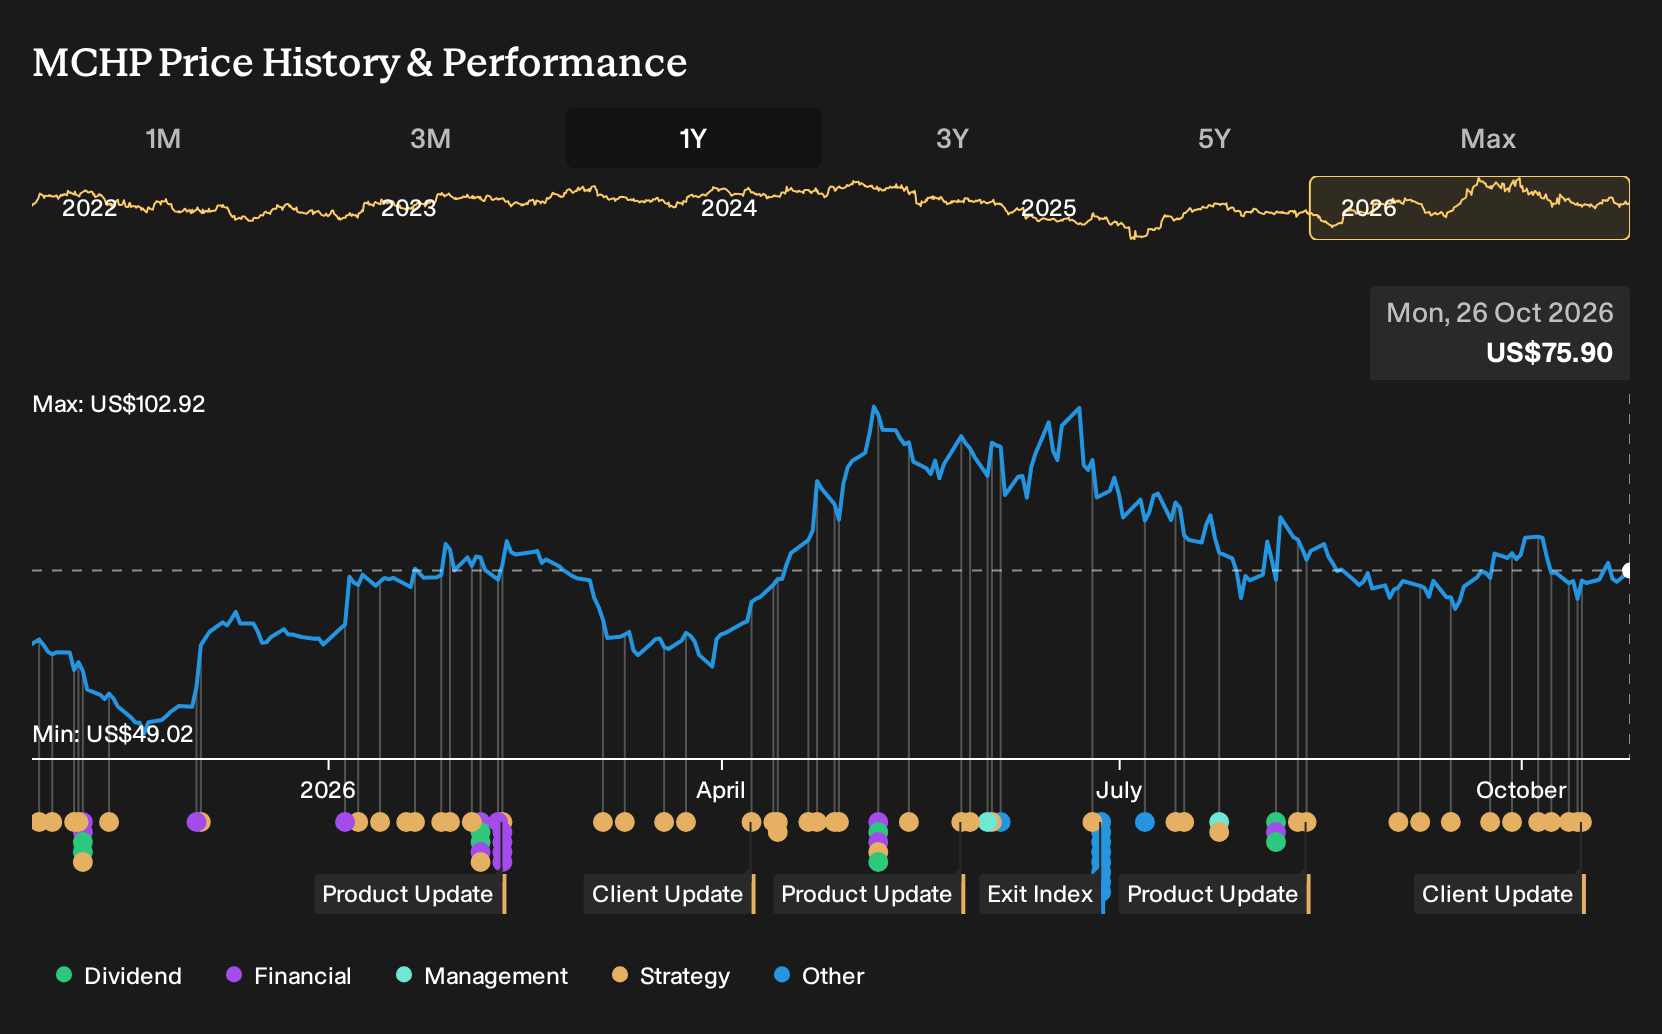
What The 2026 Results Tested In The Microchip Technology Story
Microchip Technology’s Q1 2027 update showed revenue of US$1.484b and net income of US$202m, compared with a Q1 2026 loss of US$46.4m, so net margin shifted from 4.3% negative to 13.6% positive. That pattern supported the optimistic case that better utilization and inventory cleanup could lift profitability, although the margin still sat below the 22.0% target in the original bullish thesis. Overall, the evidence supported the optimistic case but left it unfinished.
The lesson is simple. When a recovery story rests on utilization and inventory, focus on the net margin line and cash generation each quarter, not just the revenue rebound or share price reaction.
What Microchip Technology’s Price Seems To Be Saying Now
Microchip Technology trades at US$75.9 today, after a 20.7% gain over the past year. The selected Narrative’s Fair Value sits above the current price, based on the view that margin repair and cash generation remain the central levers.
That Narrative also leans on data center, aerospace, defense and edge AI exposure plus restocking. It argues today’s price still does not fully credit the potential mix shift toward higher margin AI linked products and licensing.
"The current narrative and supporting figures imply that Microchip Technology's share price does not fully reflect the scale of its data center and defense ramps, its AI product optionality, and its progress in deleveraging the balance sheet."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Microchip Technology
Once you understand Microchip Technology, it is natural to look sideways. Your chips and controllers still rely on something more basic.
Data has to move quickly, reliably and at scale. That calls for specialist hardware and software that keep networks, storage and security stitched together.
Another large supplier focuses on exactly that digital plumbing. It builds connectivity and infrastructure tools that help customers run private clouds and complex data centers.
The same demand drivers you watched for Microchip Technology, including computing intensity and data traffic, matter here too.
If those needs keep compounding, this adjacent business could see its role quietly expand.
The argument comes with a number attached. → Uncover the power-grid company trading 49% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com