


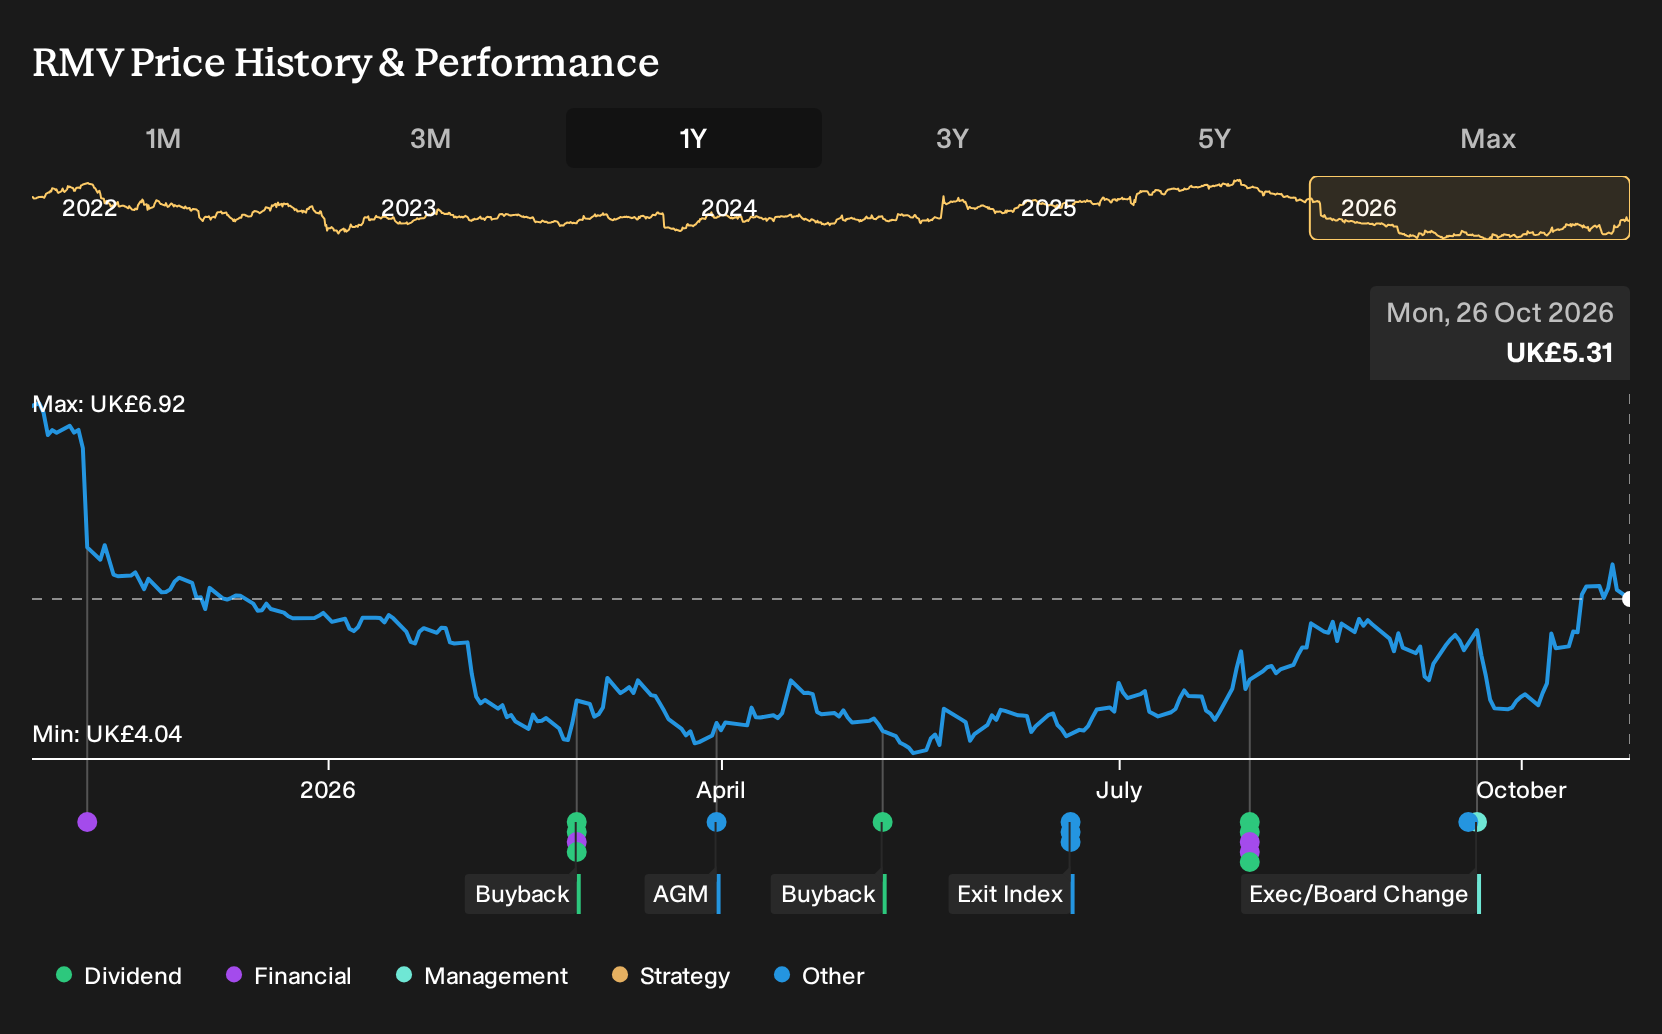
Rightmove’s latest half year report showed higher revenue and slightly higher profit, yet the share price went the other way. Investors who held Rightmove over the past year are down 21.5%, including dividends. If you had been weighing up a position last October, that gap between business progress and portfolio outcome would matter. So what exactly was on record then that could have hinted at this disconnect?
Rightmove is not the only name tied to this theme. Zero in on 94 robotics and automation stocks and compare how each one is priced.
The Two Rightmove Stories Investors Had To Weigh
The shares cost £6.88 at the start of the period, so anyone looking at Rightmove then had to decide which story about the future felt more realistic.
The bullish narrative pointed to a fair value of £7.78, essentially the price implied if digitisation and AI tools translated into stronger monetisation. That camp leaned on assumptions of 10.0% annual revenue growth and rising profit margins supported by higher ARPA and expansion into mortgages, rentals, and commercial listings.
The bearish view saw fair value at £4.85, a lower implied price if regulation and digital disruption constrained the upside. This scenario still assumed 8.1% yearly revenue growth yet stressed risks from tighter data rules, a saturated UK portal market, and pressure on pricing power as new proptech rivals gained traction.
What The Rightmove Results Put To The Test
Rightmove’s own housing data showed flat asking prices and softer sales, which leaned toward the cautious case that warned about a constrained UK market. At the same time, H1 2026 numbers recorded higher revenue and profit, although net margin slipped from 51.9% to 49.2%, so the profitability upside in the bullish story stayed unproven. Overall, the evidence cut both ways.
The useful takeaway is what to track. When a thesis leans on margin expansion, you test it against reported net margin and any later broker forecasts for growth, not just top-line progress.
What Today’s Rightmove Price Already Assumes
Rightmove now trades at £5.31, with this Narrative’s Fair Value framed above that level based on its own assumptions rather than hard fact. The argument leans on AI tools built on a large data set, plus an active plan for buybacks and dividends.
On that view, a buyer today would be assuming Rightmove can keep turning ARPA gains, AI assisted productivity and newer segments into sustained profit growth despite weaker New Homes activity.
"Rightmove's fully cloud enabled, AI capable tech stack with over 5 petabytes of unified data and 31 or more AI projects in flight creates room for entirely new data products and workflow tools that could support additional revenue lines and higher operating margins as more of development and operations become AI assisted."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 30% below our estimate - supplies specialist defence electronics and sensors for longer multi year underwater and autonomous programmes.
- Company 2 - 24% below our estimate - expands higher margin defence electronics, missiles and space work off a record order backlog.
- Company 3 - 28% below our estimate - advances stalled copper projects that would roughly double output and add polymetallic by product revenue.
That is three of the list. See every one of the 10 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com