


- Royal Caribbean Cruises reported third quarter 2026 sales of US$1,706 million and net income of US$1,728 million, with both quarterly and nine month basic EPS from continuing operations higher than the prior year.
- The earnings update shows both sales and net income for the first nine months of 2026 above the same period in 2025, which gives investors more concrete evidence about how the cruise operator is converting demand into profit.
- We will now explore how Royal Caribbean Cruises' higher earnings per share from continuing operations might influence the longer term investment narrative.
Compare Royal Caribbean Cruises' latest earnings momentum with a curated list of travel and leisure stocks that also pair demand with strong balance sheets via list of solid balance sheet and fundamentals (24 results).
Royal Caribbean Cruises Investment Narrative Recap
To own Royal Caribbean Cruises, you need to be comfortable with a consumer travel story that relies on filling a large fleet at attractive ticket and onboard spending levels while keeping a close eye on costs. The latest quarter delivered higher sales, revenue and earnings per share than a year ago, which supports that basic thesis but does not remove demand sensitivity.
The key short term swing factor remains pricing and booking strength into late 2026 and early 2027, especially in regions where commentary has flagged softer trends. Fuel and debt costs still sit in the background as meaningful risks. Even with firm earnings today, any reversal in demand or rise in input costs could pressure margins quickly.
The fresh earnings report for the quarter to 30 September 2026 is the clearest data point to focus on. Royal Caribbean Cruises posted quarterly sales of US$1,706 million and net income of US$1,728 million, with basic EPS from continuing operations at US$6.46 compared with US$5.79 a year earlier, and nine month EPS also above the prior period.
That kind of EPS momentum, alongside higher revenue for both the quarter and the year to date, feeds directly into the existing catalysts investors are watching, such as new ships, destination projects and loyalty driven onboard spend. It also helps offset some of the risks around fuel, Mediterranean softness and macro pressure, although it does not eliminate them.
Royal Caribbean Cruises Forecasts and Analyst Assumptions
Royal Caribbean Cruises now sits at an interesting junction where hard earnings for 2026 meet fairly punchy analyst spreadsheets for the next few years. Instead of just focusing on the last quarter, it helps to look at what the consensus numbers are actually asking the business to deliver.
Analysts are working off a forecast that revenue grows by 9.1% a year over the next three years. That is a material ramp in activity for a cruise operator that already runs a large global fleet, and it assumes the booking engine, pricing and onboard spending remain supportive enough to keep that compound pace going rather than flattening out.
Earnings expectations are even more ambitious in absolute terms. Forecasts point to profit rising from US$4.4b today to US$6.4b by 2029, which is an increase of about US$2b. That is a big jump in dollar terms and places clear pressure on Royal Caribbean Cruises to keep filling cabins at healthy yields while pushing margins higher from the current 23.5% level to a projected 26.2% over roughly the same window.
Those projections sit on top of some additional moving pieces. The analyst models assume the share count declines by about 1.93% each year for the next three years, so part of the earnings per share story comes from buybacks as well as from higher profit. The playbook also assumes a discount rate of 9.19% to pull those future cash flows back into today’s valuation, which matters if you are comparing Royal Caribbean Cruises with other travel and leisure companies that may be modeled using different risk assumptions or capital costs.
Royal Caribbean Cruises' narrative projects US$24.3b revenue and US$6.4b earnings by 2029. This leans on 9.1% yearly revenue growth and about US$2b earnings increase from US$4.4b today.
Uncover why Royal Caribbean Cruises' fair value indicates a 25% potential upside to its current price, which could narrow quickly.
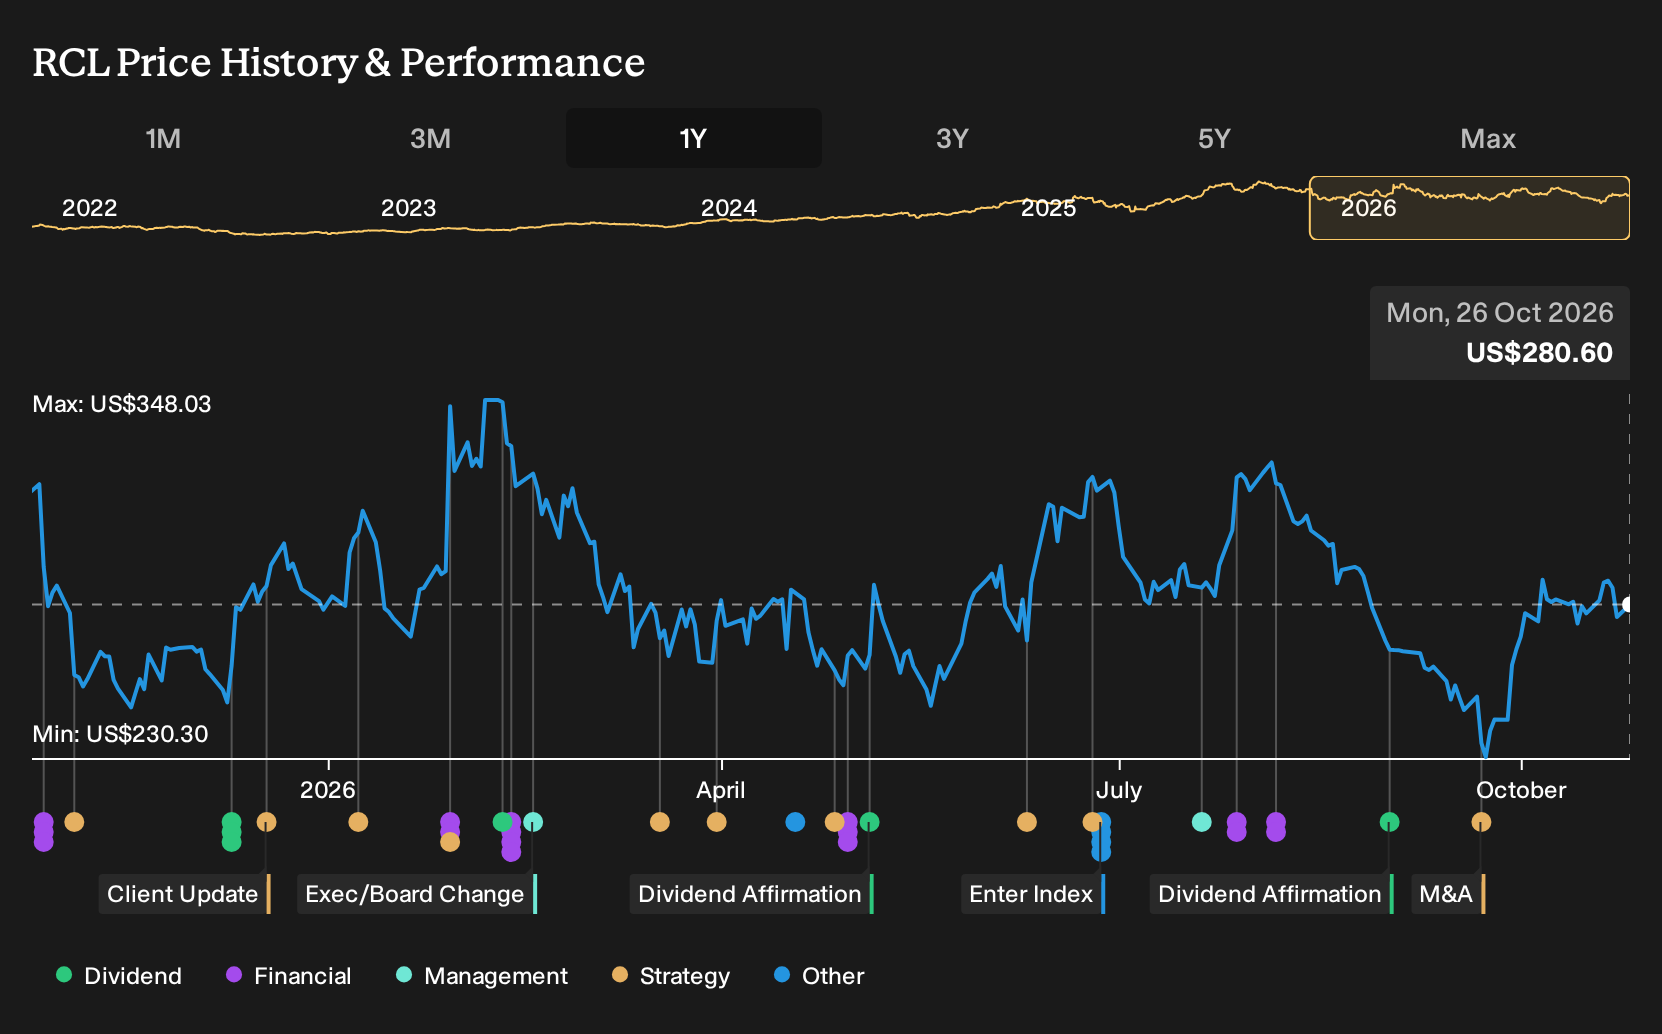
Exploring Other Perspectives
One bearish angle on Royal Caribbean Cruises focuses on passenger cruise day growth. The most conservative analysts were estimating only 8.0% yearly revenue growth and about US$23.6b in revenue by 2029. You can read this as a much more cautious story, which the latest earnings beat has not yet been able to challenge or confirm in their models.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests it could be worth just $275.45.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Royal Caribbean Cruises?
If you want to pressure test your view on Royal Caribbean Cruises against other opportunities, the Simply Wall St Screener lets you scan the market using the same kind of earnings quality, balance sheet strength and risk filters used in this analysis.
- For investors who want income with a cushion, focus on businesses that pair higher yields with sturdier fundamentals through 5 dividend fortresses.
- If capital preservation ranks high on your checklist, narrow the field to companies with steadier financial profiles by using the 30 resilient stocks with low risk scores.
- When you want something off the beaten path, widen your research to financially sound smaller companies that fewer people are watching through 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com