


Hitachi (TSE:6501) drew fresh attention after Raiffeisen Informatik adopted Hitachi Vantara’s cyber resiliency architecture, which cut modeled mainframe recovery times from about seven days to between one and two hours.
Hitachi’s recent client wins arrive against a backdrop of solid momentum, with the share price at ¥5,640 and a 90 day share price return of 13.78% contributing to a 1 year total shareholder return of 21.88% and a 5 year total shareholder return of 349.38%.
Scan other potential beneficiaries of rising demand for secure, resilient infrastructure by reviewing our hand-picked 42 power grid technology and infrastructure stocks along with Hitachi's latest win.
After a 13.78% move over 90 days and a 5 year total return above 300%, the question now is whether Hitachi’s valuation still leaves meaningful upside or has already priced in most of the story.
Most Popular Narrative: 15% Undervalued
Against a last close of ¥5,640, the most followed narrative for Hitachi anchors on a fair value of ¥6,600, pointing to meaningful implied upside from the current level while hinging on execution in energy grids and digital services.
Reallocation of the portfolio toward Lumada, services and digital, alongside exits from non core assets such as the reduction of the Astemo stake and the sale of home appliances, is increasing the share of higher margin businesses like Energy services and DSS domestic IT, which targets 16 to 18% EBITDA margins by FY2027. This mix shift can support higher group earnings and cash generation over time.
See why 23 investors see Hitachi as 15% undervalued.
Result: Fair Value of ¥6,600 (UNDERVALUED)
Still, the whole Hitachi story depends on flawless execution in a very large Energy capex program, while geopolitical and tariff shocks could unsettle grid and digital demand.
Find out about the key risks to this Hitachi narrative.
Another View: What Multiples Say About Hitachi
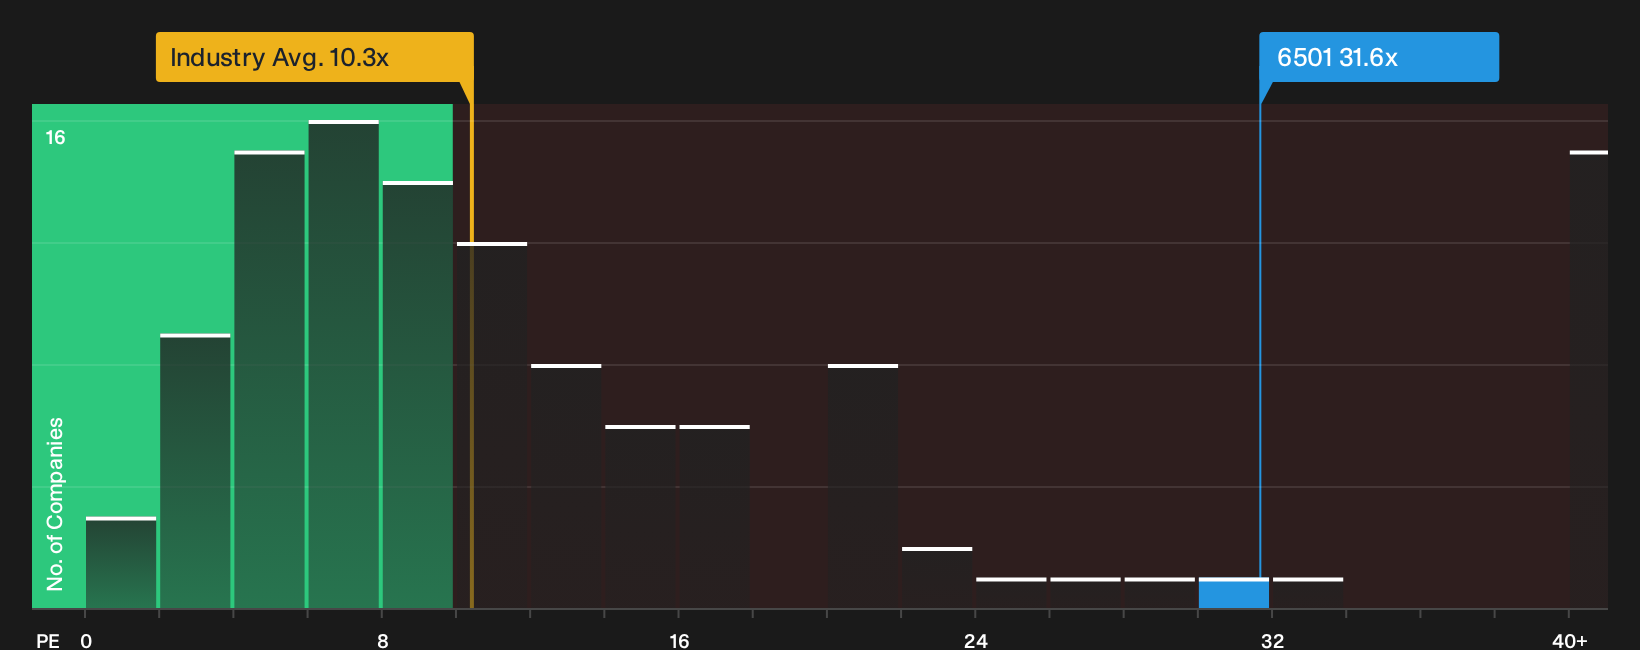
There is a different read on Hitachi when looking at the P/E ratio instead of fair value models. The shares trade on about 31.6x earnings compared with roughly 10.3x for the wider Asian Industrials group and around 12.5x for peers, while the fair ratio estimate sits closer to 32.1x.
This means the stock lines up near that fair ratio but at a much richer level than the sector and peer averages. This points to less margin for error if growth or returns disappoint. The key question is whether that premium reflects durable strengths or simply enthusiasm built on recent performance.
See what the numbers say about this price gap in our valuation breakdown, then compare it with the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer look at how Hitachi’s current earnings multiple stacks against the sector, review the latest valuation snapshot next to the
Next Steps
If this all sounds constructive for Hitachi, do not wait for consensus to harden before checking the underlying data and pressure testing the assumptions. Then weigh those signals against the 3 key rewards.
Looking for more investment ideas beyond Hitachi?
If Hitachi is on your radar, you may want to broaden your watchlist with a few focused idea sets that line up with different risk profiles and return goals.
- Explore potential bargains by scanning our curated pool of high quality businesses that may trade below intrinsic value through the 16 high quality undervalued stocks.
- Review companies that pair higher yields with resilient payout histories using the 29 dividend fortresses.
- Filter for companies with sturdier balance sheets and fundamentals inside the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com