


Sandoz Group (SWX:SDZ) has filed an anti-dumping complaint with the European Commission over Chinese amoxicillin ingredients, putting regulatory risk and antibiotic supply security directly on investors’ radar.
That regulatory push comes as Sandoz Group’s share price has been on a strong run, with a 30-day share price return of 15.74% and a year-to-date share price gain of 43.94%, alongside a 1-year total shareholder return of 66.19%, which indicates that momentum has been building rather than fading.
Scan how Sandoz Group compares with other pharmaceutical players protecting critical drug supply by reviewing our curated list of list of solid balance sheet and fundamentals (207 results)
Sandoz Group has already rewarded anyone who owned it during this 66.19% 1 year run, which raises a clear fork in the road. Do you pay up now for that momentum, or wait and hope for a cheaper entry before the valuation section does the talking?
Most Popular Narrative: 5% Overvalued
Sandoz Group closed at CHF82.36 against a widely followed fair value estimate of CHF78.32. The current quote sits modestly above that narrative anchor and puts more weight on whether the growth story can keep carrying the valuation.
The company's substantial pipeline (27 biosimilars and 400+ generics targeting ~$420 billion in originator sales) and strategic independence post-spin-off enable focused capital allocation and agile R&D, which is likely to drive sustainable double-digit earnings growth for several years.
See why 40 investors see Sandoz Group as 5% overvalued.
Result: Fair Value of CHF78.32 (OVERVALUED)
Still, the Sandoz Group story can be knocked off course if pricing pressure in generics intensifies, or if its heavy reliance on partnerships squeezes long term margins.
Find out about the key risks to this Sandoz Group narrative.
Another View: Cash Flows Point To A Different Sandoz Group Story
Price tags tell one story for Sandoz Group, but cash flows tell another. While the analyst fair value narrative sits at CHF78.32 and flags the shares as modestly overvalued, the SWS DCF model points to a future cash flow value of CHF121.37, which frames the stock as materially undervalued. That split forces you to decide which set of assumptions feels more realistic.
Look into how the SWS DCF model arrives at its fair value.
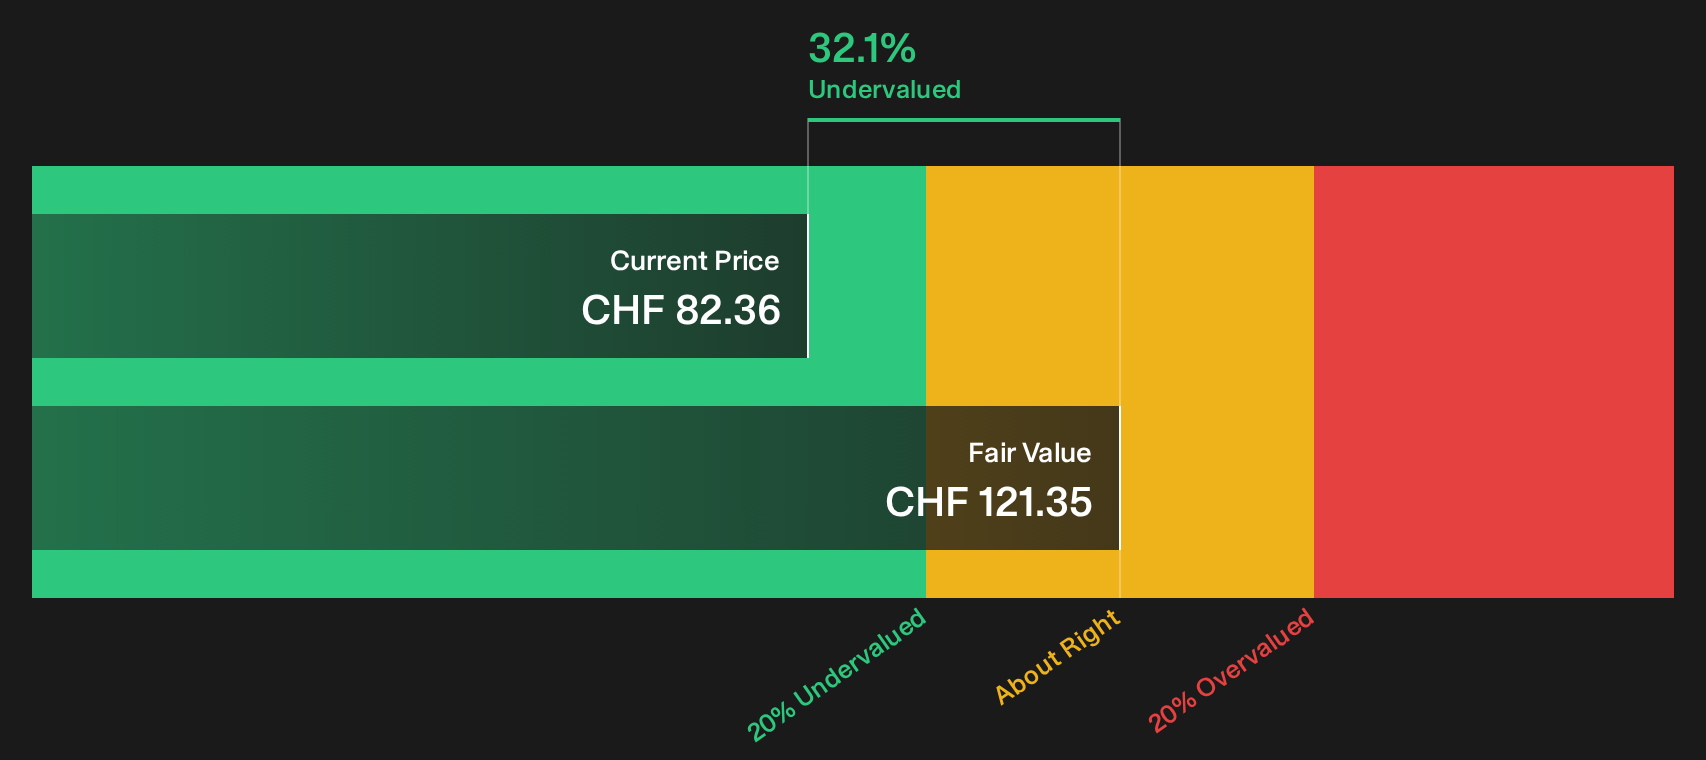
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sandoz Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Sandoz Group leave you unsure, move quickly, review the full data set, and pressure test the bullish angles yourself. To see which potential upsides others are focusing on, unpack the 3 key rewards.
Looking for more investment ideas beyond Sandoz Group?
If Sandoz Group has sharpened your focus, do not stop here. Broaden your watchlist with other high quality setups that could suit very different playbooks.
- Target resilient balance sheets by scanning companies that pass tough financial health checks with the list of solid balance sheet and fundamentals (207 results).
- Hunt for mispriced quality by using the screener that highlights 195 high quality undervalued stocks before the crowd catches on.
- Stack potential income streams by reviewing a curated group of 224 dividend fortresses that may align with a long term payout focus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com