


- UMB Financial is approaching its Q3 earnings release after previously reporting quarterly revenue of US$759.8 million, with analysts now modeling 10.4% year-on-year revenue growth and watching how the business balances lending and fee income momentum with expense control.
- Valuation metrics such as a 1.35 P/B ratio and a 15.76 P/CF ratio, alongside a value rating from Zacks, keep attention on how UMB Financial’s operating performance and balance sheet strength line up against peers.
- We now look at how UMB Financial’s investment narrative could be influenced by the upcoming Q3 earnings catalyst and valuation focus.
UMB Financial Investment Narrative Recap
For UMB Financial, the central idea is that a diversified banking and institutional services model can keep generating steady earnings, even as temporary supports such as purchase accounting accretion taper off. The near term story revolves around whether loan demand and institutional fee activity stay solid enough to offset the expected step down in accretion related net interest income.
The biggest short term swing factor is the upcoming Q3 print. It will show how well the Heartland integration, operating efficiency initiatives and double digit loan growth track record translate into current profitability. The key risk is that the elevated loan and fee growth seen recently proves hard to sustain, which would pressure operating leverage.
The most relevant fresh data point is UMB Financial’s Q3 earnings release scheduled for this Tuesday after the close. Last quarter, the bank reported US$759.8 million of revenue, above analyst expectations, with year on year growth of 15.1%. Analysts now look for 10.4% revenue growth, which would imply slower momentum that investors will likely scrutinise against recent loan trends.
That deceleration matters because the long term thesis relies on healthy organic activity in commercial lending and institutional businesses such as fund services and custody. If Q3 results indicate that revenue growth is settling at a more modest pace while purchase accounting income fades, the debate will likely center on whether expense control, fee diversification and capital strength can keep earnings on a stable path.
Analyst Scenario For UMB Financial Into 2029
Analysts frame UMB Financial's medium term story around a few simple building blocks. Revenue is modeled to rise at 7.7% a year over the next three years, while profit margins are expected to edge up from 32.6% today to 34.2% in that same window. That combination underpins a consensus view that earnings could move from US$917.3 million currently to US$1.2 billion by 2029, with share count assumed to be broadly flat.
UMB Financial's narrative projects US$3.5 billion revenue and US$1.2 billion earnings by 2029. This requires 7.7% yearly revenue growth and an earnings increase of about US$282.7 million from US$917.3 million today.
Those earnings assumptions also feed straight into the valuation math investors are watching. On the analyst numbers, the bank would be trading on a P/E of 12.7x its 2029 earnings versus about 11.0x today. That prospective multiple sits above the 11.4x cited for the broader US banks industry. The implied fair value work uses a discount rate just over 7%, which matters if you are comparing these forecasts with your own required return.
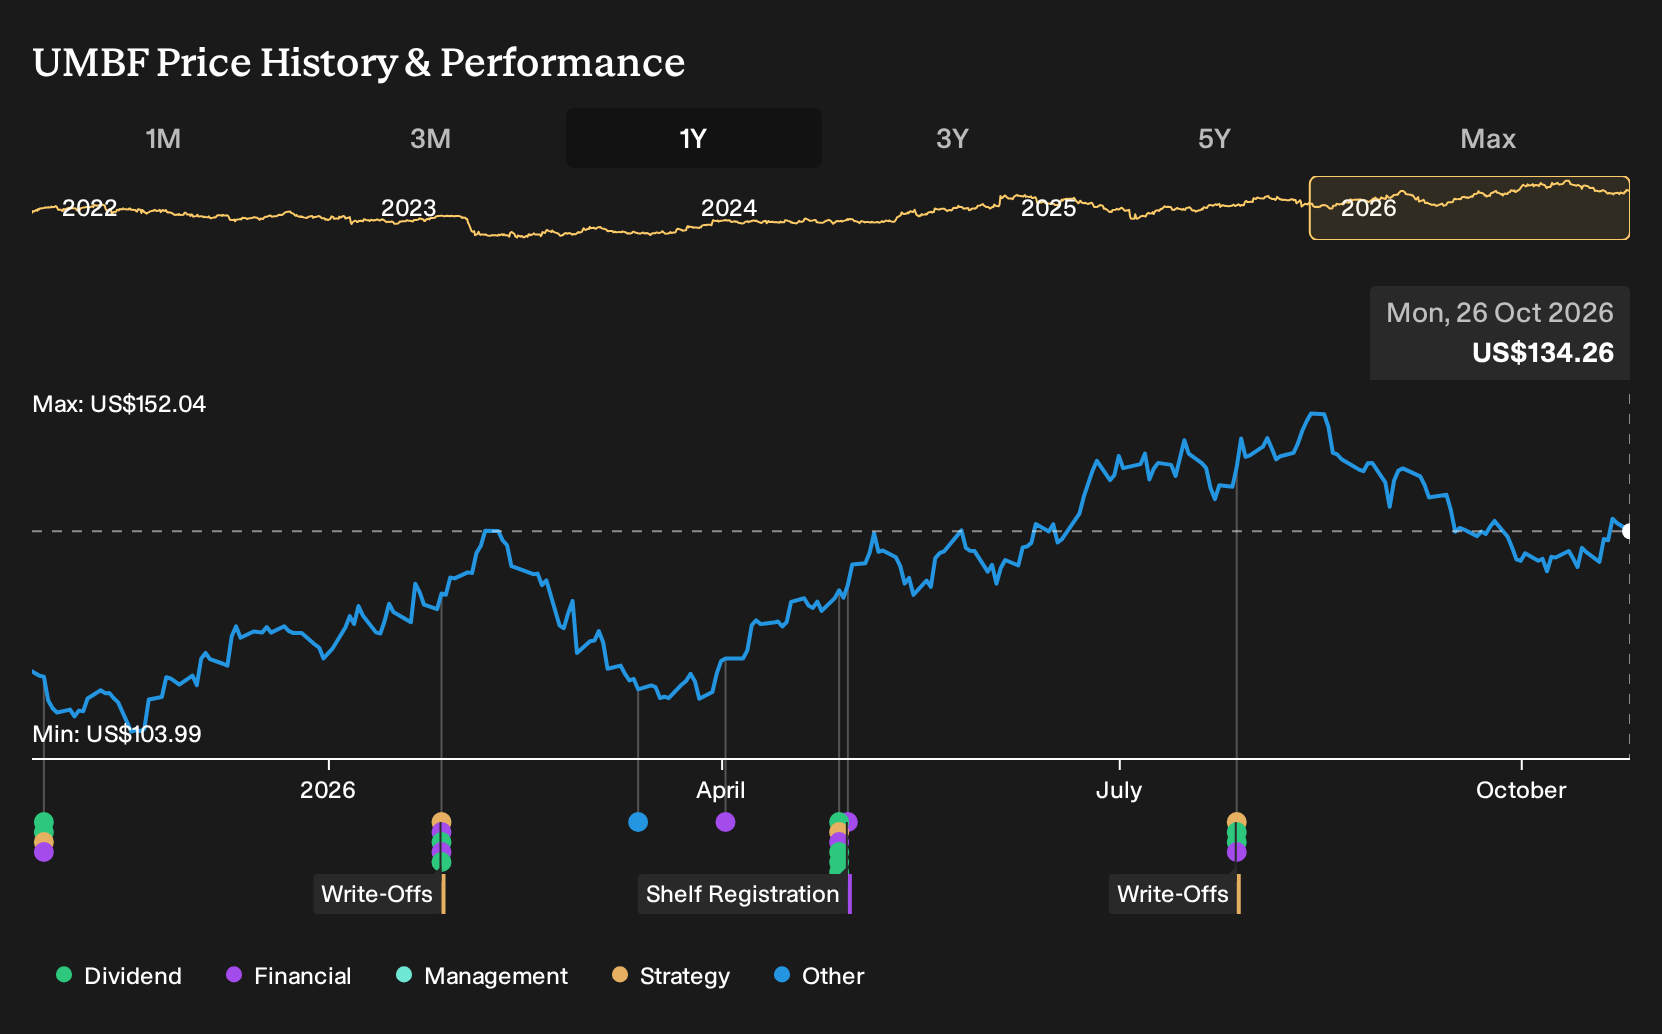
Price targets cluster around that story. The current consensus sits at US$163.12 per share, compared with a recent price of US$133.09, with individual analyst targets running from US$145 at the low end to US$182 at the high end. That spread highlights that even when the revenue, earnings and margin paths look tidy on paper, there is still a wide range of views on how UMB Financial should be priced against those projections.
Uncover why UMB Financial's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$163 to US$231 per share, so you are seeing very different views on UMB Financial’s upside. Those retail perspectives sit alongside catalysts such as the Q3 earnings release and the recent Argus target lift, which could reshape how you think about the company’s risk reward trade off.
Explore another UMB Financial fair value estimate, including one that suggests as much as 72% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UMB Financial research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UMB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMB Financial's overall financial health at a glance.
Looking for more investment ideas beyond UMB Financial?
If UMB Financial has sharpened your thinking on balance sheets, earnings power and valuation, broaden that lens across the wider market using the Simply Wall St Screener to spot other opportunities that fit your preferred mix of risk, quality and price.
- If capital preservation comes first for you, start with companies that pair resilient financial profiles with measured risk using our 30 resilient stocks with low risk scores.
- If you care most about financial strength, focus on businesses with sturdy balance sheets and fundamentals by scanning the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced quality, look for potential bargains with sound cash flows and robust finances through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com