


Omnipod Discover rollout puts Insulet’s data tools in focus
Insulet (PODD) has pushed its Omnipod Discover web-based data platform nationwide in the US, extending access beyond earlier limited users and linking product adoption trends directly to the diabetes technology data story.
That product story is playing out against a mixed share price backdrop, with Insulet’s stock up 9.65% on a 1 month share price return and 5.14% over 7 days, yet still down 47.24% on a year to date share price return and showing a 54.19% decline in 1 year total shareholder return. This indicates that recent momentum has picked up after a much tougher stretch as investors reassess growth prospects and risk following launches such as Omnipod Discover.
Compare Insulet’s rebound with other potential diabetes and medtech beneficiaries by scanning the hand-picked 34 healthcare AI stocks now gaining attention from data driven treatment trends.
Insulet’s short term bounce could point to confidence in Omnipod 5 and Discover, or it could simply reflect a sentiment swing in a bruised stock. How does today’s valuation frame that split?
Most Popular Narrative: 11% Undervalued
On Simply Wall St’s most followed view, Insulet’s fair value sits at $167.17 compared with a last close of $149.26. This frames the recent Omnipod momentum against a still discounted share price.
Rapidly rising adoption of Omnipod 5 in both the U.S. and international markets, supported by Q2 2026 total revenue of US$802 million and 23% growth in the global customer base, points to Insulet gaining share in a growing diabetes device market, which can support ongoing revenue growth and operating leverage.
See why 23 investors see Insulet as 11% undervalued.
Result: Fair Value of $167.17 (UNDERVALUED)
Still, the Insulet narrative relies on fixing weaker type 2 retention and managing recall related reputational risk. Both of these factors could limit how much the Omnipod story supports upside.
Find out about the key risks to this Insulet narrative.
Another View: Insulet Through The P/E Lens
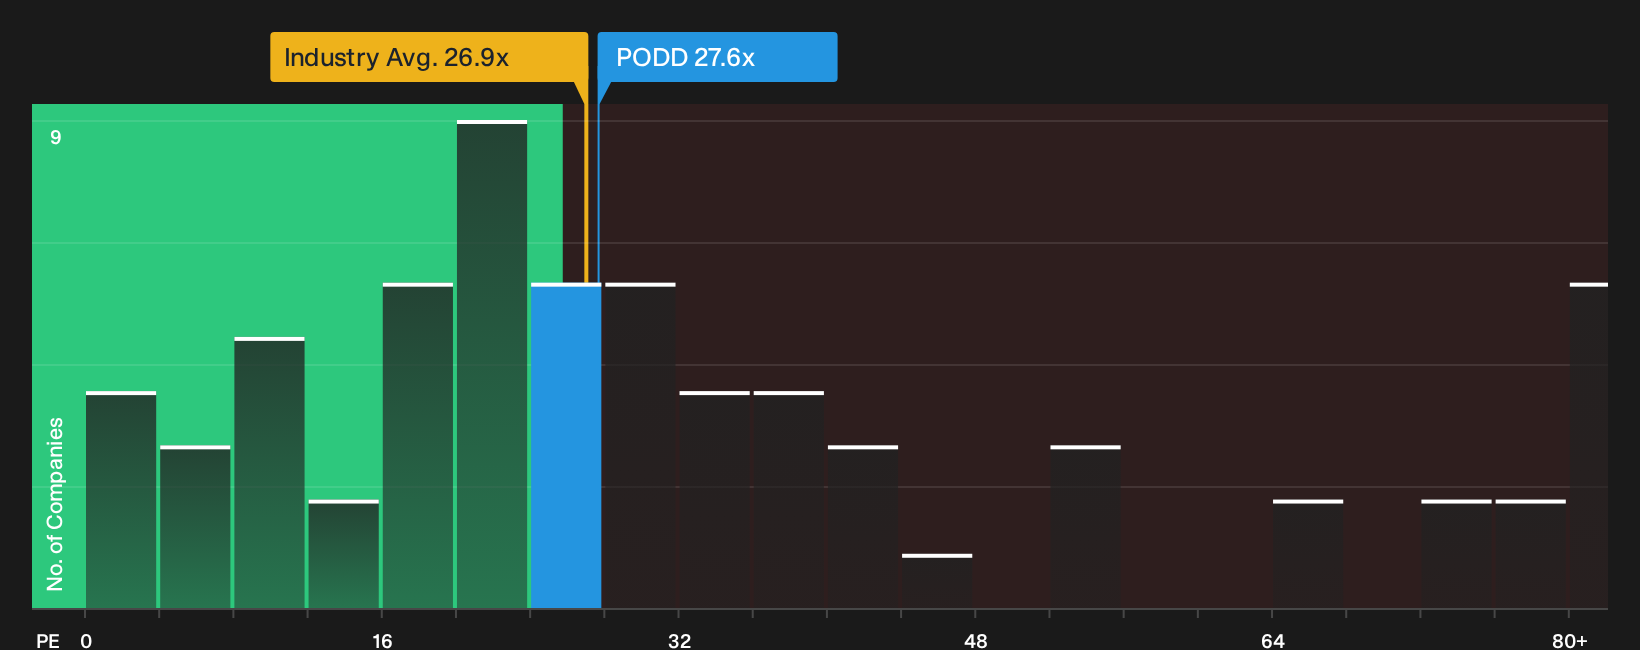
The first fair value story suggests Insulet is 11% undervalued. A simple earnings multiple paints a sharper picture. At a 27.6x P/E, PODD trades a touch richer than the US Medical Equipment industry on 26.9x, but below a 30x fair ratio estimate. This implies some cushion if sentiment improves, yet also less room if sector multiples compress.
In practical terms, that means the stock looks cheaper than similar peers on this framework while still pricing in a premium to the wider industry. The key question is whether you think Insulet has earned that gap or not.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Insulet leaves you on the fence, move quickly to test the numbers yourself and pressure test the thesis. To see the specific bright spots investors are focused on, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Insulet?
If Insulet’s setup has your attention, do not stop here. The next strong addition to your portfolio could be sitting in plain sight.
- Spot potential bargains early by scanning our 21 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Strengthen your downside protection and review the 30 resilient stocks with low risk scores that score well on resilience and financial stability.
- Target quality balance sheets by running through the list of solid balance sheet and fundamentals (24 results) that combine prudent debt levels with sound fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com