


CRA International (CRAI) is back in focus after reporting higher revenue and earnings per share, and management has lifted its outlook. This shift has coincided with a sharp recent share price move.
The raised outlook appears to have reset expectations around CRA International, with a 24.38% 30 day share price return and a 13.26% move over the past week suggesting momentum is building. The 3 year total shareholder return of 116.64% shows a strong longer term track record.
Scan other consulting and professional services stocks showing similar earnings momentum with our hand picked 21 high quality undiscovered gems alongside CRA International.
For CRA International, the sharp rerating came right after better results and a higher outlook, which puts a simple question in front of you: Is this jump mostly business driven, or does sentiment now run ahead of valuation?
Most Popular Narrative: 20% Undervalued
The prevailing narrative pegs CRA International’s fair value at $250.50 using a 7.87% discount rate, compared with the last close at $201.59. That gap frames the current share move as potentially grounded in fundamentals rather than just momentum.
CRA International is investing heavily in expert recruitment and retention, with tens of millions of dollars in forgivable loans and retention awards and around 30 new vice presidents ramping ahead of expectations. This can support future utilization, revenue growth and EBITDA dollars once these hires fully mature.
See why 7 investors see CRA International as 20% undervalued.
Result: Fair Value of $250.50 (UNDERVALUED)
Still, two pressure points sit in the background for CRA International: heavy senior hiring costs and higher credit facility borrowings that could squeeze flexibility if activity cools.
Find out about the key risks to this CRA International narrative.
Another View On CRA International’s Valuation
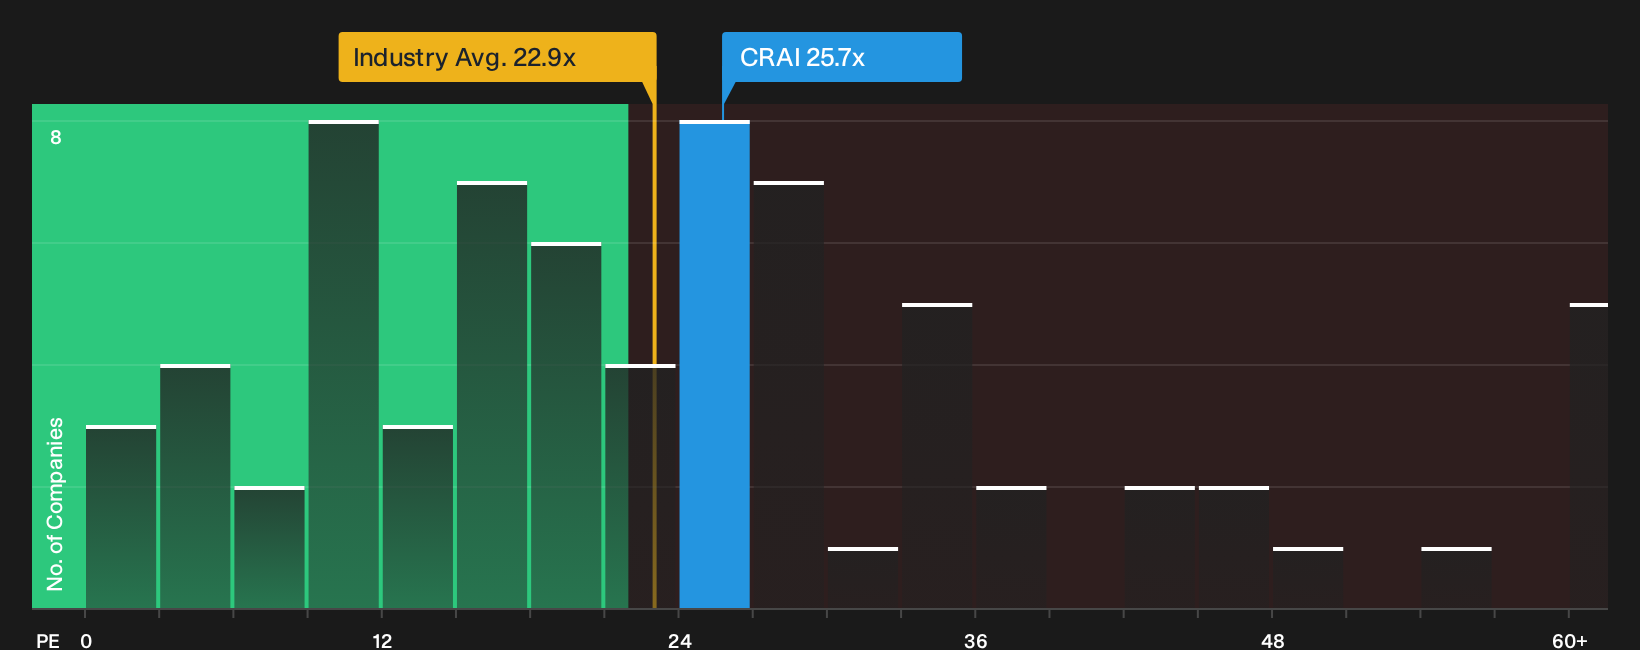
There is a clear gap between that $250.50 fair value and what CRA International looks like on simple earnings multiples. The stock trades on a P/E of 25.7x, richer than the US Professional Services average at 23.1x and well above its own fair ratio of 16.1x, which points to meaningful valuation risk if sentiment cools.
Put differently, the market is pricing CRA International well ahead of both the wider industry and the fair ratio that earnings history points to. This leaves you asking whether the stronger narrative or the colder multiple will set the next move for this stock.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on CRA International is clearly split, with both enthusiasm and caution in play. Consider acting promptly, scrutinise the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CRA International?
If CRA International has your attention, do not stop here. Use the same structured approach across other opportunities and let the data do the heavy lifting.
Spot companies investors often overlook yet are backed by strong fundamentals when you scan our curated list of 21 high quality undiscovered gems.
Target resilient balance sheets and robust financial footing by filtering for businesses in the list of solid balance sheet and fundamentals (24 results).
Prioritise resilience and controlled risk by focusing on companies highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com