


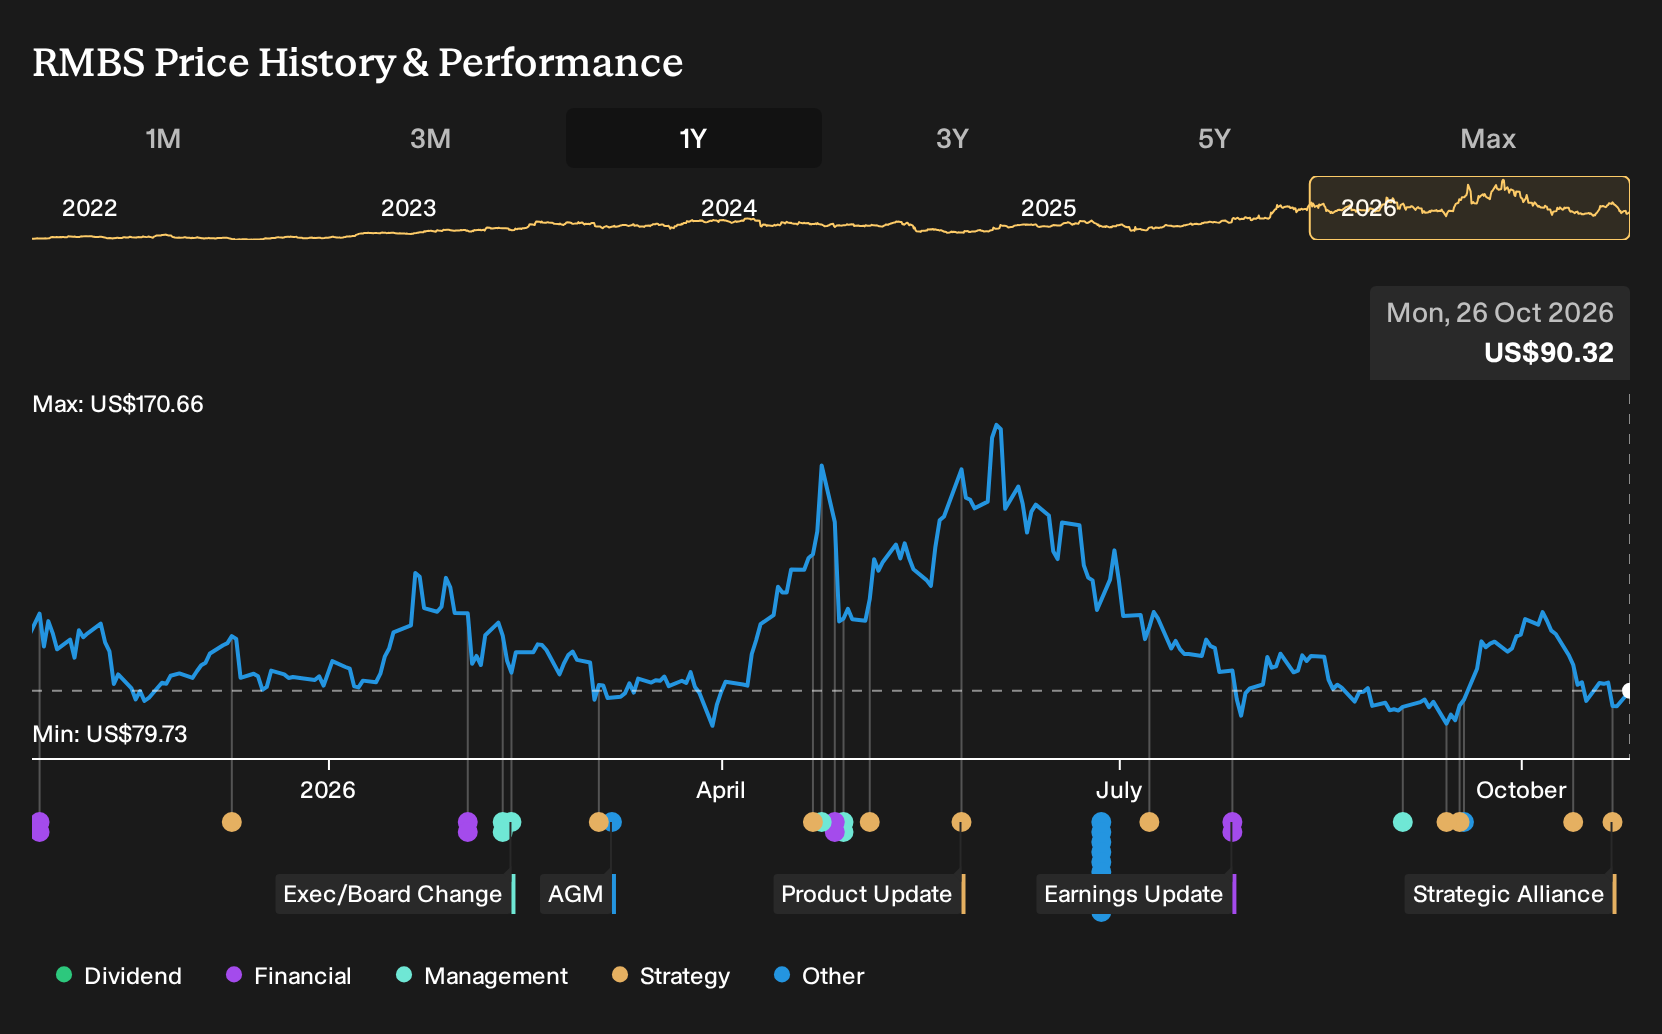
- Rambus reported third quarter 2026 revenue of US$218.29 million and net income of US$74.57 million, along with guidance for GAAP diluted EPS of US$0.68 to US$0.76 in the fourth quarter.
- The company paired this earnings update with a multifaceted ChipAgents agreement that introduces agentic AI across its chip design workflows and includes a direct investment in the partner.
- This article examines how Rambus' stronger quarterly profitability and its ChipAgents AI collaboration contribute to the broader investment narrative.
Scan how Rambus' AI and memory moves compare with other potential beneficiaries across AI hardware by reviewing the hand-picked 55 AI infrastructure stocks in one place.
Rambus Investment Narrative Recap
To own Rambus, you need to believe its memory interface and IP engine can keep turning AI and data center demand into solid earnings, even with supply bottlenecks and legal overhangs. The latest quarter, with revenue of US$218.29 million and net income of US$74.57 million, reinforces that the operating model is working today.
The key near term catalyst is continued execution on high margin chips and licensing, while capacity constraints and cost pressure remain live issues. Fourth quarter GAAP EPS guidance of US$0.68 to US$0.76 frames expectations clearly. If margins or shipments slip from here, the current growth narrative becomes harder to sustain.
The ChipAgents agreement is the most interesting development alongside the earnings. Rambus is rolling the platform out across chip and silicon IP design and verification, aiming to speed development cycles and improve Quality of Results in customer designs. That sits directly in the area where investors tend to focus most attention: how efficiently the portfolio can track AI centric standards and form factors.
There is also a capital allocation angle. Rambus has taken a direct stake in ChipAgents, so execution risk is not just technical but also financial. If agentic AI tools do raise throughput and help the business bring PMICs, MRDIMM solutions and security IP to market more predictably, that would feed directly into the core catalysts investors already focus on, such as product ramps and licensing wins.
Rambus' analyst narrative points to US$1.2b of revenue and US$474.9 million of earnings by 2029. This lines up with an assumed 17.4% yearly revenue growth rate and requires roughly a doubling in earnings from US$239.7 million today to reach those consensus expectations.
Uncover why Rambus' fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into the ChipAgents catalyst. The most optimistic Rambus analysts were already modeling about US$1.3b of revenue and US$906.6 million of earnings by 2029 before this update, far above consensus. You can use this quarter’s AI and earnings news to test which narrative you find more convincing.
Explore 2 other Rambus fair value estimates, including one that suggests up to 57% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rambus research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rambus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rambus' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rambus?
Rambus can be a useful anchor for your research, but a stronger portfolio usually leans on several different engines of return. Use the Simply Wall St Screener to line up other stocks against the same earnings quality, balance sheet, and risk filters you care about most.
- For investors who care about resilient businesses with steadier risk profiles, start with a curated set of 30 resilient stocks with low risk scores that may better match your comfort level.
- If dependable income is a priority, scan for payout candidates in the 5 dividend fortresses and see which yield and coverage combinations fit your goals.
- To widen the research funnel beyond the usual watchlists, broaden your search with a 21 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com