


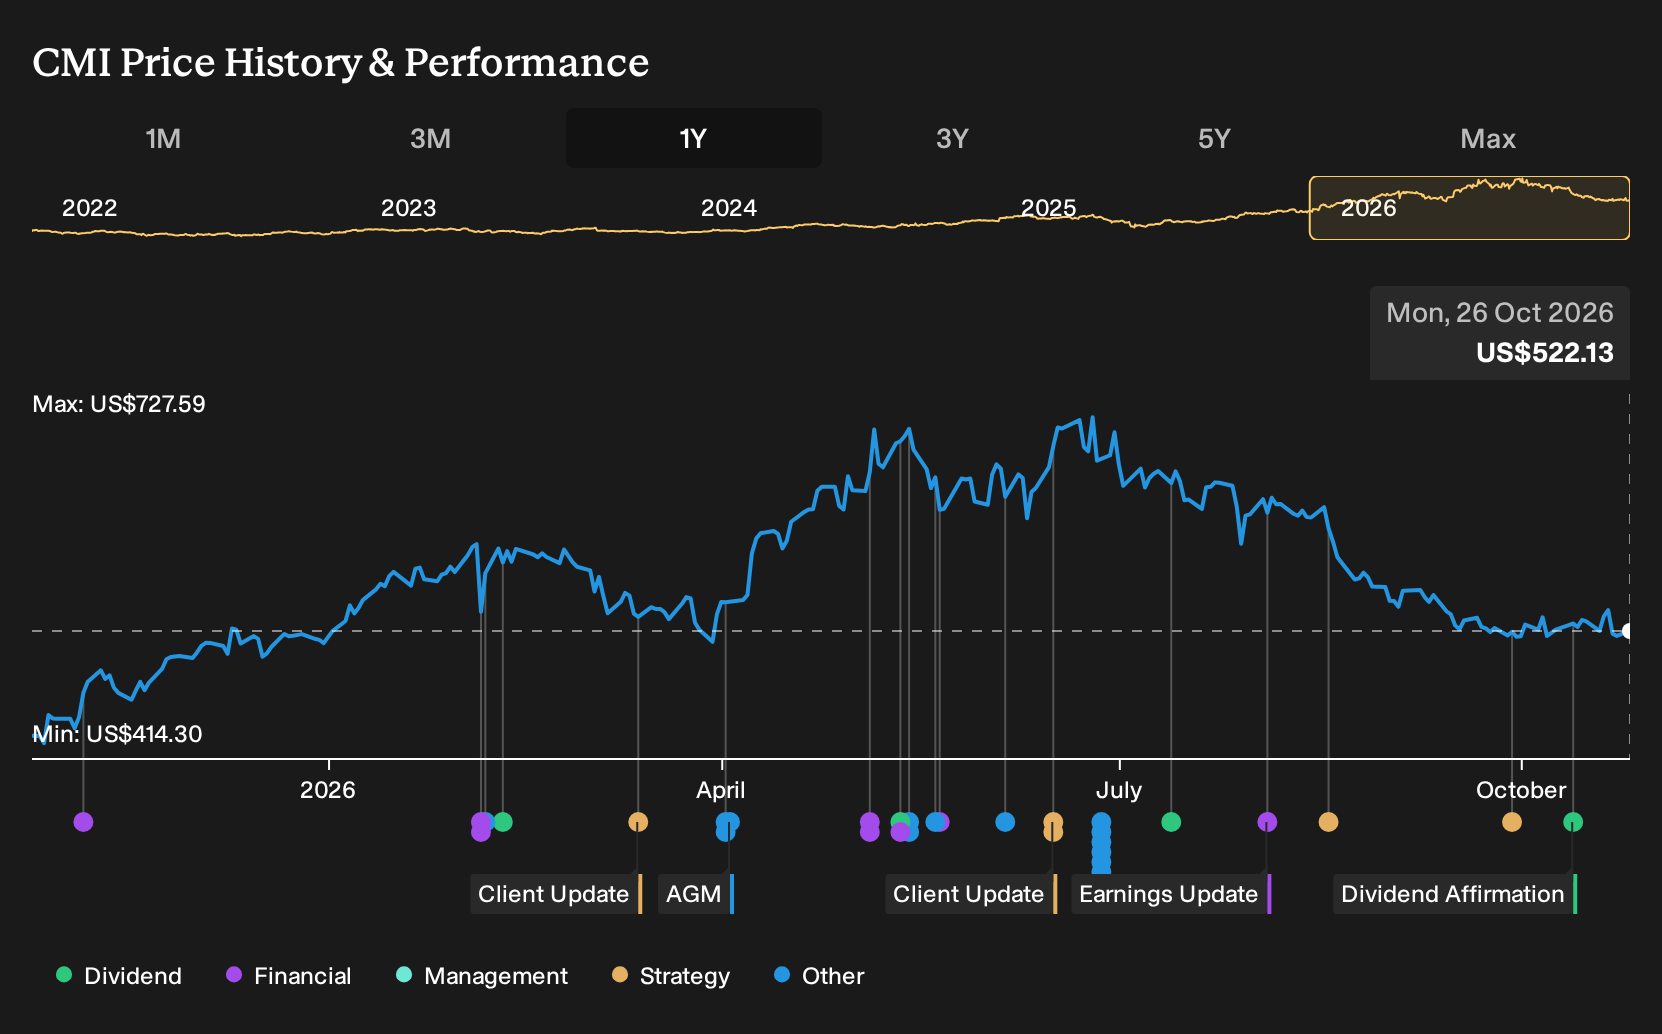
- Cummins' board declared a quarterly common stock cash dividend of US$2.20 per share, payable on December 3, 2026, to holders of record on November 20, 2026.
- The firm paired this dividend decision with expectations for stronger fiscal Q3 2026 profitability and an upgraded 2026 revenue outlook, tied to a multiyear hyperscaler supply deal and added plant capacity.
- Now the focus shifts to how Cummins' upgraded 2026 revenue outlook, driven by the hyperscaler agreement, could reshape its investment narrative.
Cummins Investment Narrative Recap
To own Cummins, you need to believe the engine, components, and power generation franchise can keep turning a strong data center order book and new capacity into solid earnings, while losses in Accelera stay contained. The upgraded 2026 revenue outlook tied to the hyperscaler deal keeps that data center theme firmly in focus.
In the near term, the main swing factor is whether Q3 2026 results confirm that higher volumes in Power Systems are flowing through to margins, rather than repeating past EPS misses. The key risk remains cost pressure from incentives and tariffs, plus ongoing Accelera losses that could dilute any operating upside.
The fresh quarterly dividend declaration of US$2.20 per share matters less for growth and more for what it signals about Cummins’ confidence in cash generation. It fits with a long running pattern of capital returns and may reassure investors who care about income alongside exposure to data center and engine cycles.
For catalysts, that payout policy only really works if the multi year data center demand story and high horsepower investments translate into durable profitability, while Accelera’s drag narrows over time. If margins keep feeling pressure from tariffs or cost inflation instead, the dividend alone is unlikely to offset concerns about earnings quality.
What the Cummins forecasts actually bake in
Cummins' narrative projects revenue of US$46.2b and earnings of US$5.8b by 2029, based on analyst models that assume 10.0% annual top line growth and an increase in profit margins from 7.8% today to 12.5% in three years. That path implies earnings today of US$2.7b would need to rise by US$3.1b to meet the 2029 consensus target.
Uncover why Cummins' fair value indicates a 38% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate angle you might explore is the bullish catalyst around Cummins’ multiyear data center buildout. The most optimistic analysts were already pencilling in revenue of US$50.5b and earnings of US$6.4b by 2029, versus US$46.2b and US$5.8b for consensus, before this dividend and hyperscaler news even landed. That gap shows how far opinions on Cummins can stretch and why fresh information like this payout and upgraded 2026 outlook could push those narratives in very different directions.
Explore 3 other Cummins fair value estimates, including one that suggests as much as 71% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cummins research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cummins' overall financial health at a glance.
Looking for more investment ideas beyond Cummins?
If the Cummins story has sharpened your thinking, keep that momentum going by scanning for other businesses that fit your preferred mix of quality, value, and risk using the Simply Wall St Screener.
- If you want potential bargains backed by solid fundamentals, start with a curated set of 29 high quality undervalued stocks that could merit a closer look alongside Cummins.
- For investors who care most about resilience, consider companies filtered for balance sheet strength and financial robustness through our list of solid balance sheet and fundamentals (24 results) to round out your watchlist.
- When you are hunting for opportunities the broader market may be overlooking, use the screener focused on 21 high quality undiscovered gems and see what else fits your thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com