


Forbo Holding (SWX:FORN) has put a sweeping transformation roadmap on the table, shifting its focus from products to customer and market segments. This move directly targets profitability and long term resilience.
Recent trading tells a mixed story. Forbo Holding’s share price is CHF878.0 after a 1-day share price return of 2.09%, yet the 7-day and 30-day share price returns are down 7.38% and 4.57%. The 1-year total shareholder return of 17.77% contrasts with a 5-year total shareholder return that is down 44.99%, which hints that sentiment has improved in the short run, while longer term confidence is still rebuilding around the new transformation roadmap.
Compare Forbo Holding's repositioning with other companies where profitability and balance sheet strength are front and center by scanning our curated 223 resilient stocks with low risk scores list.
So is Forbo Holding’s sharp repositioning a sign that the underlying operations are turning a corner, or has sentiment simply swung ahead of what the fundamentals justify, as the valuation now implies?
Price-to-Earnings of 19x: Is it justified?
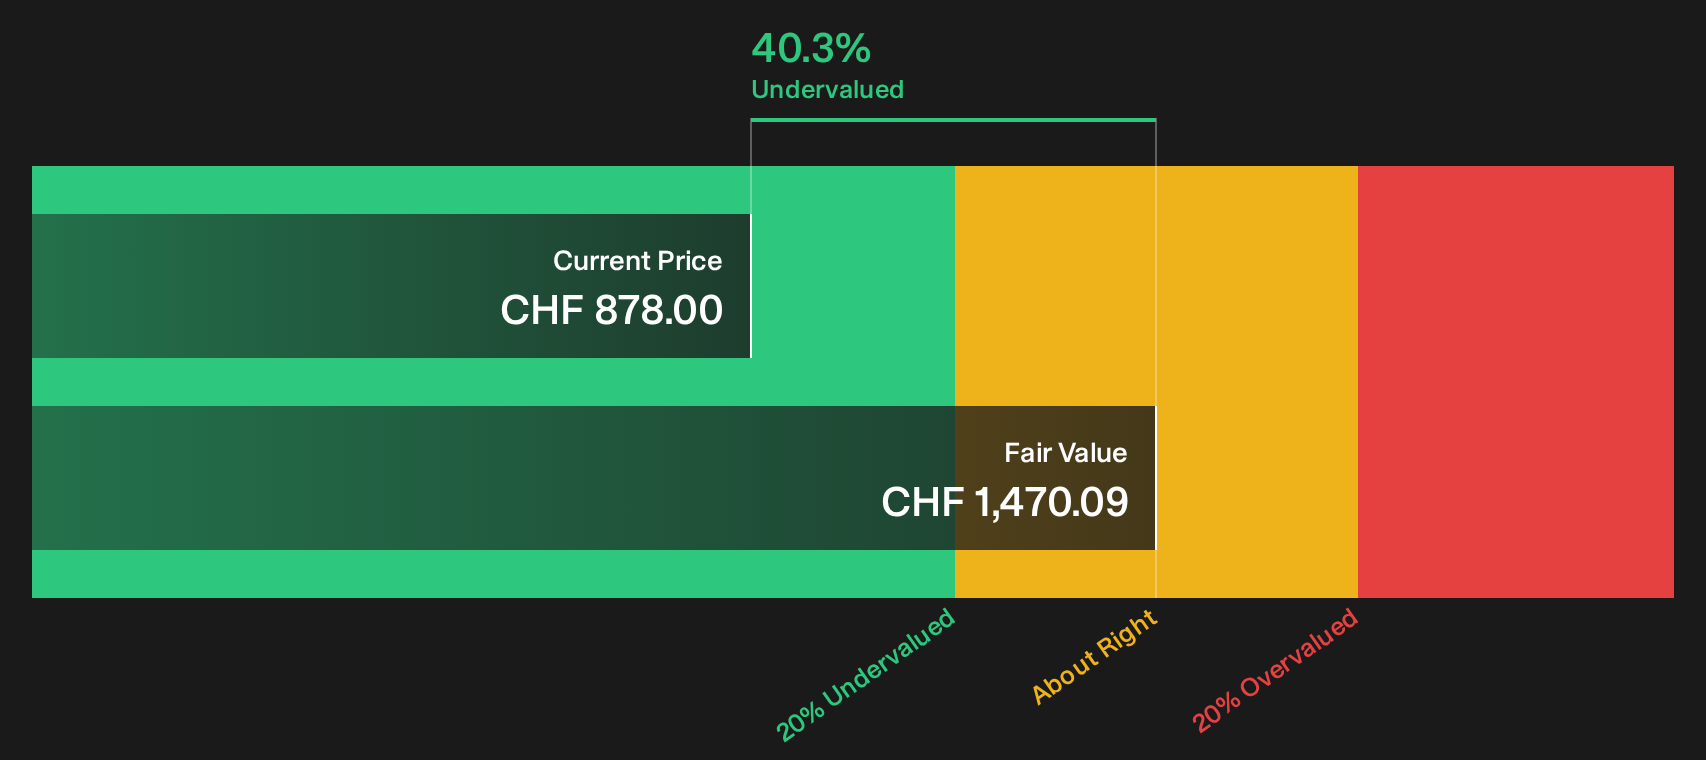
On simple valuation math, Forbo Holding trades on a P/E of 19x, which screens as inexpensive compared to several benchmarks despite a CHF878 share price and a 40.3% discount to an internal fair value estimate.
The P/E ratio compares what you pay per share today to the earnings that Forbo Holding generates per share over a year. For a building and industrial supplier that earns CHF66.3m on CHF1.08b of revenue with high quality earnings, this lens helps you gauge how much of those profits the market is currently willing to pay for.
Here, the market is assigning a lower tag than multiple reference points. The current 19x P/E is presented as good value against the European Building industry average of 23.1x and a peer group on 30x. It is also below an estimated fair P/E of 23.8x. That level is described as one the valuation work suggests investors might eventually gravitate toward if the forecast 17.1% annual earnings growth and reliable 2.85% dividend remain in place.
Against that backdrop, the discount looks punchy relative to both sector norms and the fair ratio, even though return on equity is described as low at 10% and recent net profit margins declined from 7.3% to 6.1%.
Explore the SWS fair ratio for Forbo Holding.
Result: Price-to-Earnings of 19x (UNDERVALUED)
Still, Forbo Holding’s 5 year total shareholder return is down 44.99%, and recent margin pressure could quickly challenge any renewed confidence in the valuation story.
Find out about the key risks to this Forbo Holding narrative.
Another view on Forbo Holding’s value
The P/E points one way, but the SWS DCF model points even harder. On that framework, Forbo Holding at CHF878 is described as trading below an estimated future cash flow value of CHF1,470.09, which frames the stock as undervalued on cash generation potential rather than just accounting earnings.
For readers who want to see how this cash flow view is built and where the key sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Forbo Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Forbo Holding’s valuation story is mixed, and that is exactly why it can pay to look at the data first hand. If you want to see what the optimism is building on, review the 4 key rewards
Looking for more investment ideas beyond Forbo Holding?
If you stop with Forbo Holding, you risk missing other opportunities that fit your style even better, so widen your search before deciding your next move.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (207 results) for companies that keep financial risk in check.
- Hunt for quality at a discount by reviewing the 610 high quality undiscovered gems that pair strong business fundamentals with relatively overlooked share prices.
- Focus on stability and risk control by filtering companies through the 223 resilient stocks with low risk scores to see which stocks score well on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com