


Guardian Pharmacy Services (GRDN) is back in focus after management reported revenue growth, stronger adjusted EBITDA and a higher full year outlook, prompting investors to reassess how these operating gains line up with the current share price.
Guardian Pharmacy Services has enjoyed a strong year-to-date share price return of 32.71%, even though the stock has eased back with a 30 day share price return of down 4.90% and a 90 day share price return of down 6.38%, leaving the latest close at $39.19. The recent pullback hints that investors are recalibrating expectations after a strong run. At the same time, a 1 year total shareholder return of 34.91% signals that, over a longer stretch, momentum has still favoured shareholders as fresh earnings guidance and cash flow expectations filter into pricing.
Scan other healthcare operators showing similar guidance momentum and pricing pressure resilience through the curated list of solid balance sheet and fundamentals (24 results).Guardian Pharmacy Services now looks like a stronger operator, but after a 1 year total return close to 35% and a recent pullback, are you still paying a fair price for that quality or stretching for it?
Most Popular Narrative: 20.8% Undervalued
Against the latest close of $39.19, the most followed narrative pegs Guardian Pharmacy Services at a fair value of $49.50. This implies a material valuation gap that hinges on how investors view its growth runway and margin potential.
Active but disciplined M&A, supported by a debt free balance sheet, strong cash conversion above 60% and a flexible shelf registration, positions Guardian to accelerate regional density and national scale, driving incremental revenue and operating leverage.
Ongoing negotiations with payers, potential evolution toward more value based arrangements and demonstrated ability to offset policy headwinds such as those tied to the Inflation Reduction Act should stabilize reimbursement, protect net margins and support durable EPS growth.
See why 2 investors see Guardian Pharmacy Services as 21% undervalued.
Result: Fair Value of $49.50 (UNDERVALUED)
Still, the narrative around Guardian Pharmacy Services depends on policy risk staying contained and on recent acquisitions reaching expected profitability without dragging margins for longer.
Find out about the key risks to this Guardian Pharmacy Services narrative.
Another View: Guardian Pharmacy Services On Earnings Multiples
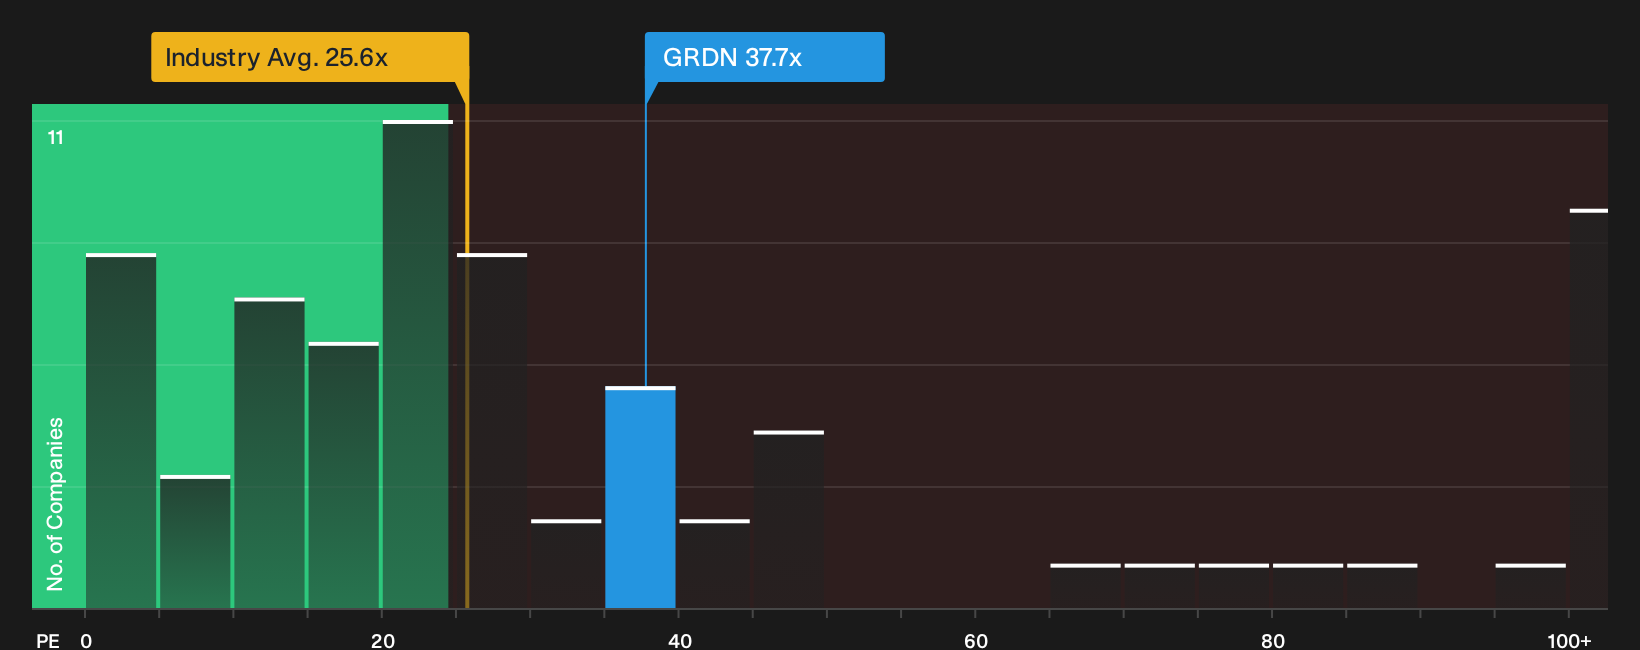
On the other side of the ledger, Guardian Pharmacy Services trades on a P/E of 37.7x compared with 25.7x for the wider US Healthcare group and a peer average of 36.3x, while the fair ratio for the stock is 24.7x. That gap points to meaningful valuation risk if sentiment cools or earnings forecasts are trimmed.
For a closer look at how those earnings multiples compare with what the numbers suggest the ratio could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimism runs through much of the Guardian Pharmacy Services story, but you still need to stress test the numbers yourself and not rely on headlines. To see what investors see as the upside case in detail, review the 4 key rewards.
Looking for more Guardian Pharmacy Services style ideas?
If Guardian Pharmacy Services has sharpened your focus on quality and price, do not stop here. Use these focused stock ideas to pressure test your next move.
- Zero in on potential mispricings by hunting through 29 high quality undervalued stocks that align with strong fundamentals and a margin of safety mindset.
- Anchor your portfolio with steadier cash returns by scanning 5 dividend fortresses that aim to combine yield with balance sheet strength.
- Dial down portfolio risk by filtering for 30 resilient stocks with low risk scores that keep financial red flags to a minimum while still offering upside potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com